
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Principal Financial Group (PFG) Undervalued Following Its Credit Facility Refinance?
Principal Financial Group (PFG) refreshed its financing toolkit on September 9, entering an amended five year credit facility that refinances its prior revolver and extends access to unsecured bank funding.
That extra liquidity support comes as Principal Financial Group’s share price has climbed to US$116.90, with a year to date share price return of 30.73% and a 1 year total shareholder return of 45.79%, signalling strong positive momentum that has built steadily rather than spiked.
Scan how Principal Financial Group’s refinancing move compares with other financially resilient insurers by reviewing our curated list of 11 resilient stocks with low risk scores in similar sectors.
Principal Financial Group now trades above the average analyst target yet screens at a sizeable intrinsic discount. Is the market being overly careful, or seeing risks that a headline valuation gap overlooks?
Most Popular Narrative: 7% Overvalued
Principal Financial Group’s most followed valuation narrative pegs fair value at $109.58, below the recent $116.90 close. This frames the refinancing and share price strength against expectations for steadier rather than explosive progress.
The analysts have a consensus price target of $109.58 for Principal Financial Group based on their expectations of its future earnings growth, profit margins and other risk factors.
In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be $19.7 billion, earnings will come to $2.5 billion, and it would be trading on a PE ratio of 10.9x, assuming you use a discount rate of 7.2%.
See why 7 investors see Principal Financial Group as 7% overvalued.
Result: Fair Value of $109.58 (OVERVALUED)
Still, Principal Financial Group’s narrative could be challenged if fee revenue softens further from client risk-off behavior, or if higher corporate expenses persist and squeeze net margins.
Find out about the key risks to this Principal Financial Group narrative.
Another View on Principal Financial Group’s Value
The earlier narrative framed Principal Financial Group as 7% overvalued using analyst targets. A different lens tells a very different story. Our DCF model, based on future cash flows, points to a fair value of $228.68 versus the current $116.90, which implies the shares screen as materially undervalued on that framework.
That kind of gap can reflect conservative cash flow assumptions in the market or sharper sensitivity to risks such as fee pressure, funding mix and earnings volatility. It raises a straightforward question for you as an investor: Is the price anchoring more on short term sentiment rather than on the long term cash generation implied by the SWS DCF model?
Look into how the SWS DCF model arrives at its fair value.
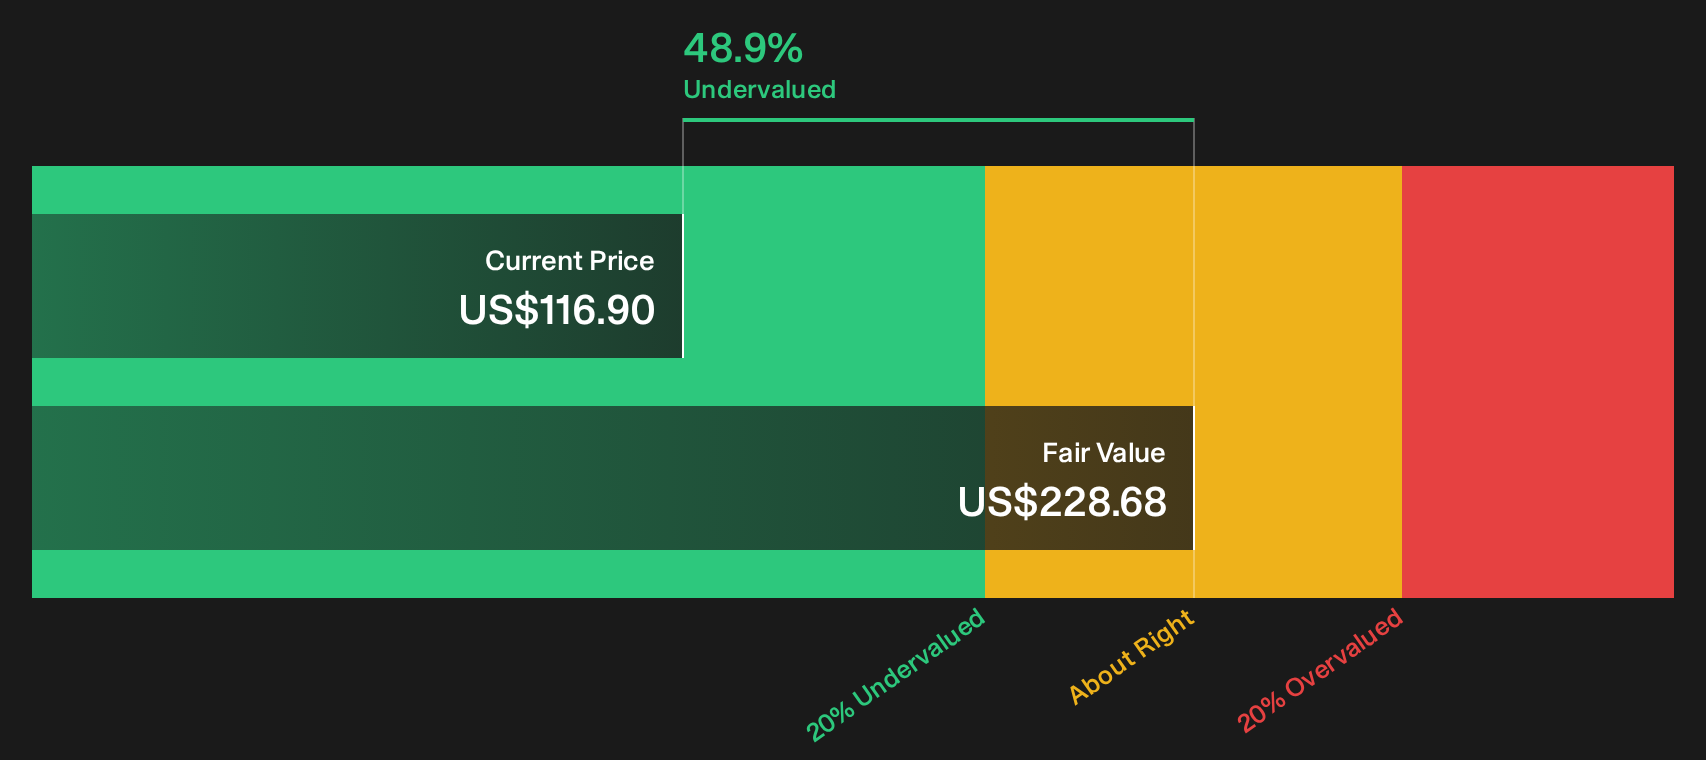
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Principal Financial Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Seen enough to understand the tone of this Principal Financial Group story? Move quickly from headline narratives to the underlying numbers and form your own stance by reviewing the 4 key rewards.
Looking for more Principal Financial Group investment ideas?
Do not stop with Principal Financial Group. Use the wider market as your hunting ground and let focused screeners surface opportunities you might otherwise miss.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (23 results). These can help anchor a portfolio when conditions change.
- Hunt for mispriced quality by reviewing the 35 high quality undervalued stocks. These combine supportive cash flows with fundamentals that may not be fully reflected in current prices.
- Build a cash flow stream that works harder for you by checking out the 6 dividend fortresses. These offer substantial yields with an emphasis on resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com