
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Planned Dividends Change The Bull Case For PagSeguro Digital Stock (PAGS)?
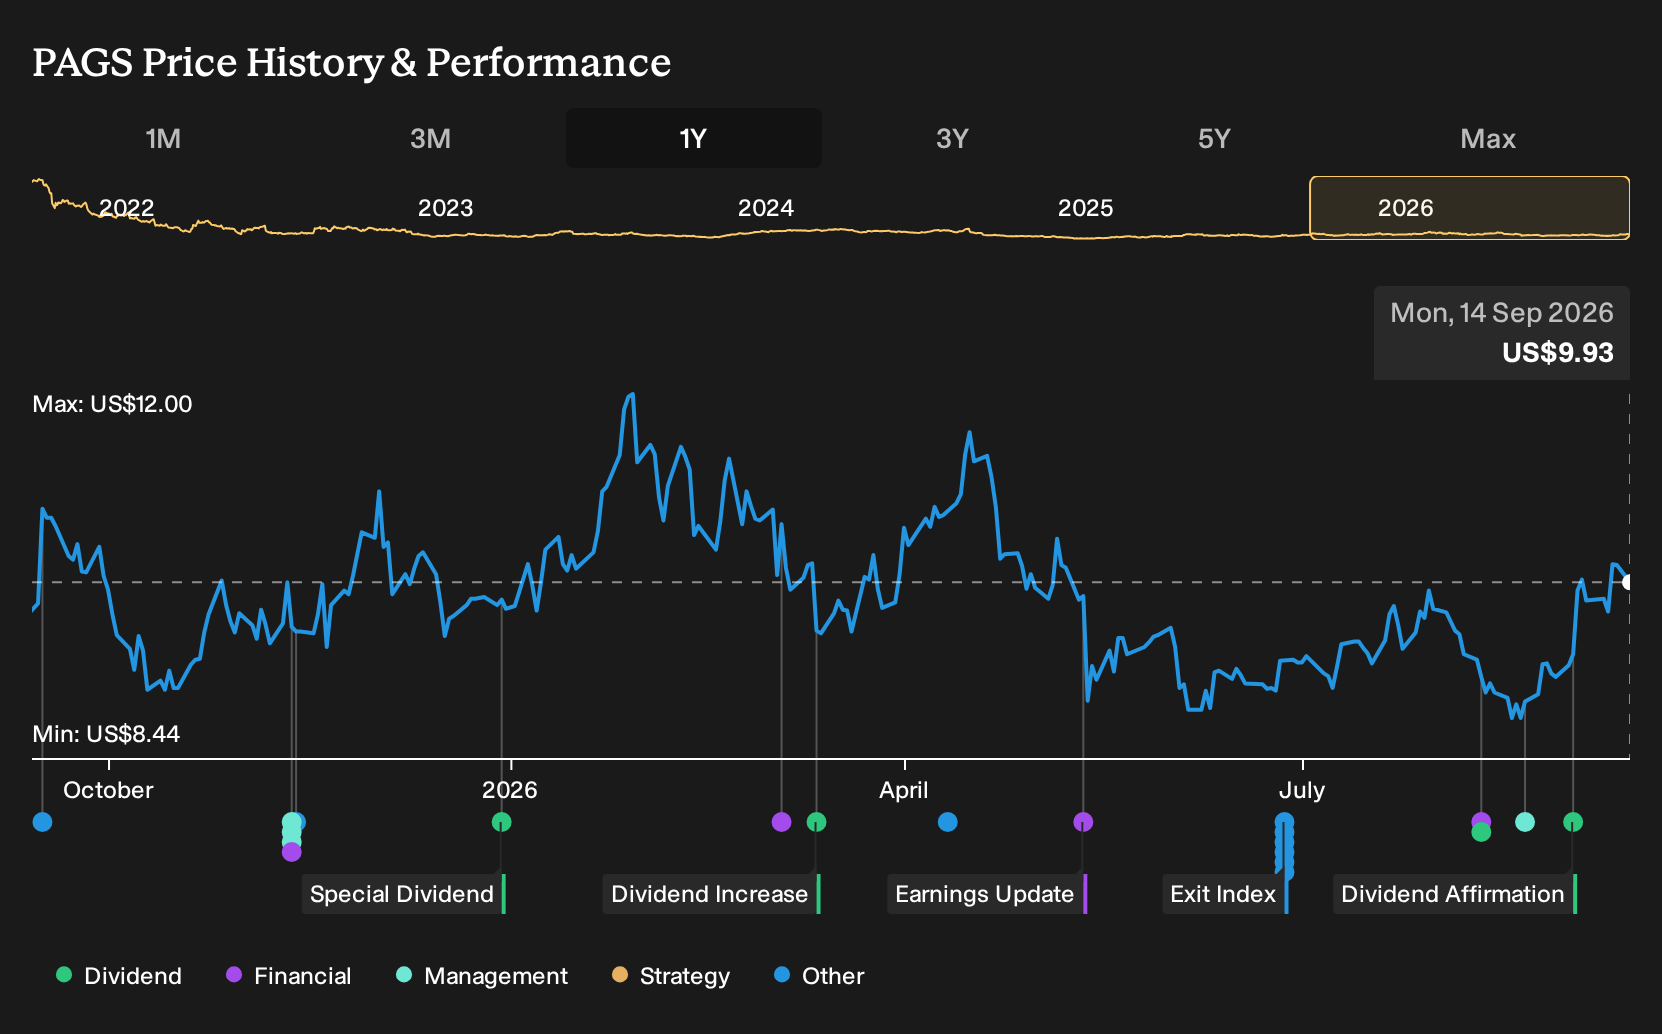
- PagSeguro Digital announced in September 2026 that it plans to distribute at least BRL 2.0b in dividends across 2027 and 2028, subject to market and financial conditions and final approval by the board.
- The planned BRL 1.0b per year payout signals a shift toward returning excess capital, which could influence how investors view PagSeguro Digital's balance between growth investment and shareholder distribution.
- This article examines how PagSeguro Digital's investment narrative is reframed by this planned BRL 2.0b multi year dividend commitment.
Scan how PagSeguro Digital’s new dividend plan compares with other payout focused opportunities by reviewing the hand picked 6 dividend fortresses in the market today.
PagSeguro Digital Investment Narrative Recap
To own PagSeguro Digital, you need to believe its payment and banking ecosystem can keep deepening engagement with small merchants and consumers while managing funding costs and credit risk. The planned BRL 2.0b dividend path does not change the near term swing factor, which still sits in how effectively the firm balances credit growth with asset quality.
The biggest operational risk remains pressure on margins from higher SELIC driven funding costs, client repricing and competition from PIX that can weigh on transaction yields. The dividend framework looks incremental rather than transformative here, unless capital returns begin to constrain credit expansion, PagBank investments or technology spending.
The fresh dividend guidance ties directly into an existing capital return lever. PagSeguro Digital has been running a sizeable buyback program that reduces share count and lifts earnings per share, and the multi year dividend expectation adds another layer to that capital allocation story. Both tools draw from the same pool of excess cash generation.
For shareholders, the key question is how far management can push these payouts while still funding credit portfolio growth, PagBank ecosystem monetization and technology upgrades. If funding costs stay elevated or PIX competition keeps transaction yields under pressure, the trade off between dividends, buybacks and reinvestment becomes a more immediate catalyst and also a source of risk.
What PagSeguro Digital’s Dividend Path Implies About Growth Assumptions
PagSeguro Digital’s planned dividend track sits next to a consensus story that still leans heavily on earnings growth and moderate top line expansion. Analysts in the latest reports are working with revenue increasing by 5.8% each year over the next three years, while profit margins are expected to move from 10.8% today to 12.2% by 2029.
On the earnings line, forecasts point to R$2.9b of profit by about 2029 compared with R$2.1b today. That is an earnings increase of roughly R$0.8b on current levels, which is a sizable uplift for a business already running large credit and payments books. For a shareholder thinking about the multi year dividend, the important link is simple. The more this earnings bridge materialises, the more room there is for PagSeguro Digital to keep writing dividend cheques without starving PagBank or the acquiring operation of capital.
Those same analyst models that underpin the R$2.9b profit view also plug in revenue of R$23.5b by 2029 and a P/E multiple of 7x on those earnings. That compares with a reported P/E of 5.7x on current earnings and a 16.5x P/E for the broader US diversified financials sector referenced in the report. PagSeguro Digital’s dividend guidance, in that context, looks like a way of signalling confidence that the firm can grow into those numbers while still feeding cash back to shareholders, even if the absolute valuation multiple the market is willing to pay ends up lower or higher than the analyst sketch.
For you as an investor weighing capital returns against growth reinvestment, the core tension is clear. Analysts also expect the share count to shrink by about 4.92% per year over the next three years because of buybacks. That means earnings per share could rise faster than total profit if those buybacks continue, which can make the payout profile look healthier even if absolute earnings track closer to the more cautious R$2.3b scenario in the analyst range. The mix of dividends and repurchases is therefore not just about generosity but also about how management wants the earnings math to work on a per share basis.
PagSeguro Digital's narrative projects R$23.5b revenue and R$2.9b earnings by 2029. This is based on revenue growing 5.8% per year and an earnings increase of about R$0.8b from R$2.1b today.
Uncover why PagSeguro Digital's fair value indicates a 23% potential upside to its current price before the discount to PagSeguro Digital closes.
Exploring Other Perspectives
Some of the lowest ranked analysts focus on competitive pressure rather than dividends. They work with slower revenue growth of about 3.6% a year and earnings of roughly R$2.4b by 2029, compared with R$2.2b today. That more cautious view predates PagSeguro Digital’s dividend plan, so opinions may change as new information becomes available.
Explore 6 other PagSeguro Digital fair value estimates, including one that suggests it could be worth just $11.63.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your PagSeguro Digital research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PagSeguro Digital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PagSeguro Digital's overall financial health at a glance.
Looking For More Investment Ideas Beyond PagSeguro Digital?
Once you have a view on PagSeguro Digital, it often helps to compare it with other opportunities that have different risk and income profiles. The Simply Wall St Screener can surface a wide mix of alternatives so you can build a watchlist that matches your own goals instead of relying on a single story.
- If capital preservation sits high on your list, check out a group of companies that score well on stability by reviewing the 11 resilient stocks with low risk scores in the market today.
- For investors hunting for mispriced quality, scan a hand picked 15 high quality undiscovered gems that combine strong fundamentals with relatively low attention.
- If balance sheet strength is non negotiable for you, focus on businesses with sturdy finances by starting with this list of solid balance sheet and fundamentals (23 results) tailored to financial resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com