
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Exelixis (EXEL) Looks Fully Valued After FDA Review Delay
Exelixis (EXEL) is back in focus after the FDA extended its review of zanzalintinib plus atezolizumab for metastatic colorectal cancer by three months, following submission of updated safety and efficacy data.
Exelixis now trades at US$56.21, with recent headlines around zanzalintinib landing on a stock that has a 30 day share price return of 9.7% and a year to date share price gain of 28.98%. Total shareholder return of 183.60% over five years points to momentum that has been building over a longer stretch, despite a softer 7 day share price move as investors weigh the extended FDA review and a busy September conference schedule.
Scan how Exelixis fits within the wider oncology opportunity set and compare it with a hand picked group of cancer focused developers in our 15 high quality undiscovered gems.
Exelixis looks like a solid oncology business with meaningful products and late stage assets, yet the recent surge in the share price raises a sharper issue. Are you now paying up for that strength or still getting a reasonable deal?
Most Popular Narrative: 6% Overvalued
On the most followed view, Exelixis carries a fair value of $53 per share compared with the latest close at $56.21. This frames today’s strength as slightly ahead of that narrative. The gap is not huge, but it puts more weight on how you judge the durability of cabozantinib and the timing of any second franchise.
The company's substantial free cash flow, strong balance sheet, and disciplined capital allocation (including aggressive share repurchases and prioritization of high-probability, high-value R&D programs) position Exelixis to invest in next-generation discovery and strategic partnerships, which has the potential to improve operating leverage and net margins over time as the product portfolio scales.
See why 67 investors see Exelixis as 6% overvalued.
Result: Fair Value of $53 (OVERVALUED)
Still, the Exelixis story can change quickly if cabozantinib faces faster than expected competitive pressure, or if zanzalintinib setbacks reshape confidence in a second franchise.
Find out about the key risks to this Exelixis narrative.
Another View: What Multiples Say About Exelixis
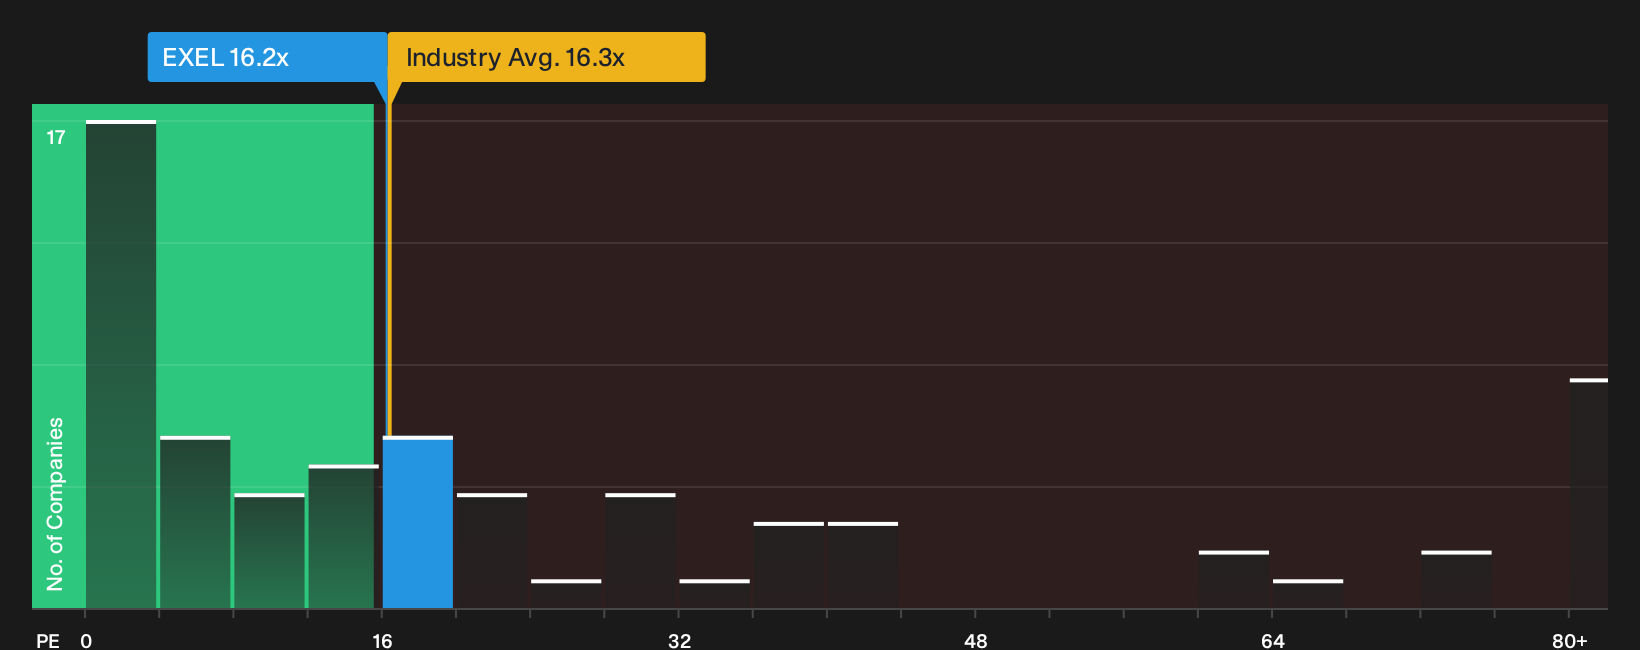
On raw multiples, Exelixis tells a very different story from the 6% overvalued fair value narrative. The stock trades on a P/E of 16.2x, compared with 82.7x for peers and 16.4x for the broader US Biotechs industry, while the fair ratio sits higher at 22.9x.
That mix points to a share price that screens as good value against both rivals and the fair ratio. This raises a basic question for investors: Is the analyst target too cautious, or is the multiple sending a noisy signal on future risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Exelixis leaves you undecided, move quickly to test the numbers yourself and stress test the upside narrative. To see what others view as the key positives worth tracking, review the 4 key rewards.
Looking for more Exelixis sized ideas?
If Exelixis has sharpened your radar, do not stop here. Use the Simply Wall Street Screener to surface fresh opportunities that fit your checklist.
- Target resilient compounders by running a filter for 11 resilient stocks with low risk scores that aim to keep portfolio volatility in check when headlines turn noisy.
- Hunt for mispriced opportunities by scanning a curated 35 high quality undervalued stocks that match solid fundamentals with what may be conservative market expectations.
- Strengthen the quality of your watchlist by focusing on a list of solid balance sheet and fundamentals (23 results) and avoid finding out too late that leverage was the real story.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com