
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Compass (COMP) Stock Looks Above Fair Value On Fresh Housing Split Warning
Compass has been through a volatile few years, and the share price now asks a simple question of investors: Is the current valuation supported by the company’s earnings power, or has the recent ride taken the stock ahead of what the income statement can justify?
- Compass has returned about 227.7% over the past 3 years, which puts a lot of pressure on its earnings to back up that move.
- Management is pointing to a housing market where price cuts are widespread and conditions differ sharply by segment, which can influence how quickly Compass converts sales activity into sustainable profit growth.
- There is a second opinion on Compass worth weighing. See what analysts think Compass's shares could be worth.
The stock's next move may depend on whether Compass's current earnings support the valuation investors are paying for today.
If you are weighing Compass against other opportunities tied to housing and broader earnings stories, it can help to line it up beside 35 high quality undervalued stocks.
Does Compass Look Pricey on Earnings?
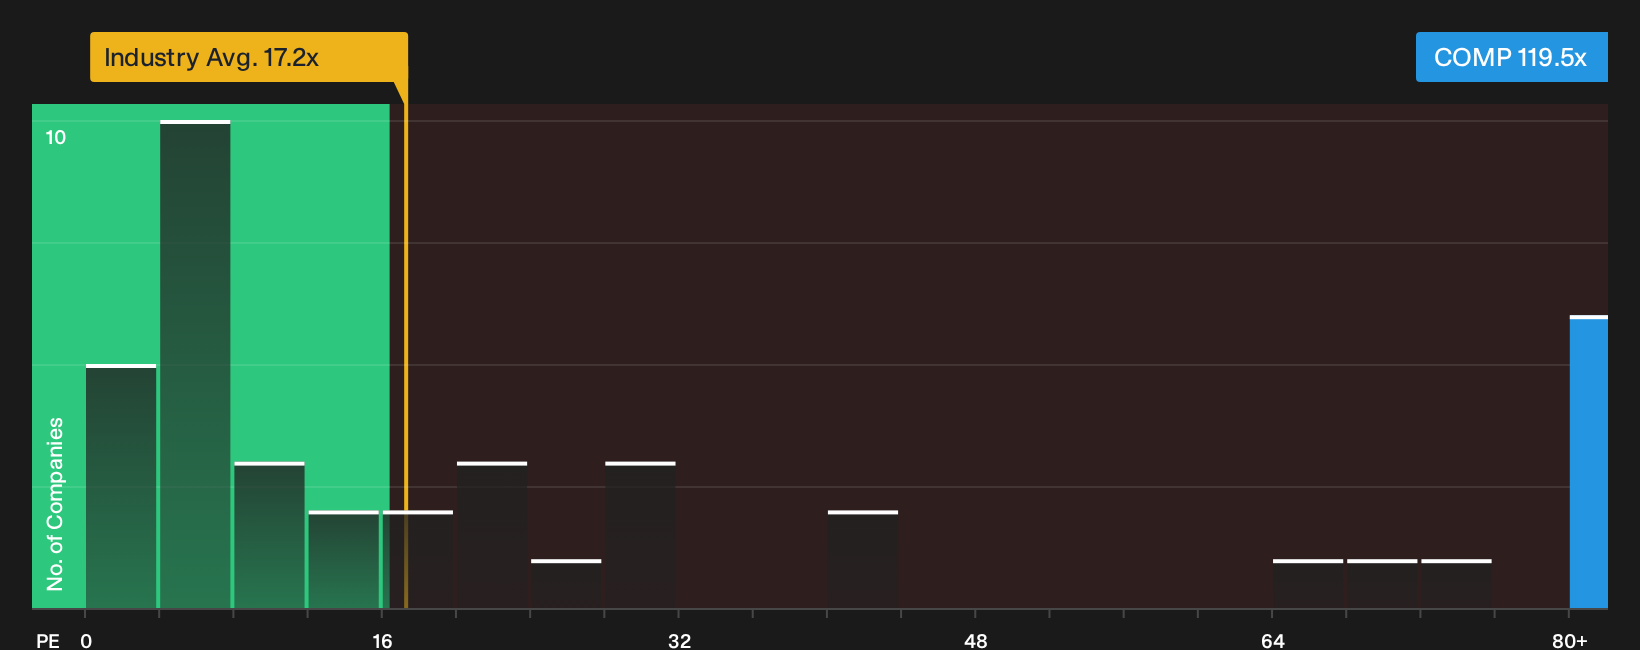
P/E makes sense for Compass because investors are weighing what they are paying today against the earnings it is already generating. On this yardstick, the stock trades on about 119.5x earnings, which is far above the wider real estate industry on roughly 17.2x and above its peer set near 86.0x. That kind of gap means you are paying a much higher price for each dollar of profit than for many other property focused businesses.
The Fair Ratio model, which adjusts the P/E you might expect for Compass based on its growth profile, margins, size and risk, sits well below the current multiple, so the shares screen as overvalued on this framework. Because management has flagged a split housing market with widespread price cuts in some segments, that rich P/E already assumes the business will handle those cross currents effectively. If that feels like a stretch for your risk tolerance, the current valuation could make alternative real estate or broader market options look more straightforward by comparison. Explore the numbers behind Compass's P/E valuation.
The Compass Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Compass' valuation puzzle leaves off. These short scenarios explain which paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today's price. Each one ties a fair value to a specific set of potential catalysts and risks, so you can monitor over time which version of Compass' story is actually unfolding. They are available on Simply Wall St's Community page.
One of the top community narratives on Compass: 31% undervalued
"Expansion into high-margin adjacent services and successful integration of acquisitions are increasing earnings potential and deepening the company's competitive moat..."
Discover why this Narrative puts Compass at 31% undervalued.
One more Compass cross check that belongs next to today’s price
There is one extra reference point that can help frame what you are seeing in Compass right now: where professional earnings models think this business could sit a few years from today. Explore where analysts expect Compass to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com