
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can Keymed Biosciences (SEHK:2162) Justify Its Valuation Following The Aeira Licensing Deal?
Keymed Biosciences (SEHK:2162) has moved back into focus after signing an exclusive licensing and commercialization agreement with Aeira that covers its IL-4Ra-targeted antibody Kangyueda across Southeast and Central Asia.
Recent trading has been choppy for Keymed Biosciences. The share price is up 2.60% over the past day to HK$74.95, yet the 7 day and 30 day share price returns are down 4.03% and 4.09%. The 90 day and year to date share price returns of 33.13% and 40.22% point to stronger momentum overall. That contrasts with a 1 year total shareholder return that slipped 1.25%. However, the 3 year and 5 year total shareholder returns of 36.27% and 44.69% suggest longer term holders have still seen gains as investors reassess growth potential and risk after the Aeira licensing deal and the recent non executive director resignation.
Capitalize on the renewed interest in Keymed Biosciences by scanning a curated 618 high quality undiscovered gems that could be quietly reshaping expectations before the wider market catches on.After the Aeira deal and the recent run, the puzzle is simple: Is Keymed Biosciences still pricing in only part of that opportunity, or has most of the upside already been pulled forward?
Price-to-Earnings of 24.4x: Is it justified?
On simple numbers, the market is paying a P/E of 24.4x for Keymed Biosciences at the last close of HK$74.95. This screens as good value versus some peers but expensive against others and its own fair ratio estimate.
The P/E multiple captures how much investors are willing to pay for each unit of current earnings. For a biotech developer like Keymed Biosciences, this ratio often reflects expectations around the commercial potential of its pipeline, the stability of its newly achieved profitability, and how durable those earnings could be.
Analysts expect revenue to grow 30.6% per year while earnings are forecast to decline 50.5% per year over the next three years. This hints that the market is paying up for top line expansion and licensed assets even as profits are expected to come under pressure. That tension shows up clearly in the modelled fair P/E of 6.7x, which is far lower than the current 24.4x level and signals a valuation that could move closer to that lower multiple if expectations cool.
The comparison with the broader Hong Kong Biotechs group is blunt. Keymed Biosciences trades on a 24.4x P/E against an industry average of 17.4x, so the stock carries a premium multiple in sector terms even though it still looks inexpensive compared to the 46x peer average used in the same preferred multiple check.
Explore the SWS fair ratio for Keymed Biosciences.
Result: Price-to-Earnings of 24.4x (OVERVALUED)
Still, the Aeira partnership could disappoint if regulatory outcomes or clinical results around Kangyueda fall short, and any slowdown in licensing activity would quickly challenge the current Keymed Biosciences narrative.
Find out about the key risks to this Keymed Biosciences narrative.
Another View on Keymed Biosciences: What the DCF Says
The P/E points one way, but the SWS DCF model points another. At HK$74.95, Keymed Biosciences is described as trading below an estimated future cash flow value of HK$120.77. That framing leans toward undervalued. So which signal do you trust when the next headline hits?
Look into how the SWS DCF model arrives at its fair value.
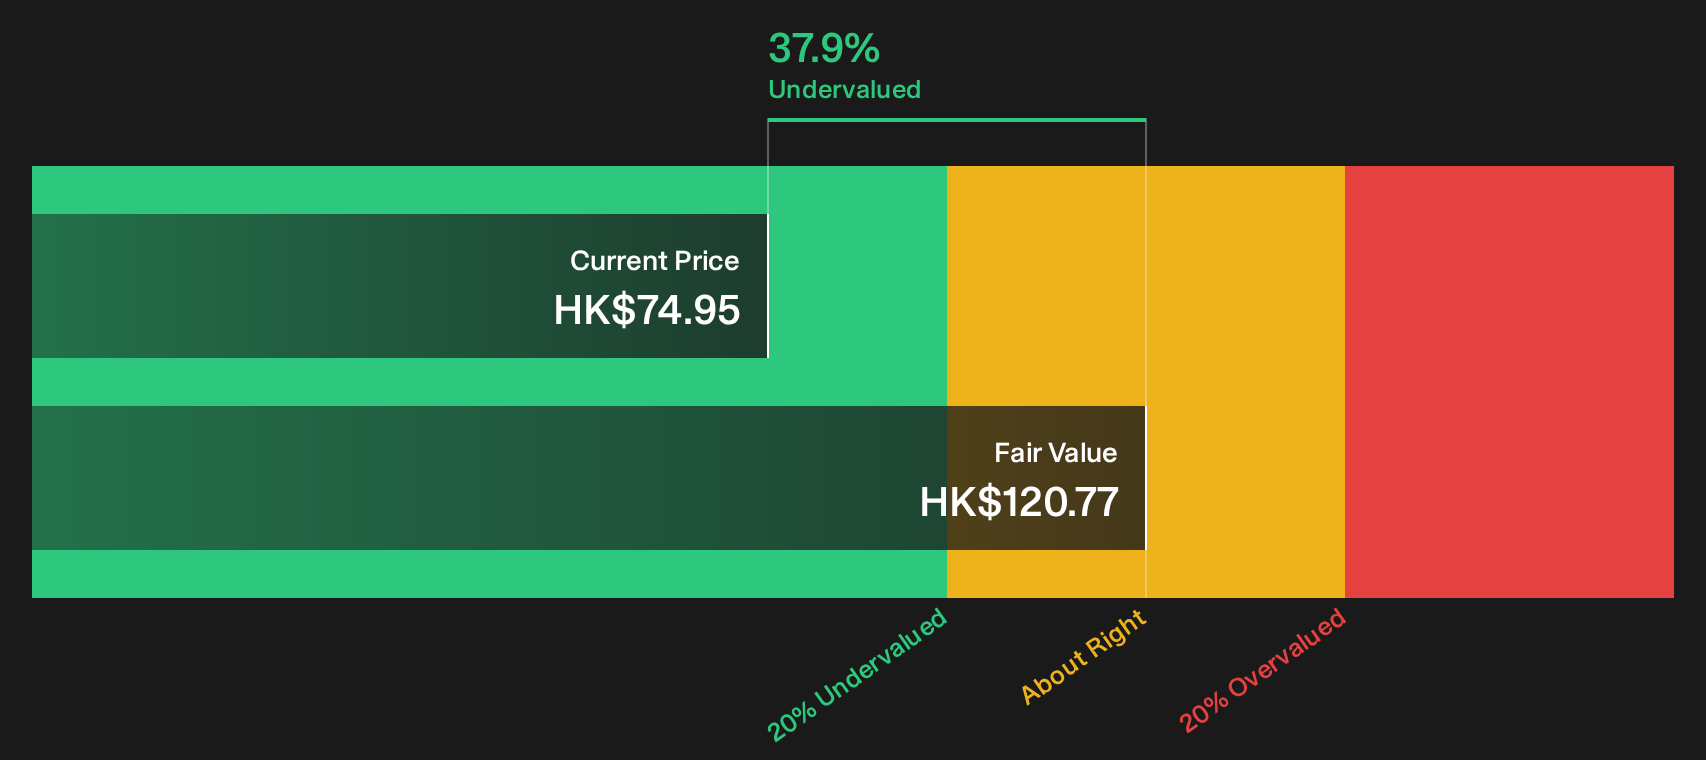
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Keymed Biosciences for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Keymed Biosciences can make the story feel complicated. This is exactly why you may want to move early and test the numbers yourself. To weigh that balance of concerns and optimism in context, start with our breakdown of 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Keymed Biosciences?
Consider looking beyond a single biotech story. A broader watchlist could highlight fresh setups and potentially more balanced risk reward trade offs across your portfolio.
- Search for quality at a discount by scanning our 192 high quality undervalued stocks that filters for companies combining solid fundamentals with prices that lag their underlying strength.
- Manage your downside by reviewing a 103 resilient stocks with low risk scores focused on businesses with resilient balance sheets and lower risk scores that can help steady overall returns.
- Identify potential early movers by checking a 20 elite penny stocks with strong financials that highlights smaller companies with financial profiles that may be stronger than many investors expect.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com