
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Tide Refresh Change P&G Stock Narrative
- Procter & Gamble recently highlighted early traction in its Fabric & Home Care segment, pointing to upgraded Tide liquid detergent and the Tide evo unit-dose format as key product launches amid ongoing pressure in Europe and softness in Home Care.
- The focus on new fabric care formats indicates that Procter & Gamble is putting greater emphasis on product development to support category momentum, even as certain regions and subsegments remain challenging.
- We will now look at how Procter & Gamble's investment narrative could be shaped by Fabric & Home Care developments related to Tide evo.
Procter & Gamble Investment Narrative Recap
To own Procter & Gamble, you need to believe in steady global demand for everyday brands, plus the company’s ability to refresh mature categories while managing cost and currency pressures. The near term story still leans on new products in Fabric & Home Care and Health Care to keep volume and pricing healthy in markets that have seen patchy consumption.
The biggest near term swing factor is how quickly category consumption stabilises in the U.S., Europe and Greater China, given prior volatility. Execution missteps or weaker demand in those regions, combined with tariffs and commodity costs, remain the key operational risk, and the latest product updates do not materially change that balance.
The Oral-B iO launch is the clearest recent proof point for how Procter & Gamble is leaning on higher tech products to reinforce its Health Care portfolio. The brush’s clinically supported performance claims, pressure sensing and app integration give the oral care franchise a more premium, feature rich tier that can support pricing and mix if consumers adopt it.
For you as an investor, the relevance is twofold. Strong adoption of Oral-B iO would support the broader thesis that P&G’s product pipeline can offset slower category growth and cost inflation. Weak traction would raise questions about how much innovation can really counter consumer and retailer volatility, especially with tariffs, currencies and softer growth in some regions still in play.
Procter & Gamble's current analyst narrative points to forecast revenue of $95.0b and earnings of $18.2b by 2029, based on an assumed 3.1% yearly revenue growth rate and an earnings increase of about $1.9b from earnings today of $16.3b.
Uncover how Procter & Gamble's fair value indicates a 12% potential upside to its current price before the market closes the gap.
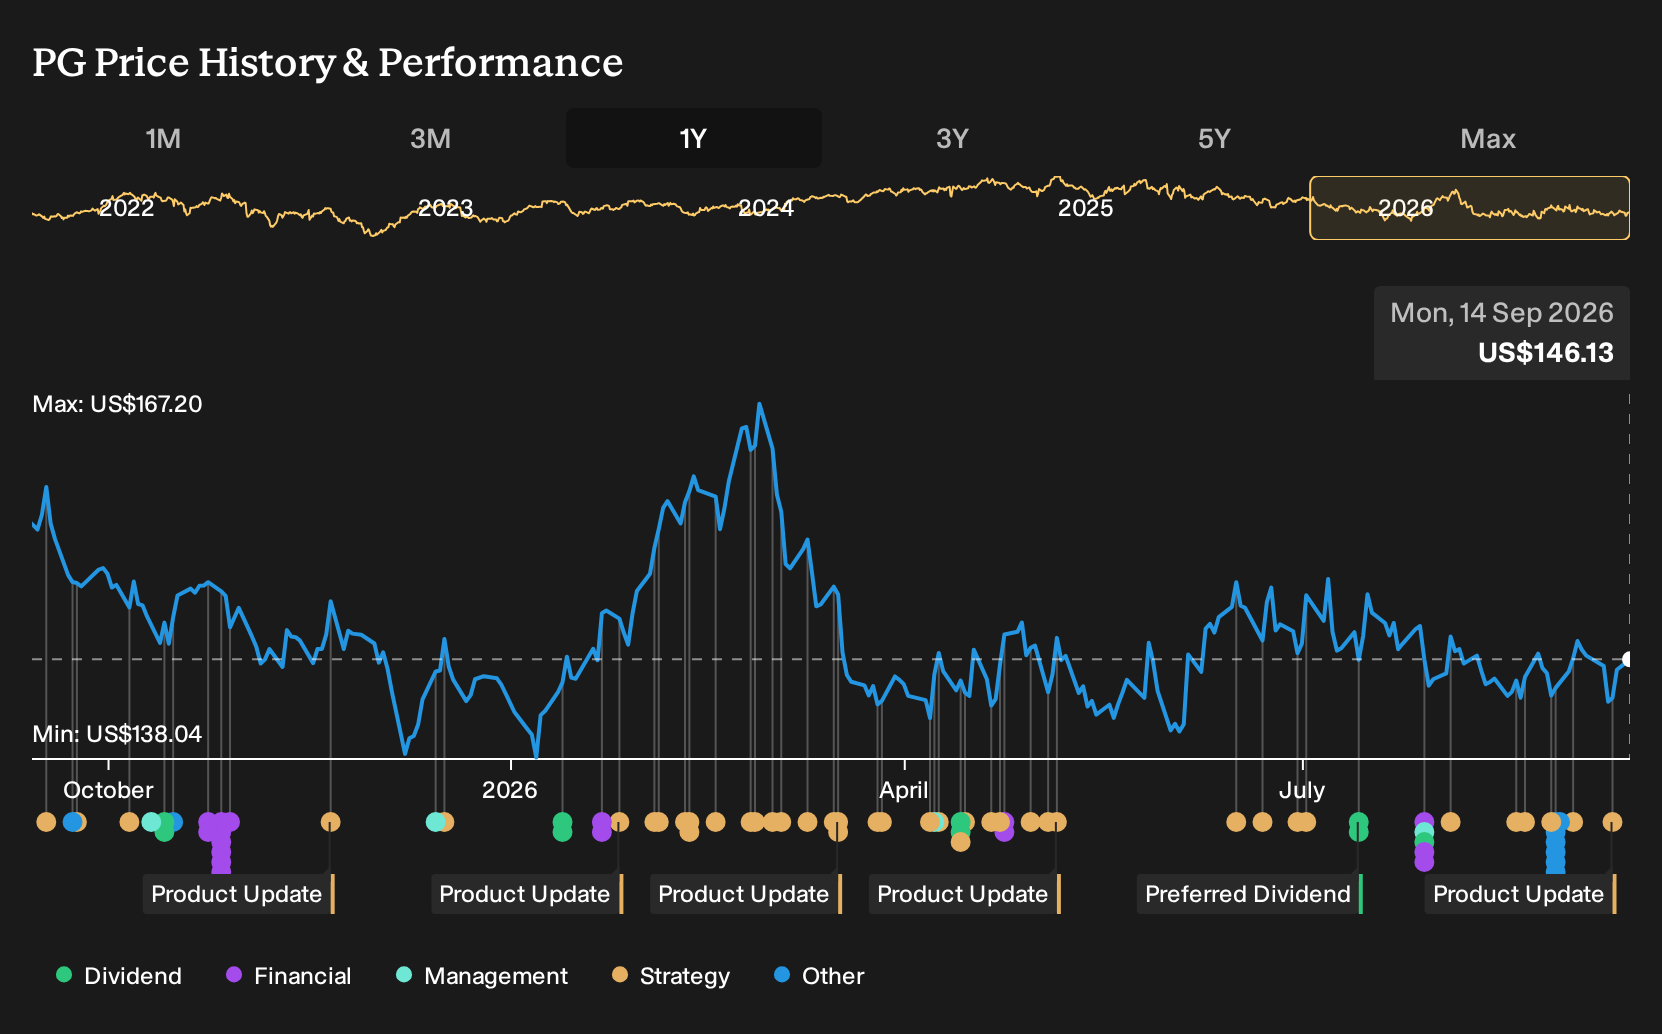
Exploring Other Perspectives
Across 17 fair value estimates from the Simply Wall St Community, Procter & Gamble’s range runs from US$107.52 to about US$196.96, so you are looking at a wide spread of opinions. Set that against fresh product launches like Oral-B iO and Febreze x Dunkin’, plus ongoing tariff and currency pressures, and you can see why views differ so sharply. Use that dispersion as a prompt to test several contrasting cases before deciding where your own thesis sits.
Explore 16 other Procter & Gamble fair value estimates, including one that suggests as much as 35% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Procter & Gamble research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Procter & Gamble. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Procter & Gamble's overall financial health at a glance.
Looking For More Procter & Gamble Sized Ideas?
If Procter & Gamble fits your preference for resilient brands with clear product stories, it can help to line it up against other candidates that share some of the same qualities. A focused screen gives you a shortlist of stocks where you can apply the same kind of narrative test you just used here.
- For investors who want quality at a reasonable entry point, scan a curated set of attractively priced companies through 35 high quality undervalued stocks.
- If income is a priority, concentrate on businesses that combine higher yields with resilience by reviewing a group of potential 6 dividend fortresses.
- If you prefer to sleep well at night, even when headlines turn noisy, focus your research on 11 resilient stocks with low risk scores that score well on fundamentals and balance sheet strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com