
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
BioLife Solutions (BLFS) Rebounds Sharply, Is It Fully Priced?
BioLife Solutions (BLFS) has drawn fresh attention after recent share price movement, with the stock last closing at $35.43. Investors are weighing that valuation against the company’s growth profile and longer term return record.
For anyone tracking momentum, BioLife Solutions has seen a strong 90 day share price return of 34.41% and a year to date share price return of 48.30%. Longer term, total shareholder return over three years sits at 178.32%, compared with a 24.95% decline over five years, which points to a recovery story that has gained traction more recently.
Scan beyond BioLife Solutions and identify other breakout candidates with a similar momentum profile by checking our curated list of 35 high quality undervalued stocks.
For BioLife Solutions, that sharp rebound sits at the crossroads of improving business metrics and a change in market mood. Does the current share price still line up with the underlying cash flows and assets?
Price-to-Earnings of 35.2x: Is it justified?
On the latest figures, BioLife Solutions trades on a P/E of 35.2x, which puts a clear valuation hurdle in front of that $35.43 share price when set against what the business is expected to earn.
The P/E ratio compares what investors pay today with the earnings generated per share. For a cell and gene therapy tools supplier like BioLife Solutions, this metric often reflects how much the market is willing to pay for the current profitability of consumables, devices, and services that support a specialised area of bioproduction.
Analysts see earnings growing by 6.1% per year, while revenue is forecast to advance by 18.1% per year, faster than the broader US market but below the 20% threshold often associated with rapid expansion. That growth profile, combined with a return on equity of 11.7%, suggests the current earnings stream is being priced at a premium level that could be hard to support if profitability or cash generation slows. The SWS fair P/E estimate of 15.1x is far lower than the present 35.2x, which some may view as a strong signal that the market multiple could move closer to that lower level if sentiment cools.
Explore the SWS fair ratio for BioLife Solutions.
Result: Price-to-Earnings of 35.2x (OVERVALUED)
Still, BioLife Solutions depends on a relatively narrow cell and gene therapy customer base, and any cooling in sentiment toward high multiple stocks could pressure that valuation.
Find out about the key risks to this BioLife Solutions narrative.
Another View on BioLife Solutions’ Value
There is a twist when switching from the headline P/E to the SWS DCF model. On that framework, BioLife Solutions at $35.43 sits about 6.1% below an estimated future cash flow value of $37.72, which frames the stock as slightly undervalued rather than stretched. Which lens do you trust more when cash flow and earnings point in different directions?
Look into how the SWS DCF model arrives at its fair value.
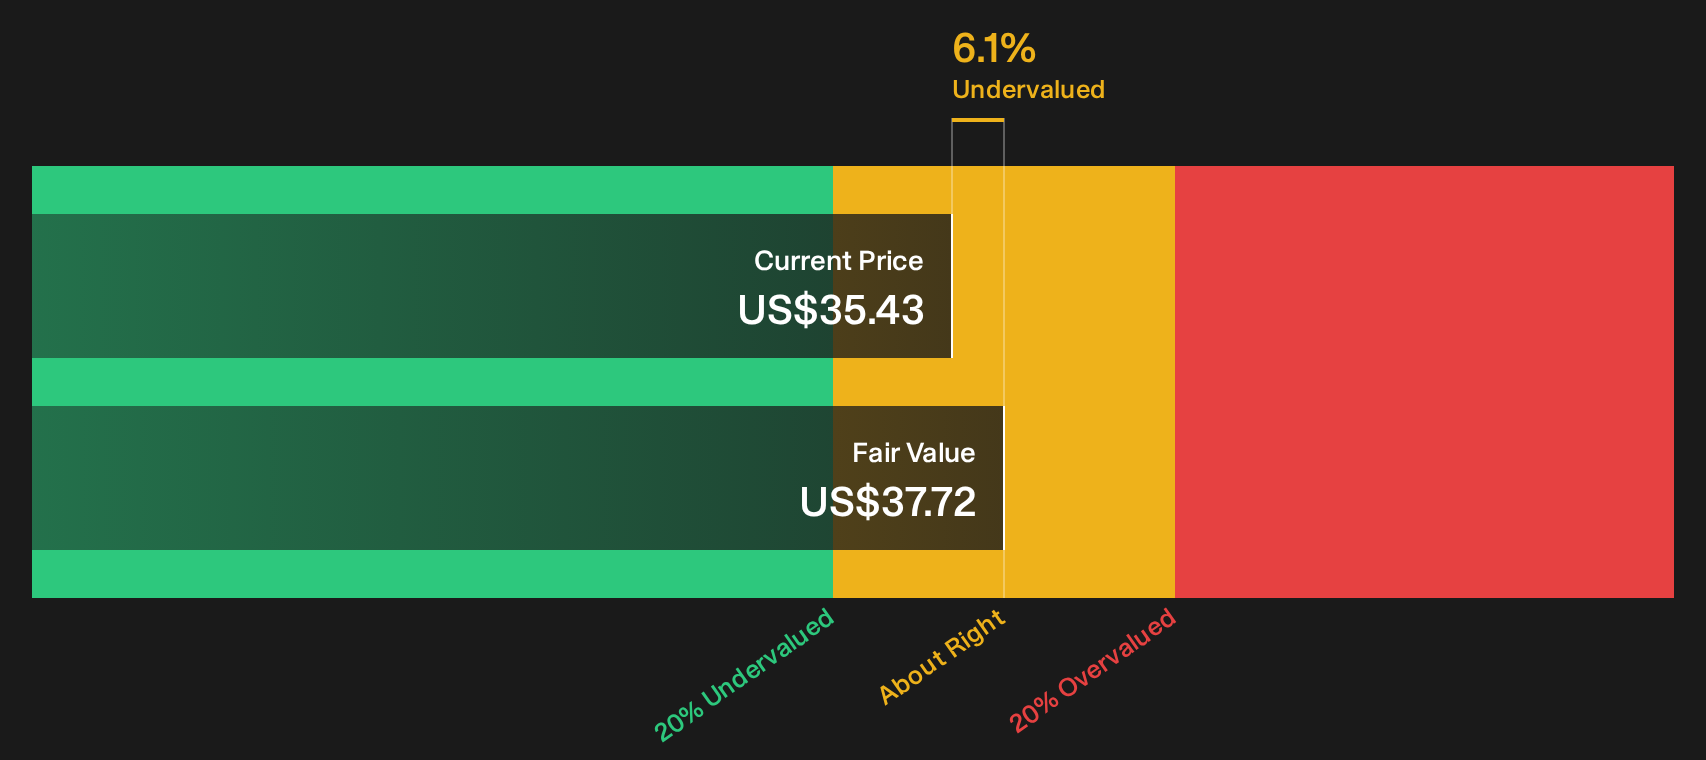
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out BioLife Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around BioLife Solutions leave you curious rather than convinced, treat that as a prompt to dig into the data yourself and move quickly while sentiment is still forming. To see what is driving the optimism, review the 3 key rewards
Ready for more investment ideas beyond BioLife Solutions?
Once the BioLife Solutions story is on your radar, widen the opportunity set and line up a few fresh ideas that could complement your watchlist.
- Target resilience first and filter for companies with stronger finances by scanning our list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced potential and sort through a curated pool of stocks using the 15 high quality undiscovered gems.
- Dial down volatility and focus on stability by checking companies highlighted in the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com