
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Kansai Electric Power Company (TSE:9503) Reconnects Mihama Unit As Valuation Questions Persist
Event overview and why Kansai Electric Power Company matters now
Kansai Electric Power Company (TSE:9503) moved back into focus after confirming that Mihama Power Station Unit No. 3 is set to reconnect to the power grid on 15 September 2026.
The reactor had been manually shut down in May following confirmed steam leakage in the high pressure turbine, with a refuel outage and maintenance program running since mid June to address the issue and complete safety measures.
Short term, Kansai Electric Power Company has given back 1.85% on a 1 day share price basis. However, the 30 day share price return of 22.57% and 90 day gain of 25.82% point to firm positive momentum that contrasts with a longer run 1 year total shareholder return of 32.78% and a very large 5 year total shareholder return of 201.47%.
News that Mihama Unit No. 3 is on track to reconnect appears to sit against this backdrop of strong recent share price gains. This suggests the market is reacting to reduced operational uncertainty and a clearer view on Kansai Electric Power Company’s nuclear capacity coming back online.
Scan for other grid and nuclear infrastructure plays showing similar momentum using our curated list of 38 power grid technology and infrastructure stocks
Kansai Electric Power Company now trades slightly above both analyst targets and an implied intrinsic value estimate after a sharp run. Is that premium simply momentum, or does it fairly reflect the remaining risks around its nuclear fleet?
Most Popular Narrative: 2% Overvalued
Kansai Electric Power Company last closed at ¥2,943, which sits slightly above the most followed narrative fair value estimate of ¥2,892 that uses a 5.12% discount rate and long term earnings assumptions.
The plan to invest a cumulative ¥15t across maintenance and growth areas by 2040, with ¥2.5t earmarked over the next 3 years, positions the group to support rising power demand and could lift group revenue and operating earnings as new assets come onstream.
Ongoing large scale maintenance on nuclear and thermal plants, while a short term drag, is intended to underpin safe and stable supply from seven nuclear reactors and other key assets.
See why 1 investors see Kansai Electric Power Company as 2% overvalued.
Result: Fair Value of ¥2,892 (OVERVALUED)
Still, that premium view on Kansai Electric Power Company depends on nuclear units returning to stable operation and on large planned asset disposals actually delivering the expected cash.
Find out about the key risks to this Kansai Electric Power Company narrative.
Another view on Kansai Electric Power Company’s valuation
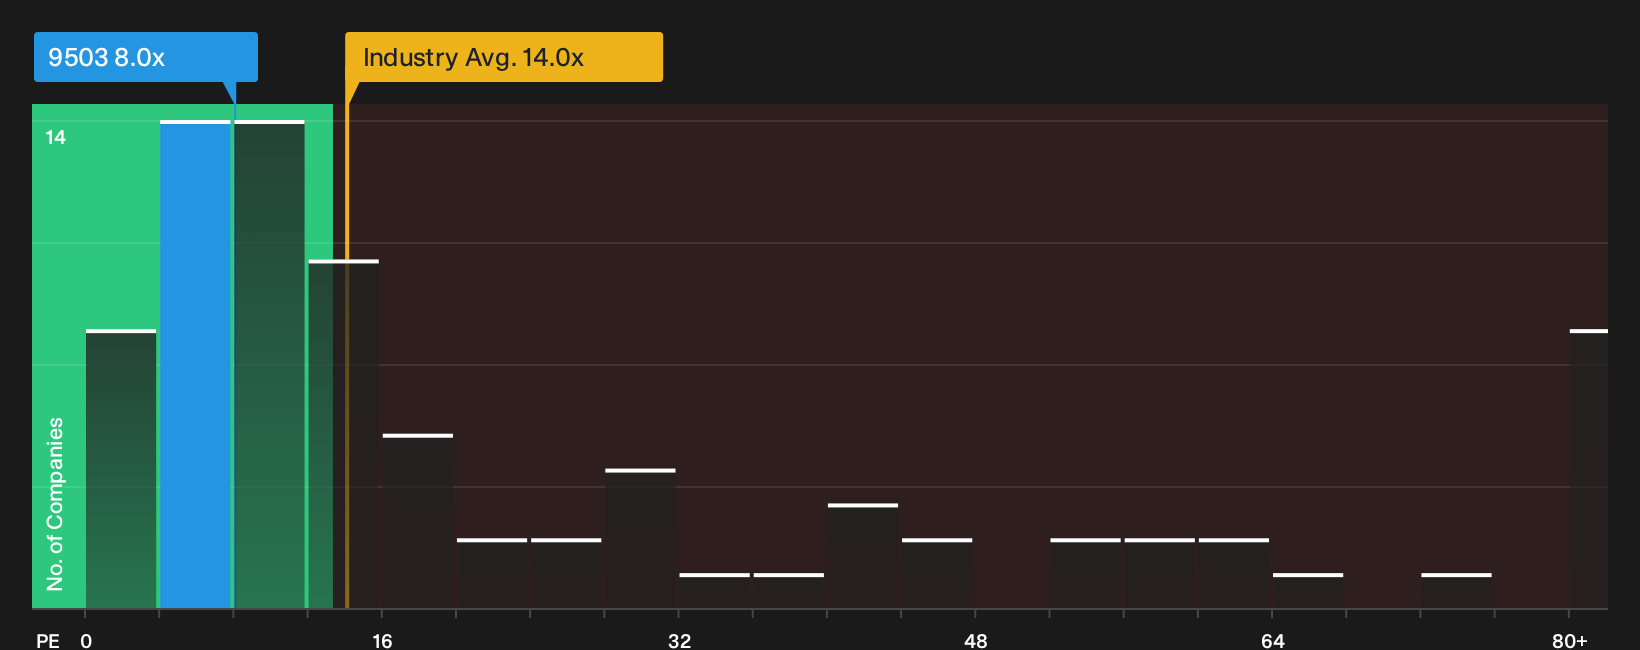
The first fair value estimate paints Kansai Electric Power Company as about 2% overvalued at ¥2,943 versus ¥2,892. Yet the market is also paying roughly 8x P/E for Kansai Electric Power Company compared with a fair ratio of 11x and an Asian electric utilities average of 13.8x. That mix of discount to both peers and fair ratio, but premium to analyst target, leaves a simple question for investors: Which signal deserves more weight when thinking about valuation risk?
To see how the current pricing stacks up against these earnings multiples and what that could mean if the market leans closer to the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Kansai Electric Power Company is mixed, with clear concerns and clear optimism pulling in opposite directions as new information lands. If you want to move fast and reach your own take based on the full picture of risks and potential upside, start by weighing the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Kansai Electric Power Company?
If Kansai Electric Power Company has sharpened your focus on where capital can work harder, do not stop here. Fresh ideas often emerge where you least expect.
- Target dependable cash generators by reviewing our 18 dividend fortresses that can help anchor your portfolio with income focused opportunities.
- Hunt for quality at a discount through the 74 high quality undiscovered gems before the broader market starts paying close attention.
- Prioritise resilience in choppy markets and filter for 12 resilient stocks with low risk scores that may help smooth portfolio swings over time.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com