
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Swedish Orphan Biovitrum (OM:SOBI) After Fast Track Win Looks Closer To Fair Value
Fast Track status for pacritinib puts rare disease focus in view
Sobi North America has received FDA Fast Track designation for pacritinib in VEXAS syndrome, drawing attention to Swedish Orphan Biovitrum (OM:SOBI) and its rare disease pipeline as investors reassess the stock’s risk reward profile.
Investors have already been paying attention to Swedish Orphan Biovitrum, with the share price at SEK448.2 and a year-to-date share price return of 35.65%. The 1-year total shareholder return of 64.18% and 3-year total shareholder return of 103.36% point to momentum that this new Fast Track decision could be reinforcing as the market reassesses both opportunity and risk around its rare disease portfolio.
Scan other rare disease and specialty pharma opportunities showing similar clinical momentum with our hand picked 618 high quality undiscovered gems that sit off most investors radar today.
Swedish Orphan Biovitrum now has a rare disease portfolio that many investors admire and a share price that has already moved significantly based on that story. The valuation question is whether the recent enthusiasm already reflects that strength.
Most Popular Narrative: 10% Undervalued
On the most followed view of Swedish Orphan Biovitrum, a fair value of SEK498.42 sits above the last close of SEK448.2. This puts the Fast Track news into a context where the rare disease story is already baked into a higher implied worth than the current price suggests.
The analysts have a consensus price target of SEK498.42 for Swedish Orphan Biovitrum based on their expectations of its future earnings growth, profit margins and other risk factors.
Given the current share price of SEK463.0, the analyst price target of SEK498.42 is 7.1% higher. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
See why 10 investors see Swedish Orphan Biovitrum as 10% undervalued.
Result: Fair Value of SEK498.42 (UNDERVALUED)
Still, Swedish Orphan Biovitrum faces real pressure points, including reimbursement and regulatory hurdles in new markets, as well as tougher competition that could test the rare disease thesis.
Find out about the key risks to this Swedish Orphan Biovitrum narrative.
Another View on Swedish Orphan Biovitrum’s valuation
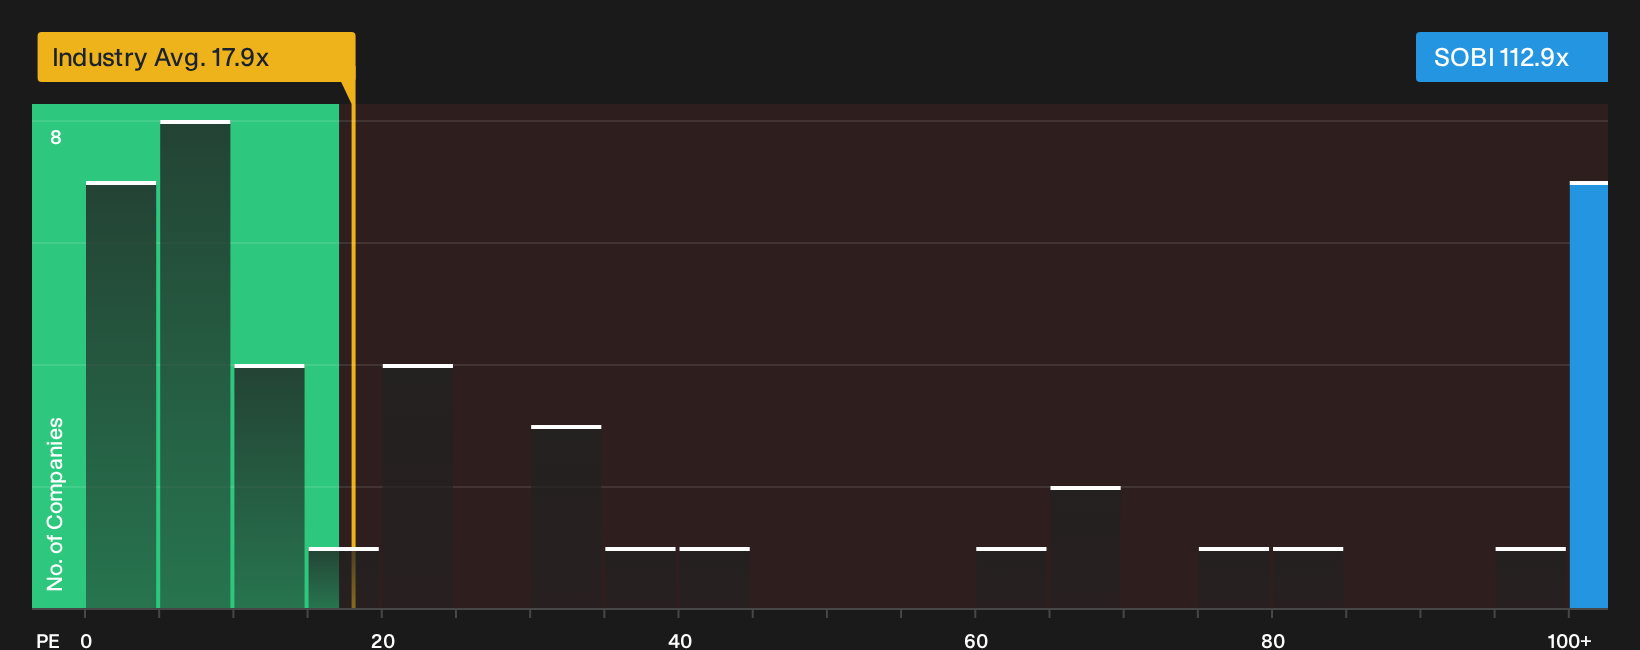
Multiples tell a very different story for Swedish Orphan Biovitrum. The stock trades on a P/E of 112.9x, which is far above the European Biotechs average of 18x, and roughly double its own fair ratio of 56.3x. That gap may indicate heightened valuation risk if sentiment cools.
For a closer look at what these comparisons imply for pricing power and downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and concern around Swedish Orphan Biovitrum feels familiar, treat it as a prompt to move fast and test the numbers yourself so your view is grounded in data rather than headlines. To see both sides of the story in one place, start with our breakdown of 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Swedish Orphan Biovitrum?
Do not stop at Swedish Orphan Biovitrum. Broaden your watchlist with fresh angles on quality, income, and resilience so you are not relying on a single story.
- Target robust fundamentals and keep risk in check by scanning our list of solid balance sheet and fundamentals (194 results), which highlights businesses built on stronger financial footing.
- Pursue income potential with staying power by reviewing our 163 dividend fortresses, which focuses on higher yielding companies with more durable payout profiles.
- Hunt for quality at a better price by using our 190 high quality undervalued stocks, which surfaces stocks where fundamentals and valuation appear out of sync.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com