
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Chewy (CHWY) Pushes AI Cost Cuts, Is The Upside Already Priced In?
Chewy (CHWY) just put a fresh AI push in front of investors, highlighting plans to cut structural costs and lift productivity, which now sits alongside recent earnings, buybacks, and a new shelf registration.
Chewy’s latest AI push lands after a choppy stretch for the stock, with the share price up 4.45% over the last day but down 36.25% on a year to date basis. The 3 year total shareholder return of 11.20% contrasts with a 42.22% decline over 1 year, pointing to long term holders still in positive territory even as shorter term momentum has faded.
Compare Chewy’s AI and cost focus with a curated group of potential breakout opportunities in our 35 high quality undervalued stocks, which is built around strong cash flows and resilient balance sheets.
After a sharp one day pop followed by a steep slide over the past year, Chewy now sits at a level where the puzzle is simple. Is the meaningful upside still ahead, or was most of the rebound already spent?
Most Popular Narrative: 31% Undervalued
The most followed narrative on Chewy pegs fair value at $31.05, compared with the latest close of $21.35. This places the AI and cost push in the middle of a much broader profitability story.
The company's increased focus on innovation, such as the Chewy+ membership and mobile app improvements, is driving new customer acquisition and higher conversion rates, enhancing both revenue growth and net sales per active customer (NSPAC).
Active customer growth has reached an inflection point, with expectations for continued growth in 2025 due to improved marketing strategies and customer acquisition channels, positively affecting top-line revenue.
See why 74 investors see Chewy as 31% undervalued.
Result: Fair Value of $31.05 (UNDERVALUED)
Still, Chewy’s heavy dependence on Autoship for more than 80% of sales, combined with modest customer growth, could quickly puncture this upside narrative if those trends weaken.
Find out about the key risks to this Chewy narrative.
Another View: What Chewy’s P/E Is Telling You
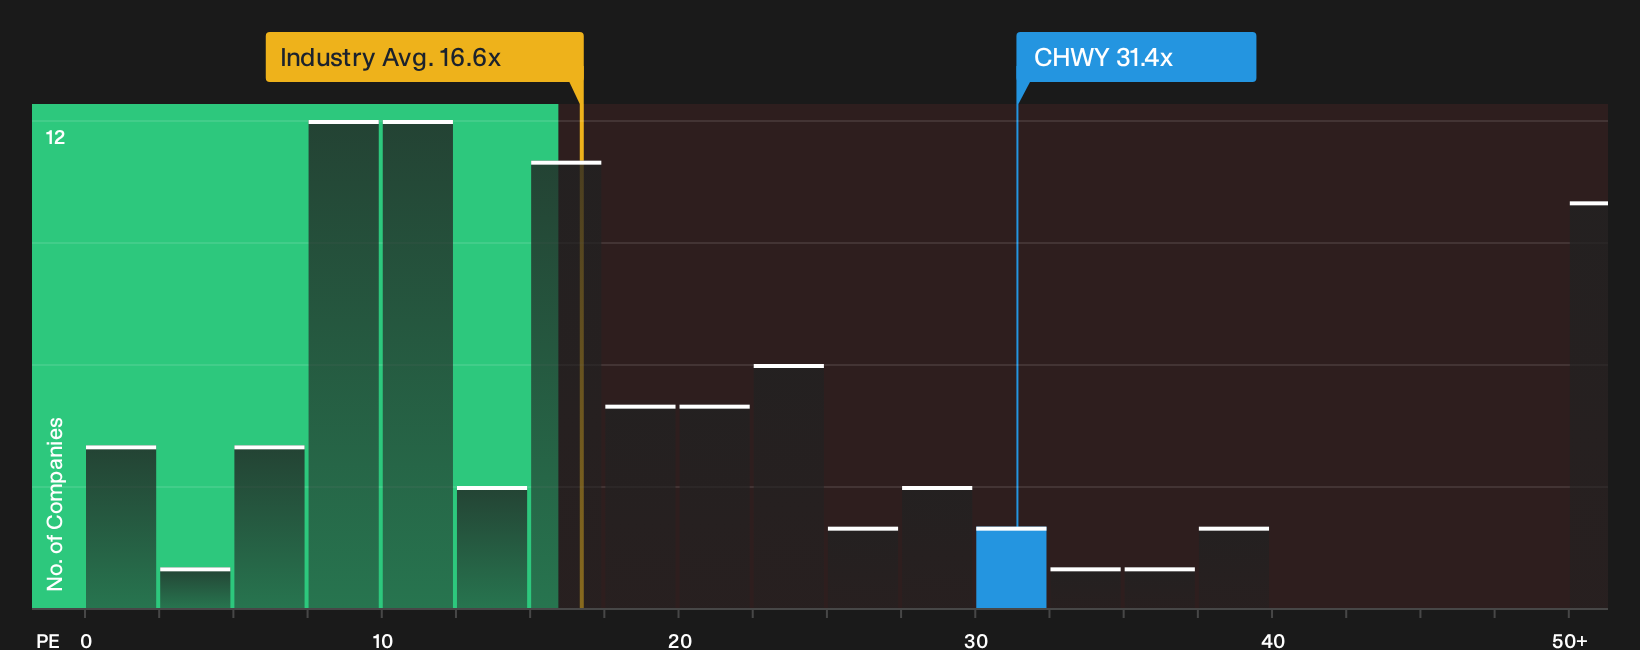
The SWS DCF model points to Chewy trading 63% below an estimate of future cash flow value. Yet on a P/E basis the picture flips. The stock trades on 31.4x earnings, compared with 18.2x for peers and 16.6x for the US Specialty Retail industry, while the fair ratio sits at 21.6x. That gap signals investors are already paying up, so it may be worth considering how much of the story is still left to price in.
For a closer look at how this earnings multiple compares with the fair ratio and peers in detail, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Chewy story feels finely balanced to you, that is the point. Move quickly through the numbers and pressure test your own thesis using the 4 key rewards.
Looking for more ideas beyond Chewy?
Chewy may be central to your watchlist today, but you do not need to stop there. Use the screeners below to pressure test fresh ideas.
- Target reliable cash generators by scanning a curated set of companies that look undervalued on quality and price using the 35 high quality undervalued stocks.
- Reduce portfolio stress by focusing on businesses with sturdy finances through the list of solid balance sheet and fundamentals (23 results).
- Spot potential outperformers early by reviewing a tightly filtered pool of under-the-radar opportunities in the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com