
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DHT Holdings (DHT) Lands Long Charter Deal On A Valuation Debate
DHT Holdings (DHT) has drawn investor attention after securing a three-year time charter for its VLCC DHT Panther at $100,000 per day with a global energy company, starting in October 2026.
Recent trading suggests investors are rewarding that visibility, with DHT Holdings’ share price up 13.47% over 30 days and 20.32% over 90 days, contributing to an 88.67% year-to-date share price return and a 5-year total shareholder return near 5x. This points to strong positive momentum rather than a short-lived reaction to one contract.
Scan other shipping and energy transport plays that show similar contract-driven momentum to DHT Holdings by reviewing the hand-picked 35 high quality undervalued stocks.
DHT Holdings now trades above the average analyst target yet screens at a sizable discount to estimated fair value. Is the recent surge a step ahead of the market, or a sign the caution is misplaced?
Most Popular Narrative: 9% Overvalued
On the most followed view, DHT Holdings screens on a fair value of $20.28 against a last close of $22.15, which leaves the stock trading at a premium that hinges on execution against an earnings and cash flow story.
Persistent growth in energy demand from emerging markets, notably in Asia, and evolving global refinery patterns are driving longer trade routes and increased ton-mile demand, supporting sustained high vessel utilization and, therefore, improved revenue visibility for DHT Holdings.
DHT's active fleet renewal selling older vessels and acquiring modern, fuel-efficient VLCCs positions the company to capture premium charter rates and reduce operating expenses, likely supporting higher net margins and more stable long-term earnings.
See why 99 investors see DHT Holdings as 9% overvalued.
Result: Fair Value of $20.28 (OVERVALUED)
Still, two pressure points could flip the DHT Holdings story quickly: weaker crude transport demand from energy transition efforts, and sector oversupply if older vessels stay in service longer.
Find out about the key risks to this DHT Holdings narrative.
Another View: Cash Flow Signals On DHT Holdings
The analyst narrative you have seen so far points to DHT Holdings trading about 9% above a $20.28 fair value, which frames the stock as overvalued on that framework. A different lens tells a very different story.
On Simply Wall St's DCF model, DHT Holdings screens on an estimated future cash flow value of $46.93 per share against a current price of $22.15. That is a very wide gap for the same company, and it raises a simple question for investors. Is the crowd underestimating the staying power of cash generation, or is the model leaning too hard on today’s strong earnings base?
Look into how the SWS DCF model arrives at its fair value.
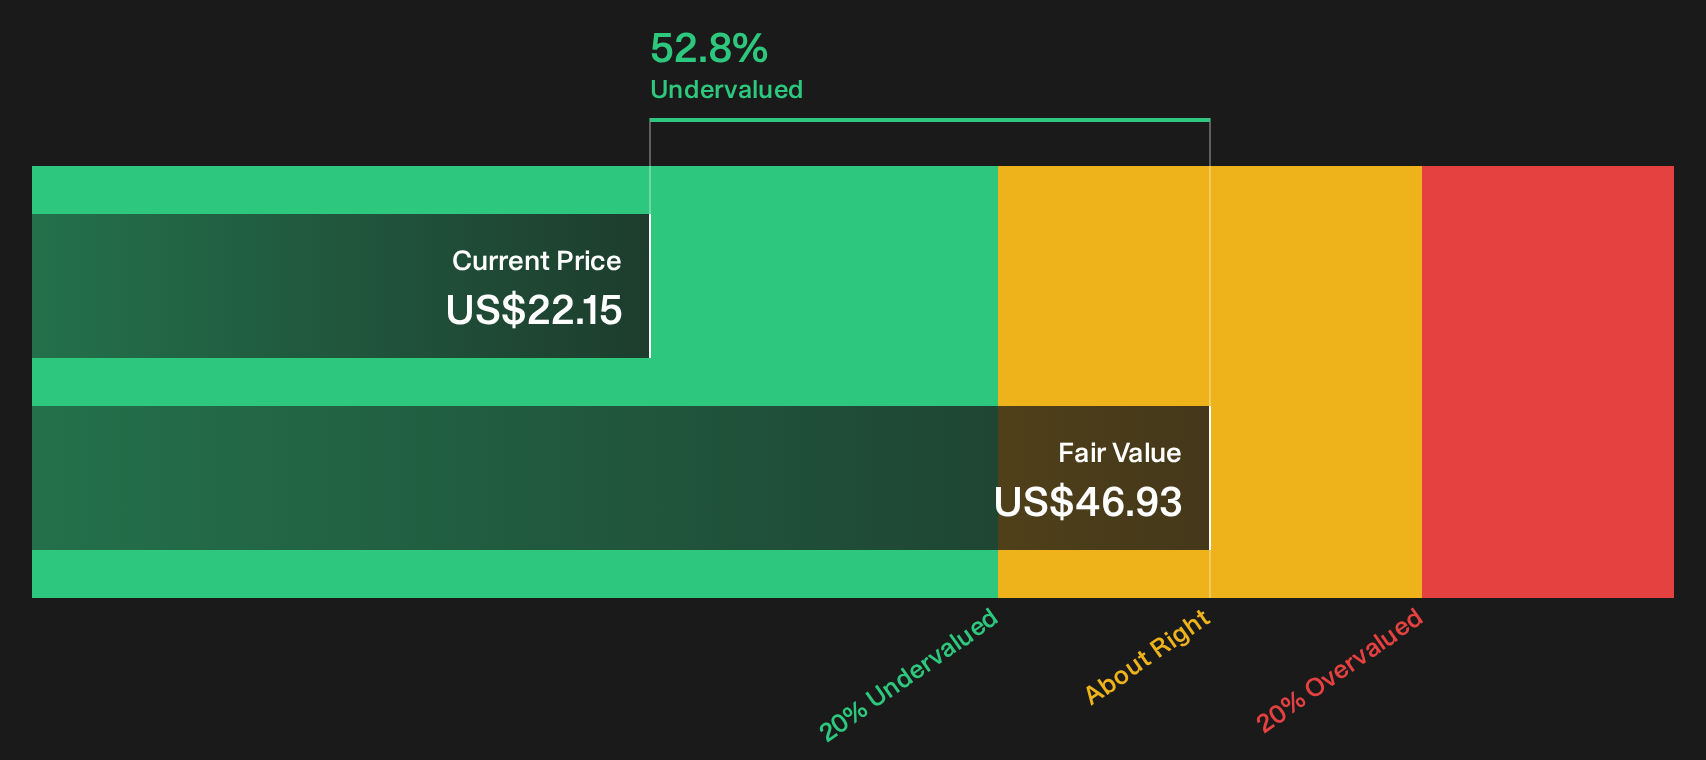
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DHT Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split views on DHT Holdings leave you undecided, move fast and inspect the data yourself so your judgement does not default to the crowd. To weigh both the upside potential and the issues investors are worried about, start with the 2 key rewards and 4 important warning signs.
Looking for more ideas beyond DHT Holdings?
If DHT Holdings has sharpened your appetite for data driven opportunities, broaden your watchlist now so you do not miss the next setup that fits your style.
- Target higher income potential by reviewing companies in the 6 dividend fortresses that aim to combine yield with balance sheet strength.
- Hunt for quality at a discount through the 15 high quality undiscovered gems that focus on solid fundamentals outside the usual crowd favorites.
- Prioritize sleep at night resilience with the 11 resilient stocks with low risk scores that concentrates on businesses with sturdier financial risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com