
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Earnings Beat Could Be A Big Moment For United Fire Group Stock (UFCS)
- United Fire Group recently reported earnings that exceeded analyst forecasts, with the latest EPS of $1.30 compared with a $0.70 consensus estimate.
- The scale of these positive earnings surprises, paired with valuation ratios that compare favorably with peers, highlights a business delivering results while still priced as a value stock.
- Next, we consider how United Fire Group's earnings surprise may influence the existing investment narrative around risk and value.
Scan beyond United Fire Group and line up other value plays with earnings momentum using our curated list of 35 high quality undervalued stocks.
United Fire Group Investment Narrative Recap
For you to hold United Fire Group, you need to believe the business can keep turning underwriting discipline and risk management into steady profitability, even as climate and reinsurance pressures build. The recent EPS beat and new 52 week high mainly affirm that the current playbook is working, rather than changing the story.
The key near term swing factor is whether United Fire Group can keep loss ratios and expenses in line while premium growth remains healthy. The biggest risk is that catastrophe activity, reinsurance costs, or competitive pricing erode those underwriting gains faster than the firm can adjust its book or pricing.
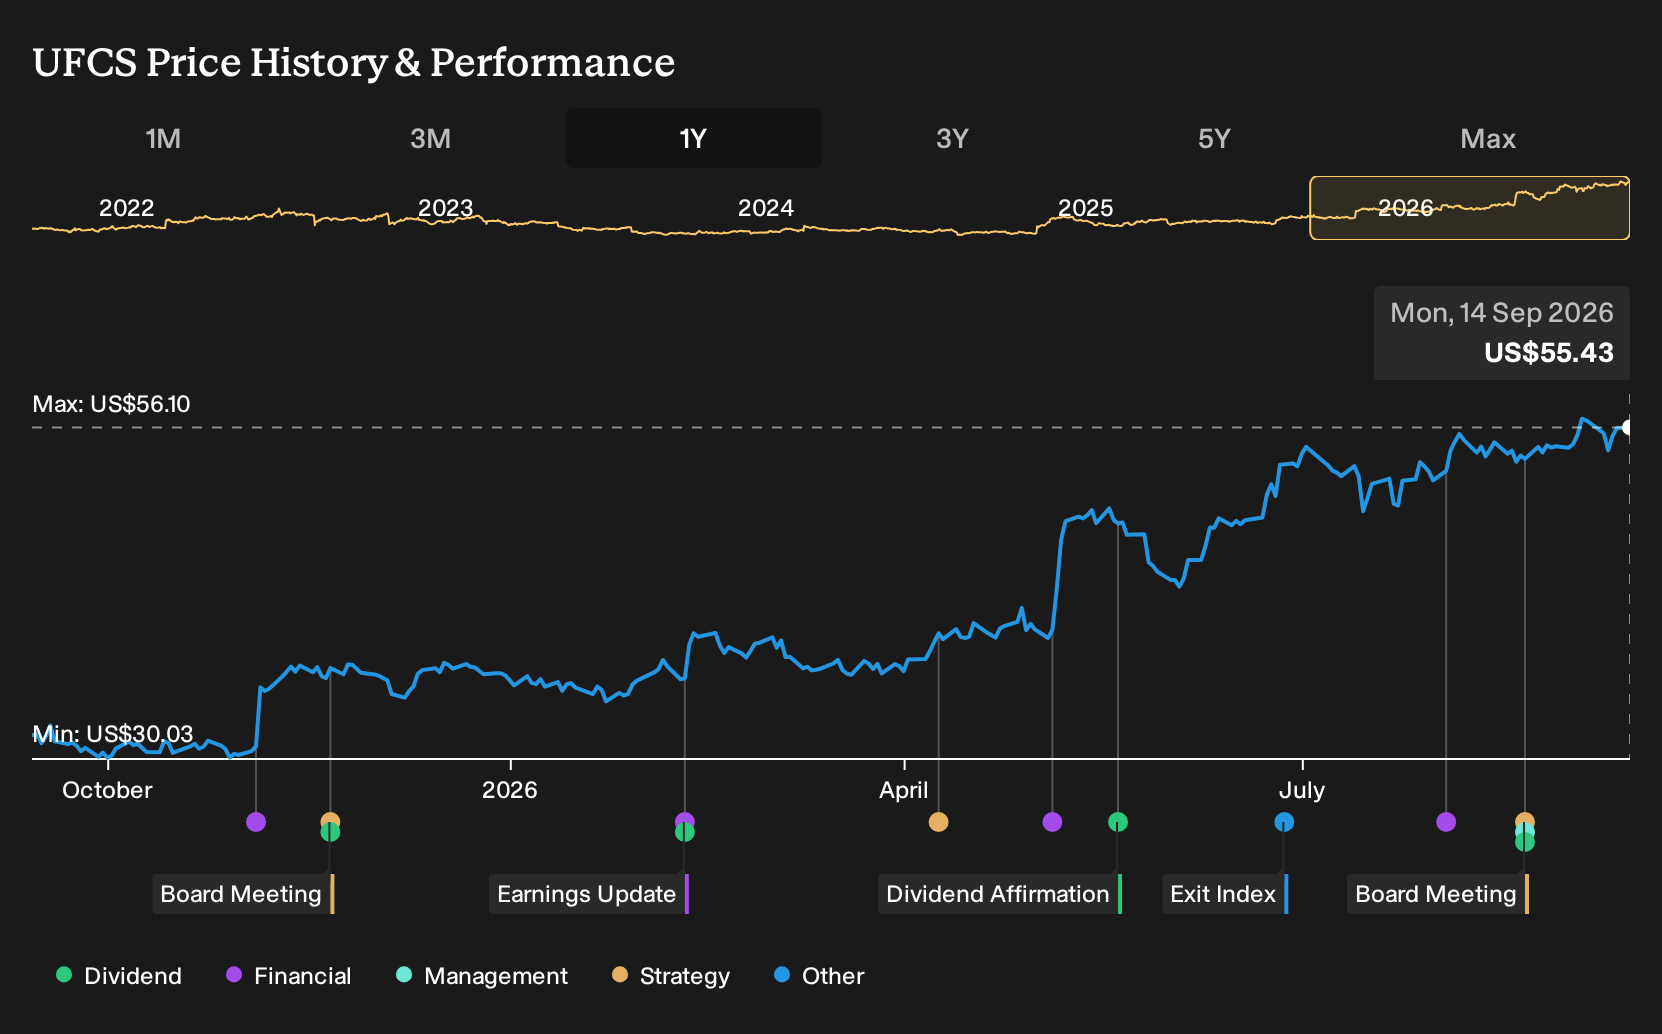
The most relevant development here is the string of earnings surprises, including the recent US$1.30 EPS result against a US$0.70 consensus estimate. That print helped push the stock to a 52 week high of US$56.74 and added weight to the idea that current underwriting and pricing efforts are feeding through to the bottom line.
For your thesis, the surprise matters because it puts more focus on execution. Strong recent earnings, revenue growth forecasts and a P/E that sits below both the US market and peer averages create a clear catalyst. Any stumble in underwriting quality or catastrophe experience would now be judged against this higher performance bar.
United Fire Group's current narrative centers on analysts expecting revenues of US$2.4b and earnings of US$93.4 million by 2029, off a base of US$141.0 million in earnings today. The forecast is built on 18.1% yearly revenue growth and an earnings decline of US$47.6 million from current levels.
Uncover how United Fire Group's fair value signals a 3% potential upside to its current price that could narrow quickly.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your United Fire Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for United Fire Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Fire Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond United Fire Group?
If the current setup around United Fire Group has sharpened your thinking on value, risk, and earnings power, it can help to compare that view with other stocks showing different mixes of quality, income, and balance sheet strength. The Simply Wall St Screener lets you line up those possibilities quickly so you can focus on building a watchlist that actually fits your approach.
- For investors hunting for under followed opportunities with robust fundamentals, start with a curated pool of 15 high quality undiscovered gems that may not yet be crowded trades.
- If capital preservation and lower volatility matter most to you, filter for companies that score well on resilience and stability using our 11 resilient stocks with low risk scores.
- Income focused investors can zero in on payout strength and consistency by screening for companies that meet your yield and stability preferences through our 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com