
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Unveiling 3 Promising Asian Stocks With Strong Potential
Amidst a backdrop of geopolitical tensions and rising oil prices, Asian markets have shown resilience, with certain sectors demonstrating robust growth potential despite broader economic uncertainties. In this dynamic environment, identifying promising stocks involves looking for companies that demonstrate strong fundamentals and the ability to adapt to shifting market conditions.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.39% | 25.87% | ★★★★★★ |
| Kyosan Electric Manufacturing | 46.17% | 7.20% | 17.51% | ★★★★★★ |
| Yahagi ConstructionLtd | 19.18% | 12.68% | 22.27% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 70.93% | 9.87% | 28.79% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
Intermestic (TSE:262A)
Simply Wall St Value Rating: ★★★★★☆
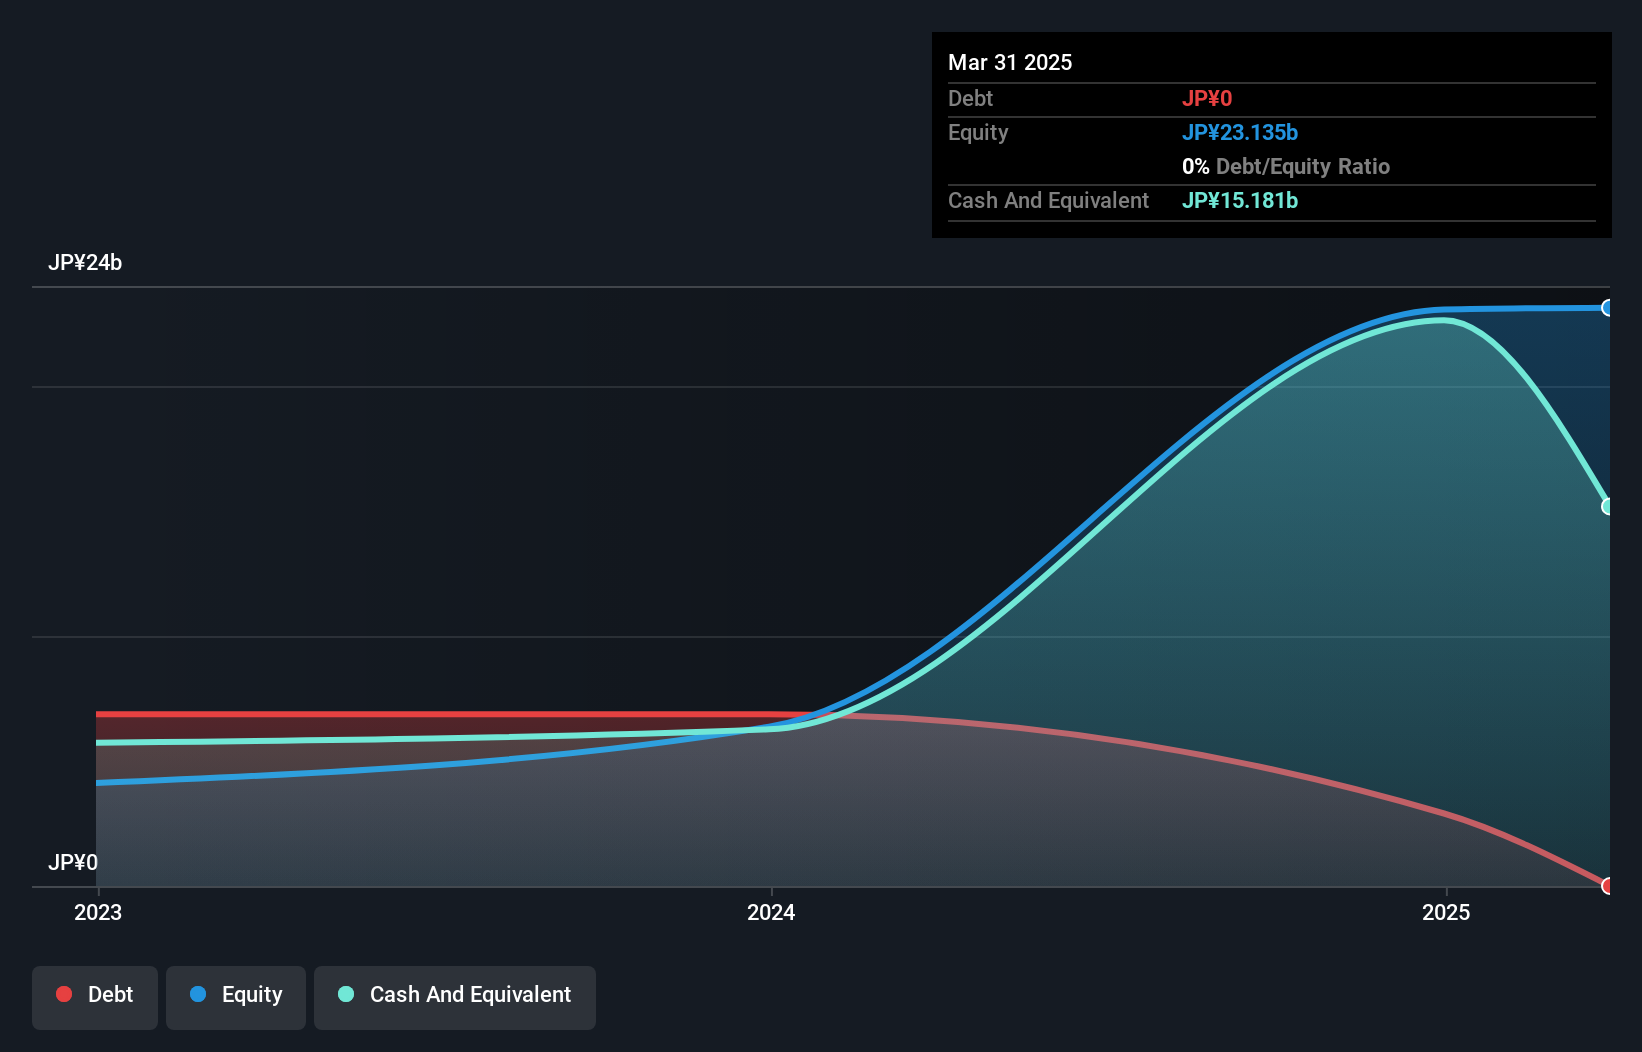
Overview: Intermestic Inc. operates in the eyewear industry, selling eyeglasses and sunglasses primarily in Japan, with a market capitalization of ¥53.64 billion.
Operations: Intermestic generates revenue primarily from its Domestic Business, amounting to ¥68.89 billion, with additional contributions from its Overseas Segment at ¥880 million. The company's financial performance is significantly driven by its domestic market activities.
Intermestic, a small cap player in the specialty retail space, has shown solid performance with earnings growing 11.7% over the past year, outpacing the industry average of 9.5%. The company's net debt to equity ratio stands at a satisfactory 16%, indicating prudent financial management. Recent sales figures reflect resilience despite challenging conditions; total store sales rose by 5% year-on-year in June 2026, with same-store sales maintaining positive growth for the 42nd consecutive month. Trading at approximately 58.1% below its estimated fair value suggests potential upside for investors seeking undervalued opportunities in Asia's market landscape.
- Click here and access our complete health analysis report to understand the dynamics of Intermestic.
Explore historical data to track Intermestic's performance over time in our Past section.
GA technologies (TSE:3491)
Simply Wall St Value Rating: ★★★★☆☆
Overview: GA technologies Co., Ltd. operates a real estate brokerage platform with a market capitalization of approximately ¥59.57 billion.
Operations: The primary revenue stream for GA technologies comes from the RENOSY Marketplace, generating ¥272.94 billion, followed by ITANDI at ¥6.89 billion.
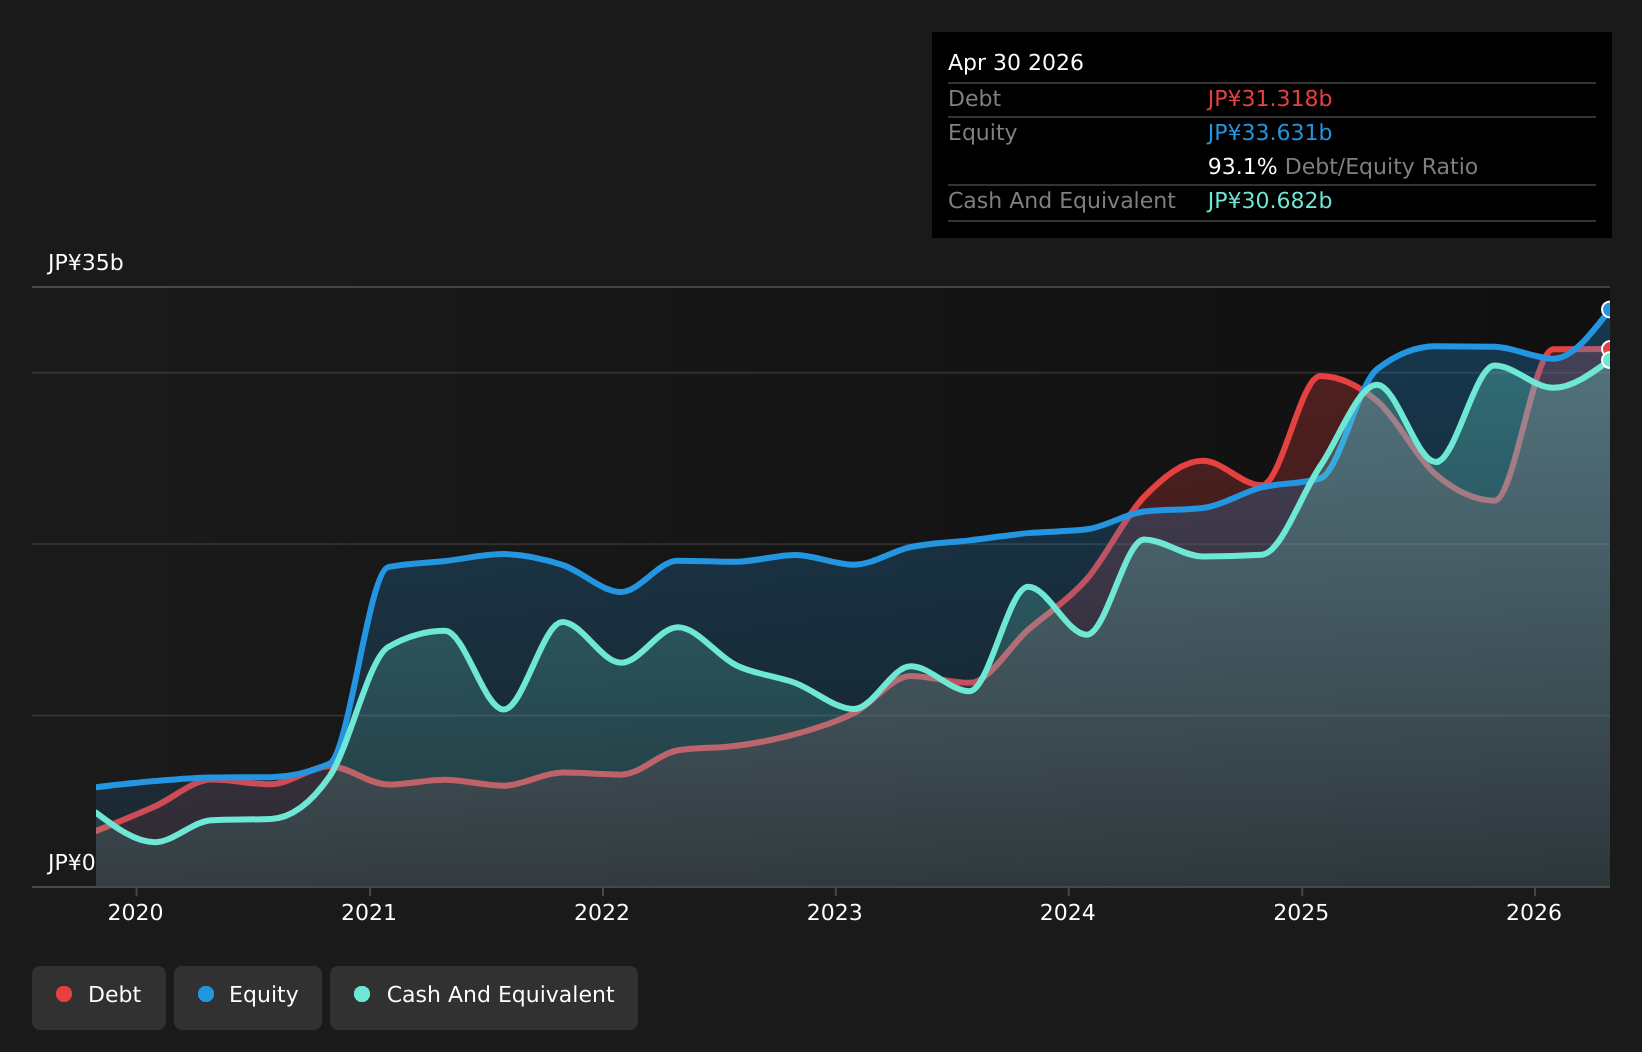
GA Technologies, a player in the Interactive Media and Services industry, has seen its earnings grow by 21.5% over the past year, outpacing the industry's 18.2%. The company is trading at an attractive value, being 74.9% below its estimated fair value, which might catch investors' eyes looking for opportunities in under-the-radar stocks. Despite a rise in debt to equity from 32.7% to 93.1% over five years, it maintains a satisfactory net debt to equity ratio of 1.9%, indicating prudent financial management amid growth ambitions with well-covered interest payments at an EBIT coverage of 8.8x.
- Get an in-depth perspective on GA technologies' performance by reading our health report here.
Examine GA technologies' past performance report to understand how it has performed in the past.
Maruzen Showa Unyu (TSE:9068)
Simply Wall St Value Rating: ★★★★★★
Overview: Maruzen Showa Unyu Co., Ltd. operates in the logistics sector both domestically and internationally, with a market cap of ¥139.19 billion.
Operations: The logistics business is the primary revenue stream, generating ¥130.92 billion, while the on-site work and mechanical cargo handling business contributes ¥16.97 billion.
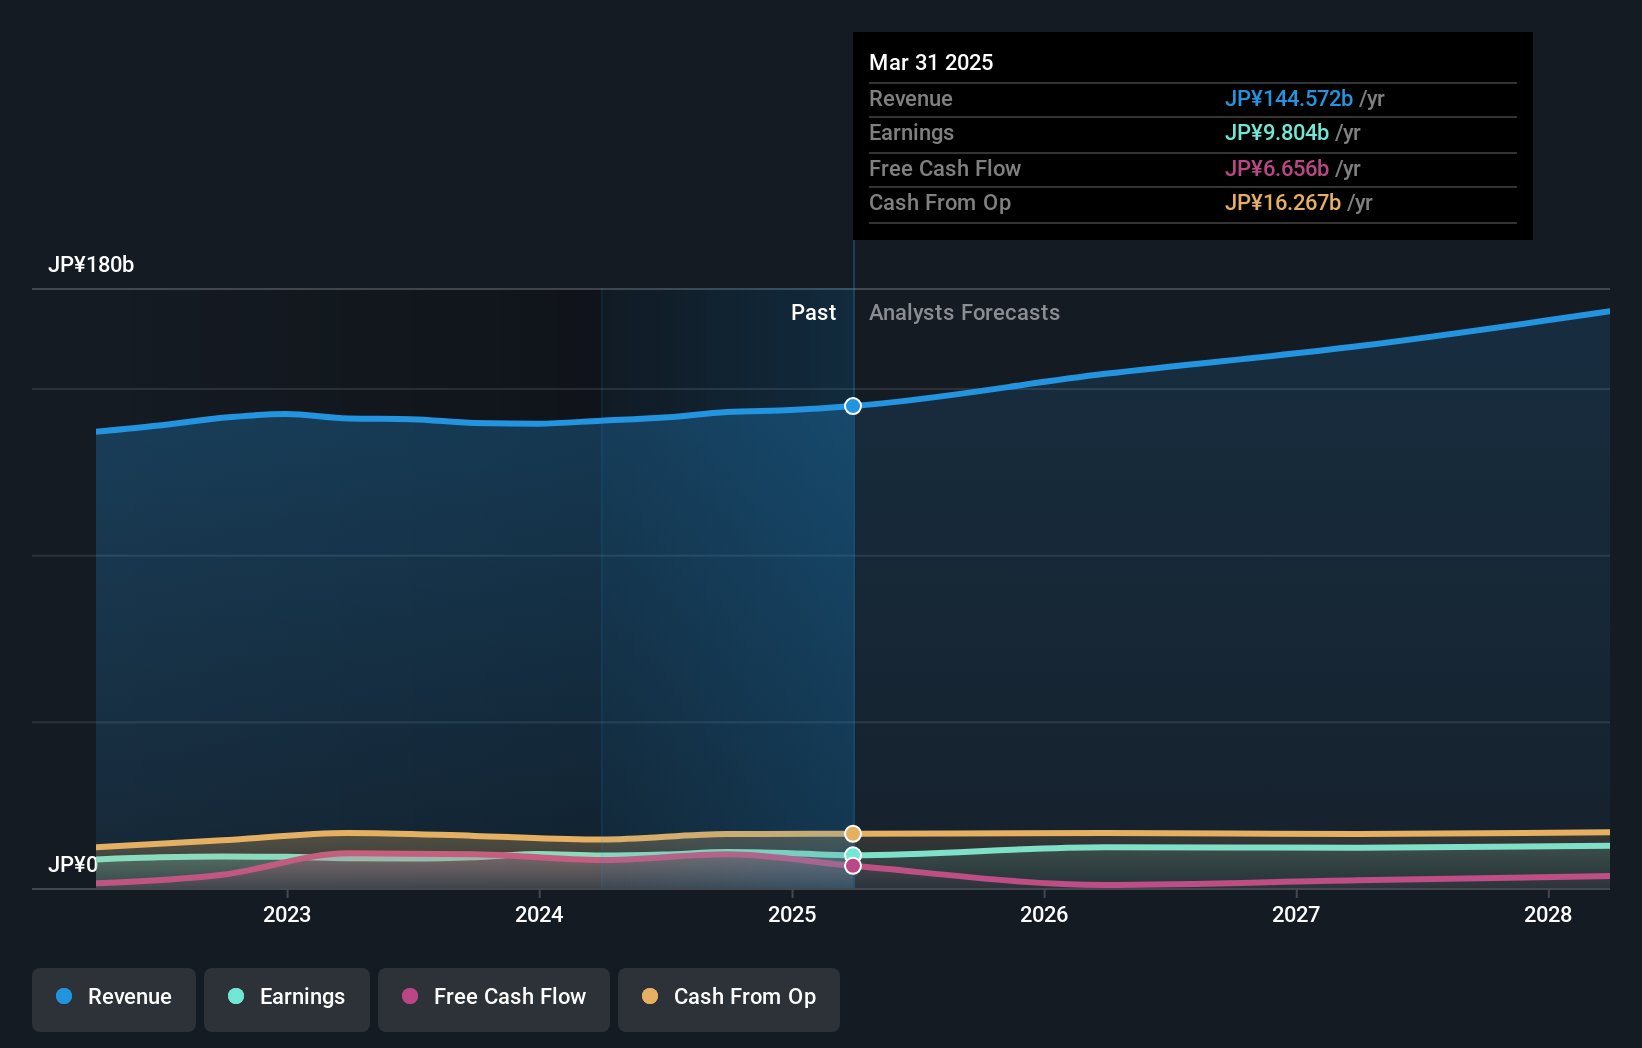
Maruzen Showa Unyu, a notable player in the transportation sector, has shown robust financial health with earnings growing by 24% over the past year, outpacing the industry average of 10.6%. The company trades at a value 23.6% below its estimated fair value and boasts high-quality earnings. Its debt to equity ratio has improved from 28.3% to 15.6% over five years, reflecting prudent financial management. Recent corporate actions include a board-approved share split and an increased dividend forecast for fiscal year ending March 2027, with dividends expected at ¥220 per share before the split takes effect on October 1, 2026.
- Unlock comprehensive insights into our analysis of Maruzen Showa Unyu stock in this health report.
Evaluate Maruzen Showa Unyu's historical performance by accessing our past performance report.
Next Steps
- Unlock more gems! Our Asian Undiscovered Gems With Strong Fundamentals screener has unearthed 115 more companies for you to explore.Click here to unveil our expertly curated list of 118 Asian Undiscovered Gems With Strong Fundamentals.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Discover a world of investment opportunities with Simply Wall St's free app and access unparalleled stock analysis across all markets.
Interested In Other Possibilities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com