
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
REX American Resources (REX) Stock Still Looks Cheap At Today’s Earnings Price
REX American Resources has ridden a strong multi year share price run and a string of upbeat headlines, which naturally puts a spotlight on what investors are paying for its earnings today. With that backdrop, the real puzzle for anyone looking at the stock now is how the current price lines up with the profits the business is generating.
- Over the past 5 years the stock has returned roughly 223%, which raises the stakes on whether current earnings can support the value now implied by the share price.
- Recent progress on ethanol expansion and carbon capture projects may support expectations for future profitability and cash generation, while the company’s debt free position can influence how investors frame its earnings power.
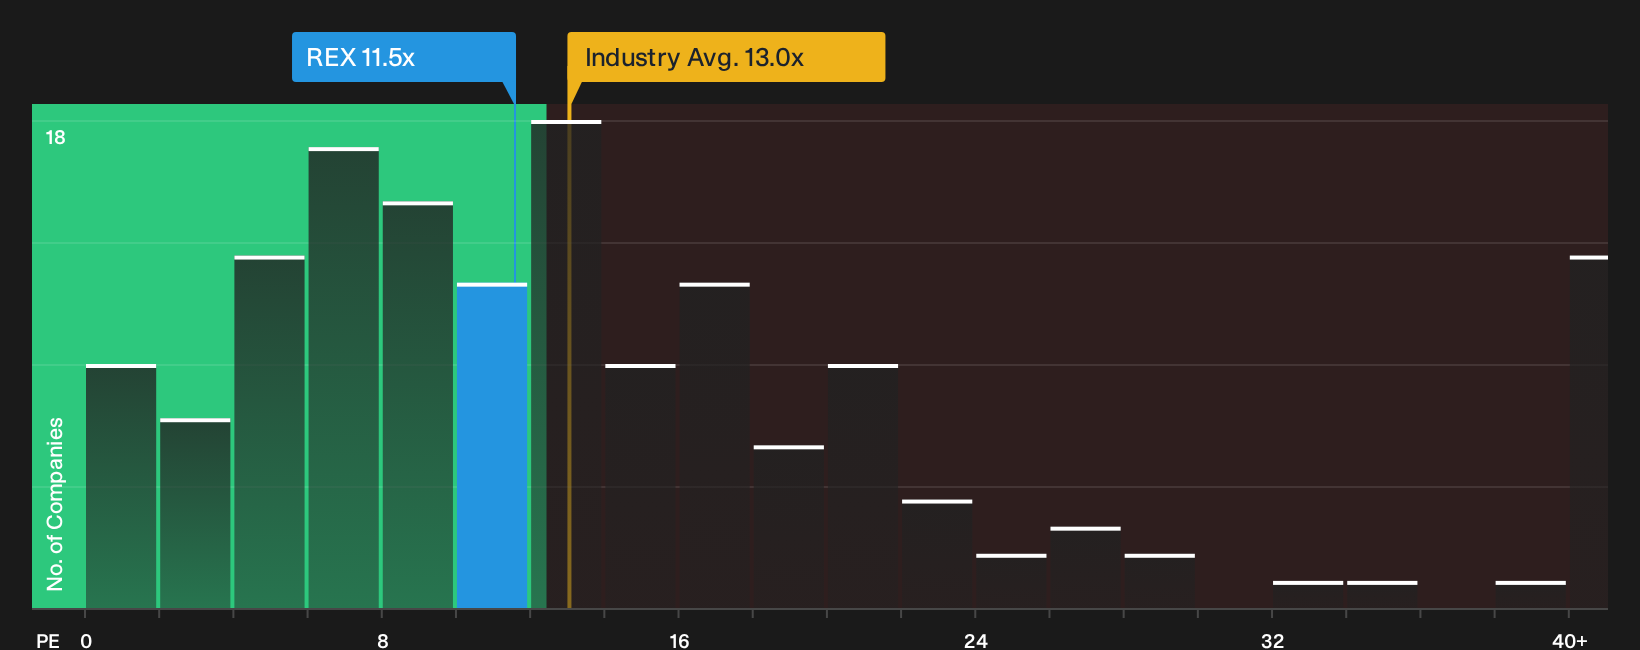
- Before you settle on a price for REX American Resources, see what its peers cost. See how REX American Resources's 11.5x P/E compares with its peers.
For investors, the debate is whether the earnings that REX American Resources generates today are sufficient to justify the current share price when judged against the industry average.
For a wider starting point alongside REX American Resources, you could also run a focused screen of 35 high quality undervalued stocks to see other ideas that pair earnings with quality fundamentals.
Is REX American Resources Still Cheap on Earnings?
The P/E ratio fits REX American Resources because the market is heavily focused on the earnings power behind its ethanol and carbon capture projects. On this lens, the stock trades on a P/E of about 11.5x, which is below the Oil and Gas industry average of roughly 13.0x and well under the wider peer group at about 26.0x.
Because record Q2 EPS has already landed in the numbers, that lower multiple suggests investors are still pricing REX American Resources at a discount to both its sector and peers rather than paying up for the recent headlines. For anyone weighing the shares, the key question is whether the current earnings profile, combined with its debt free balance sheet and project pipeline, justifies a P/E that sits below those benchmarks or points to a potential gap in how the market is valuing the business today. Explore the numbers behind REX American Resources's P/E valuation.
The REX American Resources Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the REX American Resources valuation puzzle leaves off by spelling out which paths for future earnings, margins and growth would need to play out for the stock to be worth materially more or less than today’s price on the Community page. Each scenario links its number to a concrete view on how profitability trends, expansion opportunities and key risks could evolve, giving you a reference point to revisit as fresh information arrives.
A written, number driven view on REX American Resources is useful now because it pins down what level of earnings, margins and cash generation would need to come through for the recent record net income per share, ethanol expansion plan and carbon capture project to make sense against today’s P/E. Putting those assumptions on paper gives you a reference that can be tested as future pricing, Section 45Z credits and regulatory decisions on the Illinois pipeline play out.
Share your own Narrative for REX American Resources and set out the assumptions behind your valuation.
REX American Resources is more than a snapshot of today's price
Valuation only tells you what the market is willing to pay right now, while analyst projections sketch out where they think earnings and cash generation might head over the next few years. Explore where analysts expect REX American Resources to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com