
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Turkish Bank Stocks Leveraged To Short Term Rates And Cash Demand
Markets are being pulled in several directions at once, with geopolitics, sticky supply bottlenecks and shifting central bank policy all pushing investors to rethink where they park short-term cash. When risk feels harder to price, the quiet power of money-market and cash management franchises starts to matter a lot more. This article walks through three stocks from our Global Short-Duration Cash & Money-Market Beneficiaries screener that are closely exposed to those cross currents.
The three stocks that follow are just a sample, and the full screen surfaced 16 more listed businesses with money-market and cash management angles that carry equally interesting stories. To identify, compare and analyze those extra candidates side by side, head straight into the Global Short-Duration Cash & Money-Market Beneficiaries screener.
Turkiye Garanti Bankasi (IBSE:GARAN)
Overview: Turkiye Garanti Bankasi is a large Turkish universal bank that gathers retail and corporate deposits and channels them into loans, payments, investment products and cash management services closely tied to short-duration liquidity demand.
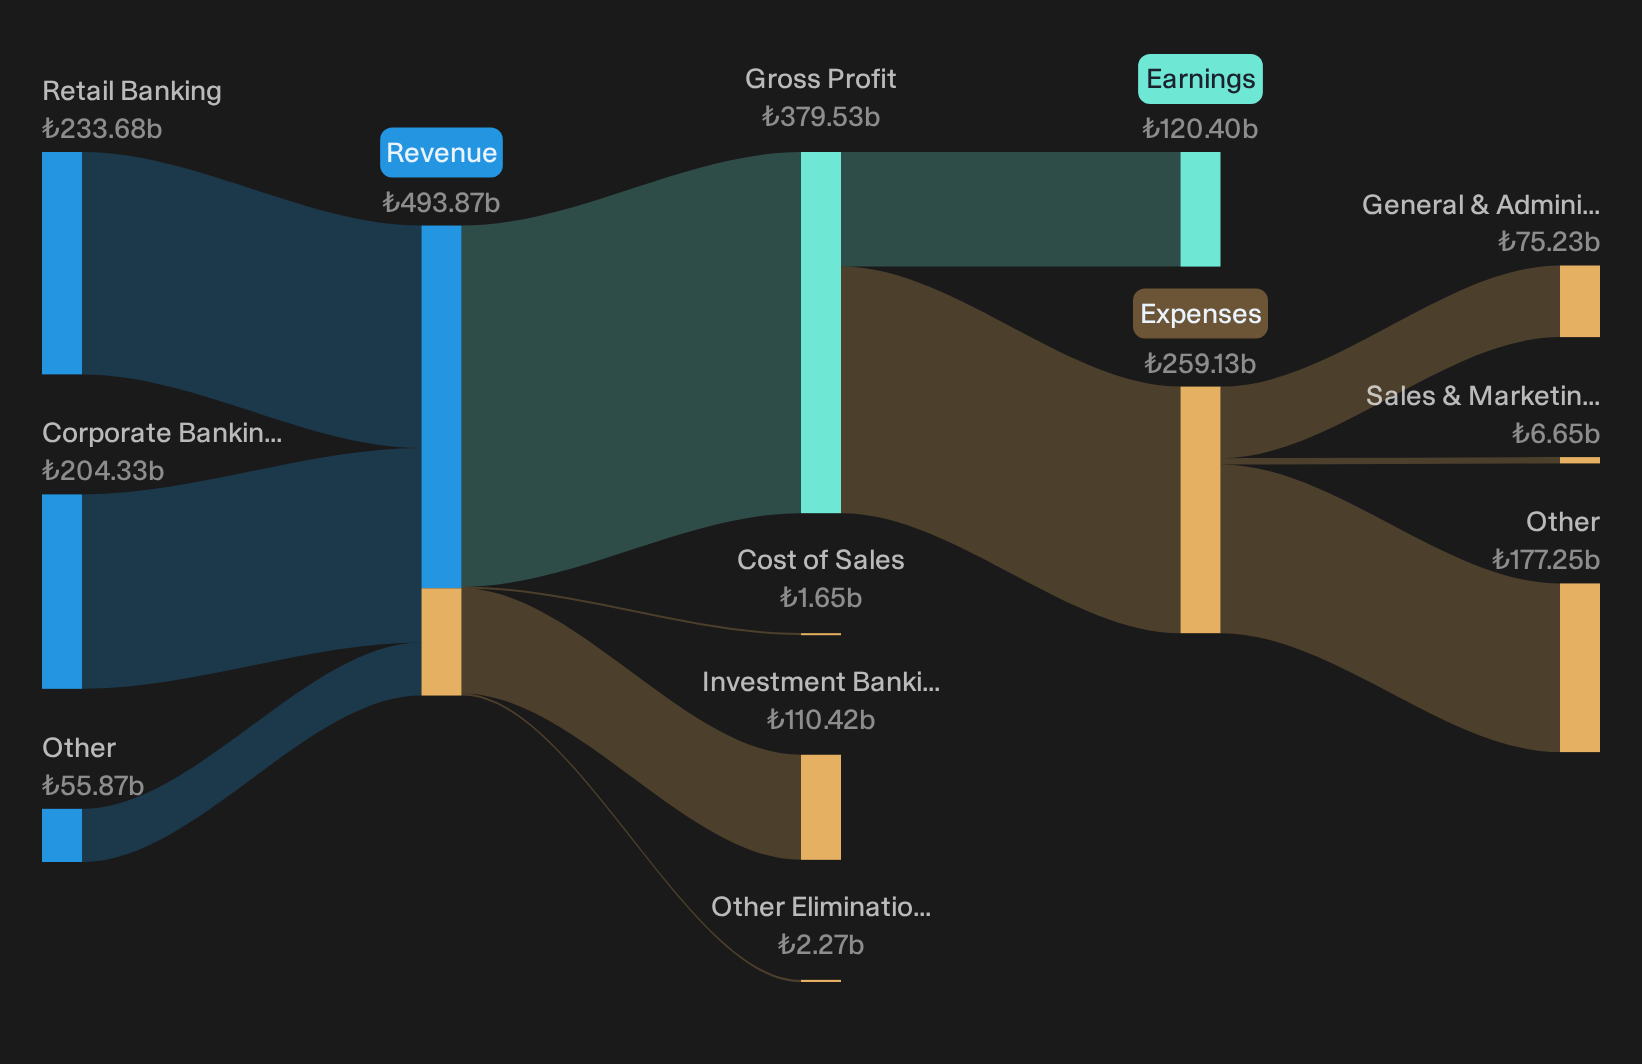
Operations: Turkiye Garanti Bankasi generates TRY 233.7b from Retail Banking, TRY 204.3b from Corporate Banking and TRY 55.9b from Other, with Investment Banking reporting a loss of TRY 110.4b.
Market Cap: TRY 562.4b
Turkiye Garanti Bankasi matters for this theme because its everyday current accounts, savings balances and cash management tools are effectively the pipes through which Turkish households and businesses respond when short-term rates shift or risk appetite cools.
"Accelerated shift to retail and SME deposits and digital banking is reducing funding costs and is described as driving sustained outperformance in net interest margins and revenue growth."
What happens if a single unseen pressure on those cheaper deposits forces Turkiye Garanti Bankasi to reprice its short-duration funding base?
That funding question is exactly what the full narrative tackles in depth. Read the full narrative for Turkiye Garanti Bankasi to see how deposit mix, pricing power and regulation really interact.
Yapi ve Kredi Bankasi (IBSE:YKBNK)
Overview: Yapi ve Kredi Bankasi is a Turkish commercial bank that gathers deposits and lends short term, while offering cash management, payment, investment and advisory services across retail, corporate and SME clients in Turkey and abroad.
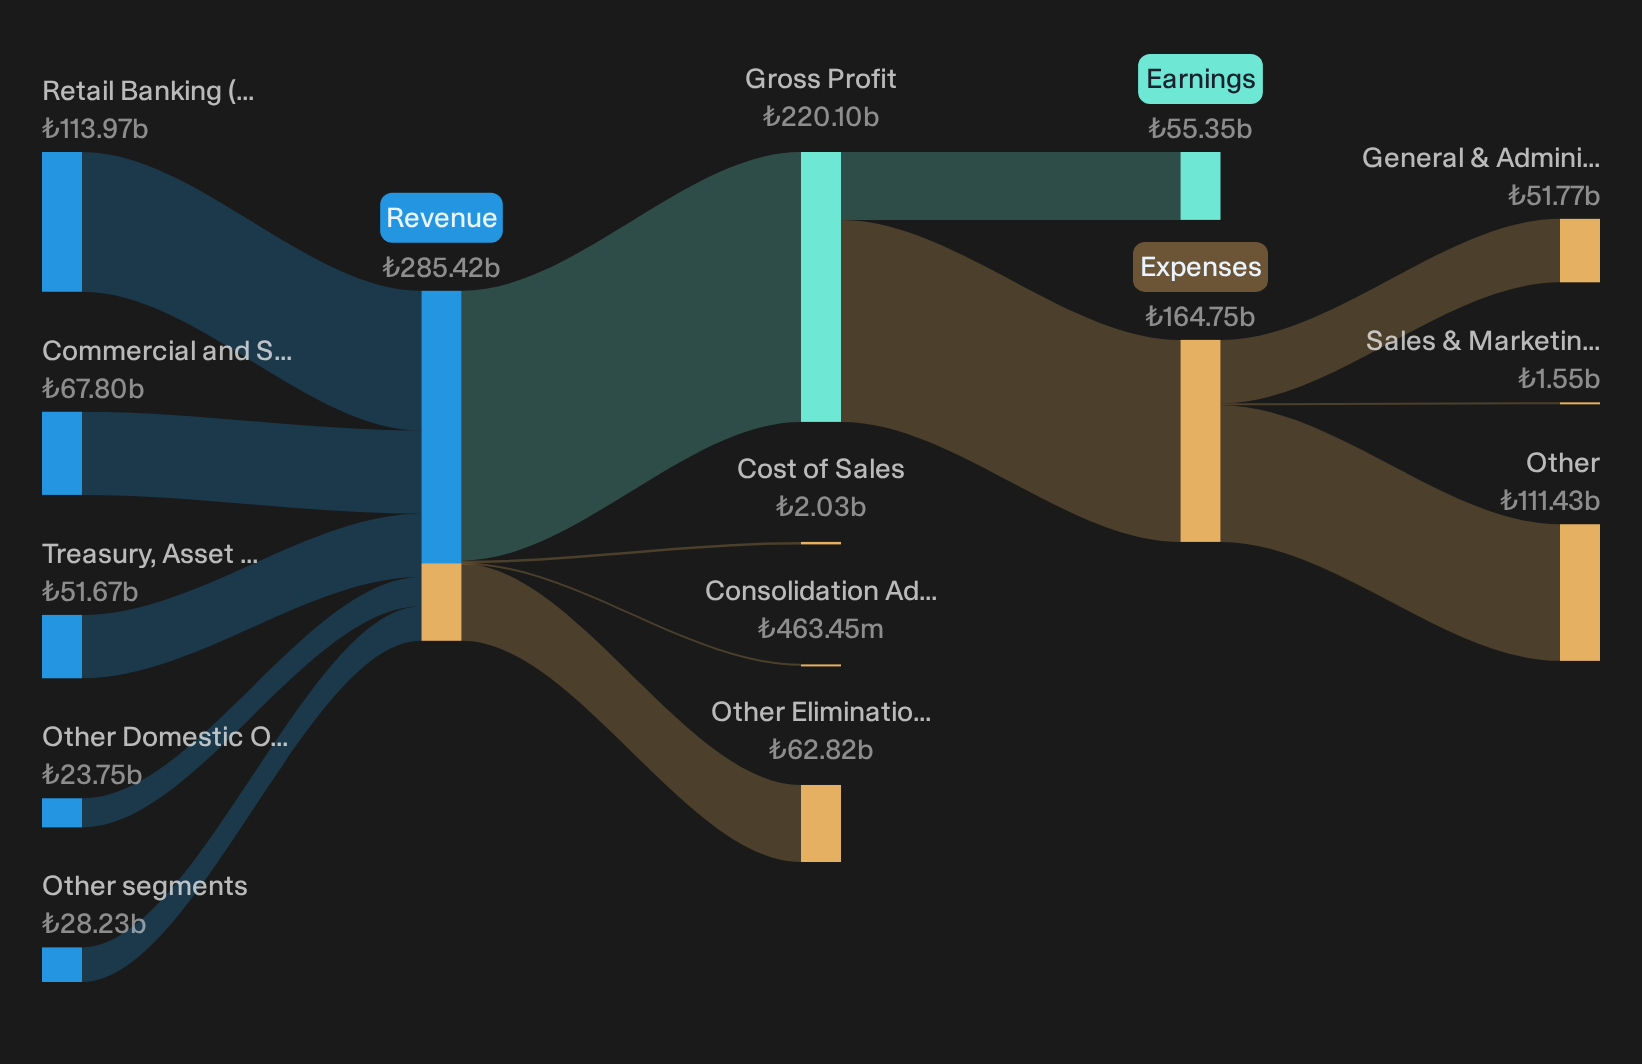
Operations: Yapi ve Kredi Bankasi generates TRY 113.97b from Retail Banking, TRY 67.80b from Commercial and SME Banking, TRY 21.15b from Corporate Banking and TRY 51.67b from Treasury, Asset Liability Management and Other, with TRY 23.75b from Other Domestic Operations and TRY 7.08b from Other Foreign Operations.
Market Cap: TRY 309.5b
Yapi ve Kredi Bankasi matters for this screener because a large demand deposit base and active short term lending book sit directly in the slipstream of changing money-market rates and shifting investor appetite for cash-like assets.
"Dominant demand deposit market share and rapid digitalization support revenue growth, cost efficiency, and strong net margins over the long term."
The real swing factor is how one subtle change in funding costs or deposit mix could ripple through those margins investors are watching so closely.
Those margin ripples are where your thesis really lives, and the full narrative for Yapi ve Kredi Bankasi shows how funding shifts could be masking a stronger earnings engine.
Türkiye Is Bankasi (IBSE:ISCTR)
Overview: Türkiye Is Bankasi is a major Turkish lender that channels customer deposits into loans, payments, cash management and short-duration liquidity services.
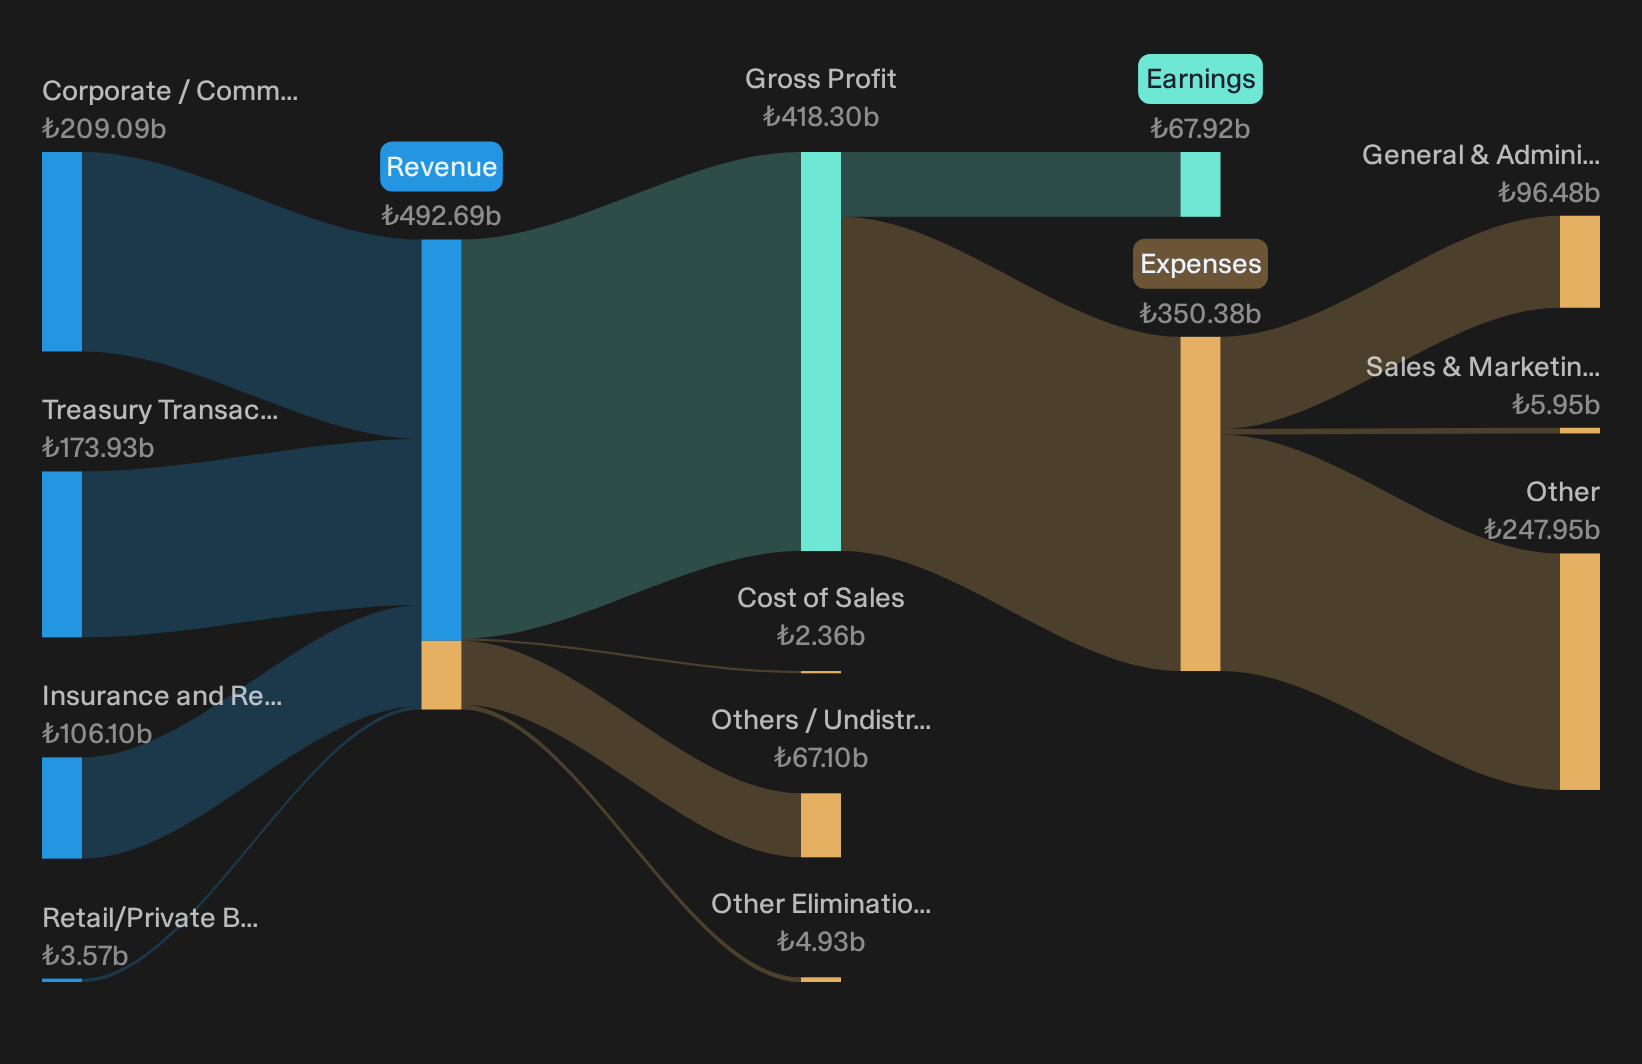
Operations: Türkiye Is Bankasi generates about TRY 209.1b from Corporate / Commercial Banking, TRY 174.0b from Treasury Transactions and Investment Activities, and TRY 106.1b from Insurance and Reinsurance Activities, with smaller contribution from Retail/Private Banking and a reported loss in Others / Undistributed.
Market Cap: TRY 393.9b
Türkiye Is Bankasi matters for this screener because its low cost deposits, fee-rich transaction business and cash management franchise all tie directly into how Turkish savers react when short-term rates, inflation expectations and risk appetite move.
"Structurally lower deposit costs, digital expansion, and strong fee growth are seen as supporting the bank’s earnings, margins, and cost efficiency relative to competitors."
What really shifts the story is how one change in policy-driven funding costs filters through its short-duration book into future margins.
When policy costs start to bite, the full narrative for Türkiye Is Bankasi shows how Türkiye Is Bankasi’s funding mix could be quietly accelerating or masking its next earnings phase.
Seeking Alternatives Before Everyone Else
Fresh ideas move first and slow research trails behind. Spot breakout momentum, catch dropping risk, and track stories flying under the radar for now. Act now.
- Target resilient income by scanning a curated group of 161 dividend fortresses before yields get crowded and the easy income opportunity is gone.
- Hunt for high conviction growth potential with a hand picked 618 high quality undiscovered gems list while these stories remain under the radar for now.
- Ride structural demand for critical materials by assessing a focused basket of 27 best rare earth metal stocks before the crowd fully prices in the supply squeeze.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com