
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Nova (NVMI) Stock Looking Stretched After Its Recent Drop?
Nova has seen its share price pull back sharply in recent weeks after a strong multi year run, which puts fresh attention on whether the current valuation still lines up with the company’s earnings power. With sentiment swinging quickly around the latest headlines, the key issue for you is how much of Nova’s profit profile is already reflected in the stock.
- Over the past 5 years, Nova has returned 228.3%, so a lot now rests on whether that gain is backed up by sustainable earnings strength.
- Recent record revenue alongside higher operating expenses and softer gross margins can support the argument that earnings quality and cost discipline now matter more for how you judge the stock.
- The analysts covering Nova have run their own numbers. See what analysts think Nova's shares could be worth.
The stock’s next move may depend on whether Nova’s current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you want to explore the same earnings-based question that is now hanging over Nova across a wider field, run the numbers on our 35 high quality undervalued stocks.
Has Nova Run Too Far on Earnings?
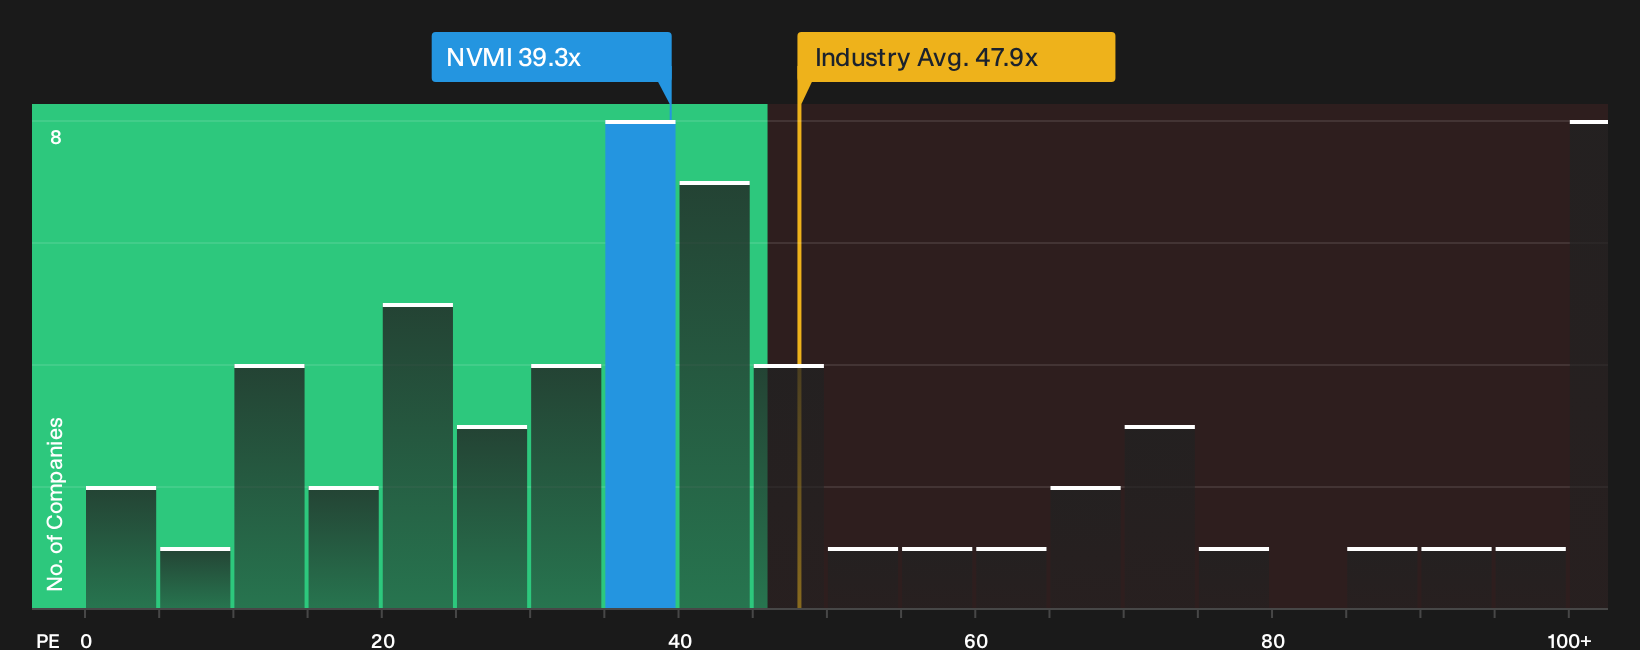
The P/E ratio suits Nova because earnings remain a key reference point for many investors after the recent pullback. On this measure, the stock trades at about 39.3x earnings, which is lower than the semiconductor sector average of roughly 47.9x and also below peers at about 86.7x. That gap indicates the market is not assigning Nova the same earnings premium as many rivals despite its position in the industry.
According to the Fair Ratio framework, which estimates the multiple you might expect given Nova’s growth profile, profitability, size and risk, the current P/E still screens as overvalued. Despite the recent sell-off following record Q2 results and a 13.4% share price drop, the valuation continues to lean to the richer side of what this model implies for the business’s earnings power. Explore the numbers behind Nova's P/E valuation.
The Nova Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Nova's valuation puzzle leaves off by setting out the specific future paths for growth, margins and earnings that would need to play out for the stock to be worth meaningfully more or less than today. Rather than a single ratio or model output, Narratives on Nova's Community page map the underlying assumptions that number rests on, so you can watch how reality lines up with them over time.
One of the top community narratives on Nova: 37% undervalued
"Demand for Nova's advanced metrology and analytics solutions is rising due to semiconductor complexity and global industry investments, supporting broad, diversified growth..."
Discover why this Narrative puts Nova at 37% undervalued.
Nova's valuation still leaves one crucial piece of the puzzle unanswered
You have a picture of what Nova is priced for today, but professional analysts have their own multi year expectations for revenue, margins and earnings that give you a different reference point. Explore where analysts expect Nova to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com