
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is SoundHound AI (SOUN) A Bargain As It Absorbs LivePerson And Names A New CFO?
SoundHound AI (SOUN) just closed its acquisition of LivePerson and installed former LivePerson executive John Collins as chief financial officer. The move puts an experienced AI focused operator in charge of the enlarged group’s finances.
Recent trading has been choppy for SoundHound AI, with the share price up 3.35% over the last day but down 12.92% over 30 days and down 38.96% year to date, while the 1 year total shareholder return has declined 54.40% even after a very large 3 year total shareholder return of about 19x. This suggests short term momentum is fading, even as long term holders still sit on sizeable gains and are reassessing how the LivePerson deal and new CFO might reset the risk and growth story.
Spot 32 AI small caps that, like SoundHound AI, are tied to real customer-service use cases yet still trade like early stage AI stories.Bulls see SoundHound AI transforming LivePerson’s assets into a stronger customer service AI platform. Bears focus on ongoing losses and sharp share price declines. Which story actually fits the current valuation picture?
Most Popular Narrative: 51% Undervalued
Analysts following SoundHound AI see a fair value of about $13.14 a share, roughly double the last close near $6.47. This sets a very optimistic bar for what LivePerson integration and the new CFO might achieve.
The rapid consumer shift toward personalized, hands-free digital experiences is compelling enterprises to integrate advanced voice solutions as a differentiator. SoundHound's unique Voice Commerce ecosystem, agentic AI platform, and multimodal capabilities offer significant upsell and renewal potential, translating to higher net retention and increased recurring revenue.
See why 363 investors see SoundHound AI as 51% undervalued.
Result: Fair Value of $13.14 (UNDERVALUED)
Still, the bullish story around SoundHound AI hinges on rapid revenue growth continuing, while heavy losses, rising operating costs and reliance on large contracts do not overwhelm the thesis.
Find out about the key risks to this SoundHound AI narrative.
Another View: Multiples Flash A Very Different Signal
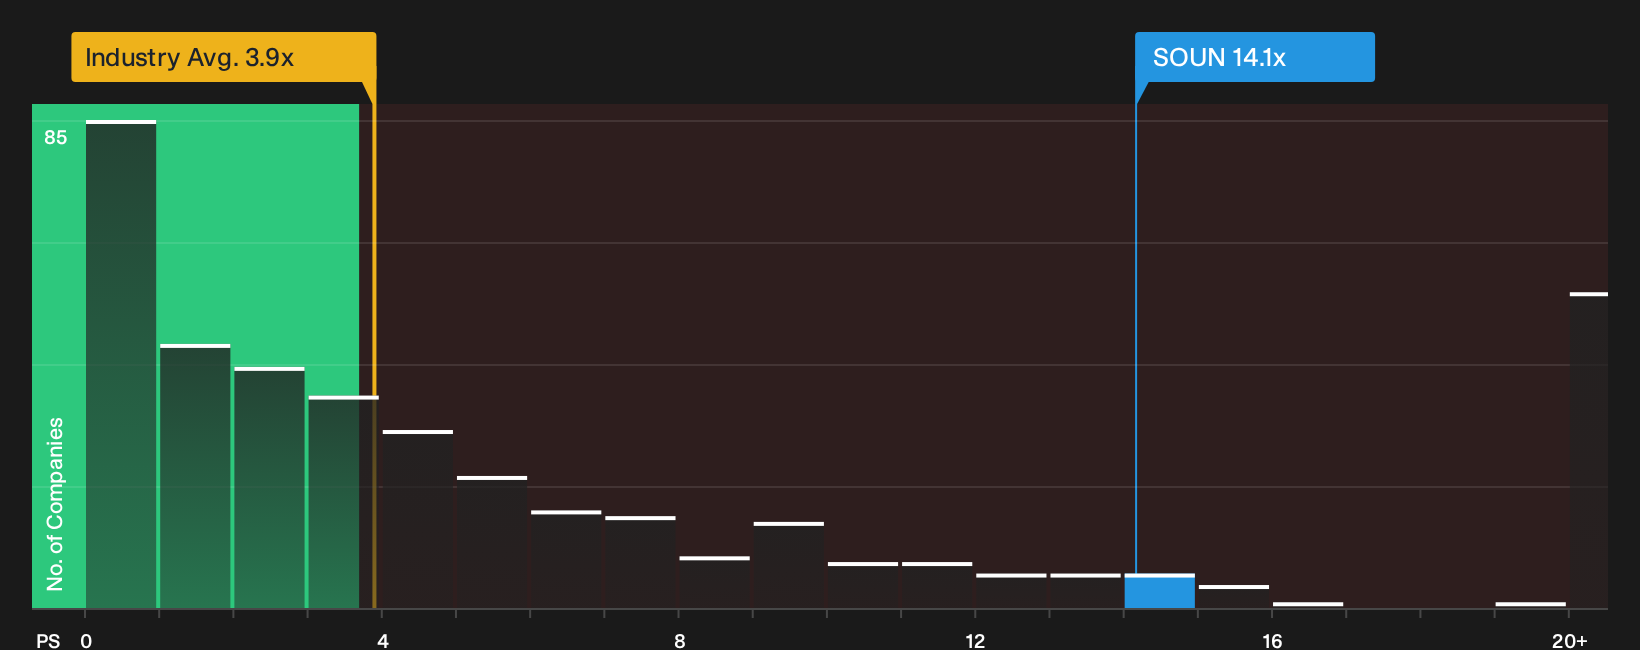
SoundHound AI might appear inexpensive relative to analyst targets, but its current P/S ratio of 14.1x tells a tougher story. That figure is significantly higher than the US Software industry average of 3.9x and also exceeds its own fair ratio of 2.8x. This comparison highlights elevated valuation risk if sentiment cools further. Are you comfortable paying that kind of premium for a business that is still reporting losses?
See what the numbers indicate about this price with our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on SoundHound AI's valuation and business risk profile make the next move tricky, so move quickly to inspect the data, weigh the trade offs, and decide where you stand with 2 key rewards and 3 important warning signs.
Want more ideas beyond SoundHound AI?
Do not stop with a single AI story when there are dozens of other opportunities that might fit your style, risk tolerance, and income needs.
- Scan for potential mispriced opportunities by reviewing our 35 high quality undervalued stocks where strong fundamentals meet compressed expectations.
- Lock in the kind of income profile you actually want by checking companies in the 6 dividend fortresses that focus on resilient payouts.
- Prioritize resilience and sleep better at night by filtering for businesses in the 11 resilient stocks with low risk scores that score well on financial strength and risk controls.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com