
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Covista (CVSA) Undervalued After Chamberlain Named A New Academic Chief And Expansion Plans?
Covista (CVSA) is back in focus after Chamberlain University, its nursing education arm, named Jason Dunne as Chief Academic Officer and outlined plans to open 10 to 15 new campuses through fiscal 2029.
Covista’s latest leadership move at Chamberlain comes against a mixed trading backdrop, with the share price at US$125.49 after a year-to-date share price return of 20.12% but a 1-year total shareholder return that declined 7.33%.
Compare Covista’s education-focused story with a curated set of resilient operators by checking out the list of solid balance sheet and fundamentals (23 results) that could be better positioned to handle ambitious expansion plans.
Covista now sits at US$125.49 after years of strong multi year returns but a weaker recent 1 year stretch, so are investors looking at fresh upside from here or mostly gains that have already played out in the share price?
Most Popular Narrative: 21% Undervalued
On the most followed view of Covista, a fair value of $159.50 against the latest close at $125.49 points to meaningful upside if the narrative plays out as expected under a 7.39% discount rate.
Persistent health care workforce shortages in nursing, medicine and behavioral health create a structural need for large scale training capacity, which can support sustained demand for Covista's programs and underpin revenue growth.
Rising acceptance of flexible digital learning for working adults, reflected in Walden's record 52,400 students and ongoing program launches in areas such as applied behavioral analysis and clinical psychology, can expand addressable markets and support earnings through scale efficiencies.
See why 3 investors see Covista as 21% undervalued.
Result: Fair Value of $159.50 (UNDERVALUED)
Still, the bullish Covista narrative leans heavily on sustained healthcare workforce shortages, as well as on students continuing to favor higher priced digital programs over cheaper online alternatives.
Find out about the key risks to this Covista narrative.
Another View: Covista Through The P/E Lens
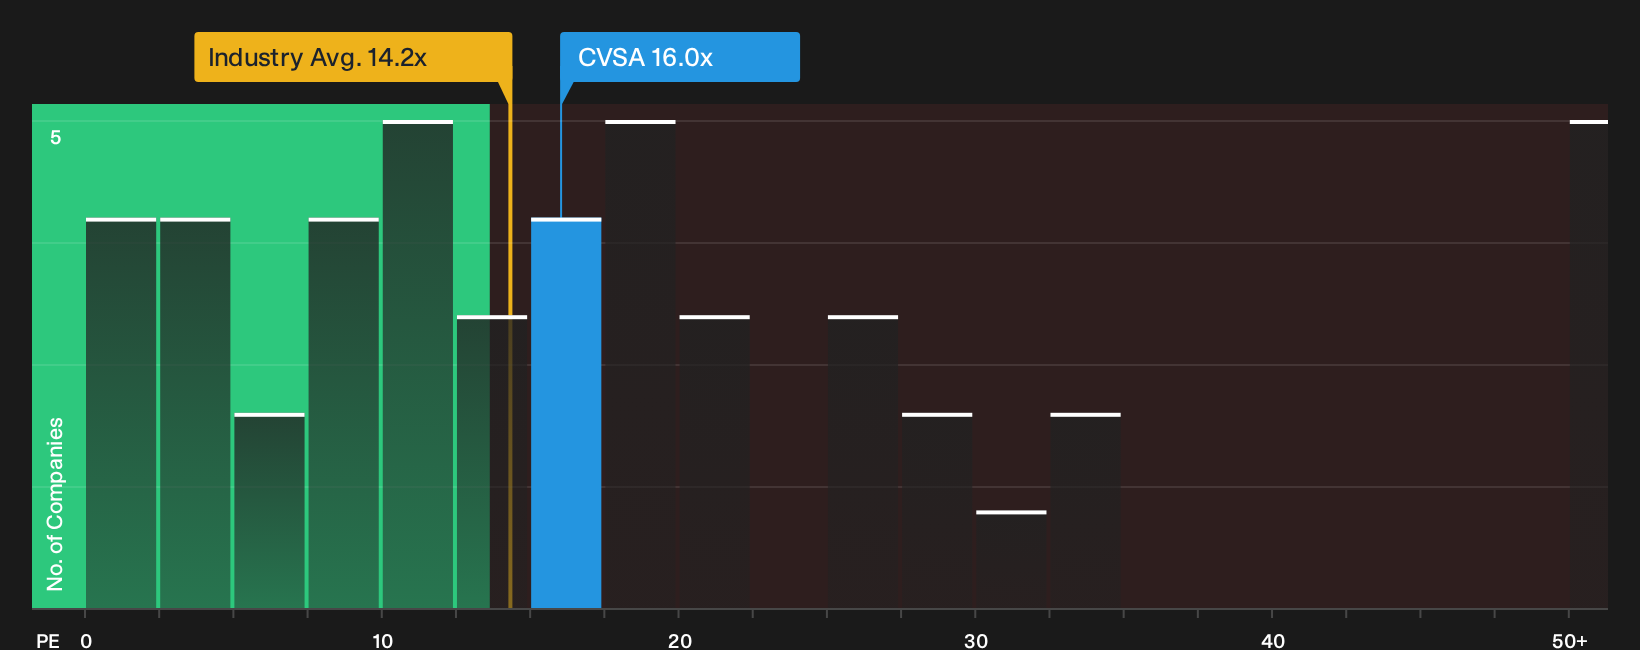
The first Covista story leans on a discounted cash flow view that flags the stock as materially undervalued, yet the simple P/E picture is far less generous. At about 16x earnings, the shares trade richer than the US Consumer Services industry at 14.2x and above the 13x peer average.
That premium multiple sits below an estimated fair ratio of 20.4x, which implies some room for re rating if earnings unfold as expected, but also means there is less of a valuation cushion if the growth narrative disappoints. Is that mix of perceived upside and downside risk a trade off you are comfortable with?
See what the numbers say about this price, then find out in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
For a clearer visual on how Covista’s current pricing stacks up against the wider sector, review the latest relative valuation chart at
Next Steps
Mixed signals on Covista's story so far, so move quickly and stress test the thesis against both sides of the ledger using 4 key rewards and 1 important warning sign.
Looking for more Covista sized investment ideas?
Do not stop at Covista. Fresh ideas often come from comparing different business models side by side, and the right tool can surface those faster.
- Target potential mispricings by scanning a 35 high quality undervalued stocks that screens for quality businesses trading below what their fundamentals might justify.
- Fortify your income stream by reviewing a 6 dividend fortresses that focuses on companies offering higher yields alongside resilient payout histories.
- Dial down risk by checking a 11 resilient stocks with low risk scores that highlights businesses with sturdier balance sheets and more consistent financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com