
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Red Rock Resorts (RRR) Stock Looks Below Fair Value After Its 47% Run
Red Rock Resorts has had a solid run over the past few years, yet the recent pullback in the share price puts fresh focus on what investors are actually paying for its earnings today. With the stock now trading around US$54.75, the key issue is whether that level still lines up with the profits the business is generating.
- Over the past 5 years the stock has returned about 47.1%, which puts real weight on whether the current earnings base can support the valuation that has built up.
- Profitability has softened even as Red Rock Resorts continues to pay a regular dividend and invests in its workforce, which can shape expectations for future margins and cash generation.
- There is a second opinion on Red Rock Resorts worth weighing. See what analysts think Red Rock Resorts's shares could be worth.
The issue now is whether the stock price investors see today is justified by the earnings power Red Rock Resorts is delivering.
If you want a wider view of how other businesses with earnings stories like Red Rock Resorts are priced today, a focused stock screen built around 35 high quality undervalued stocks.
Is Red Rock Resorts a Bargain on Earnings?
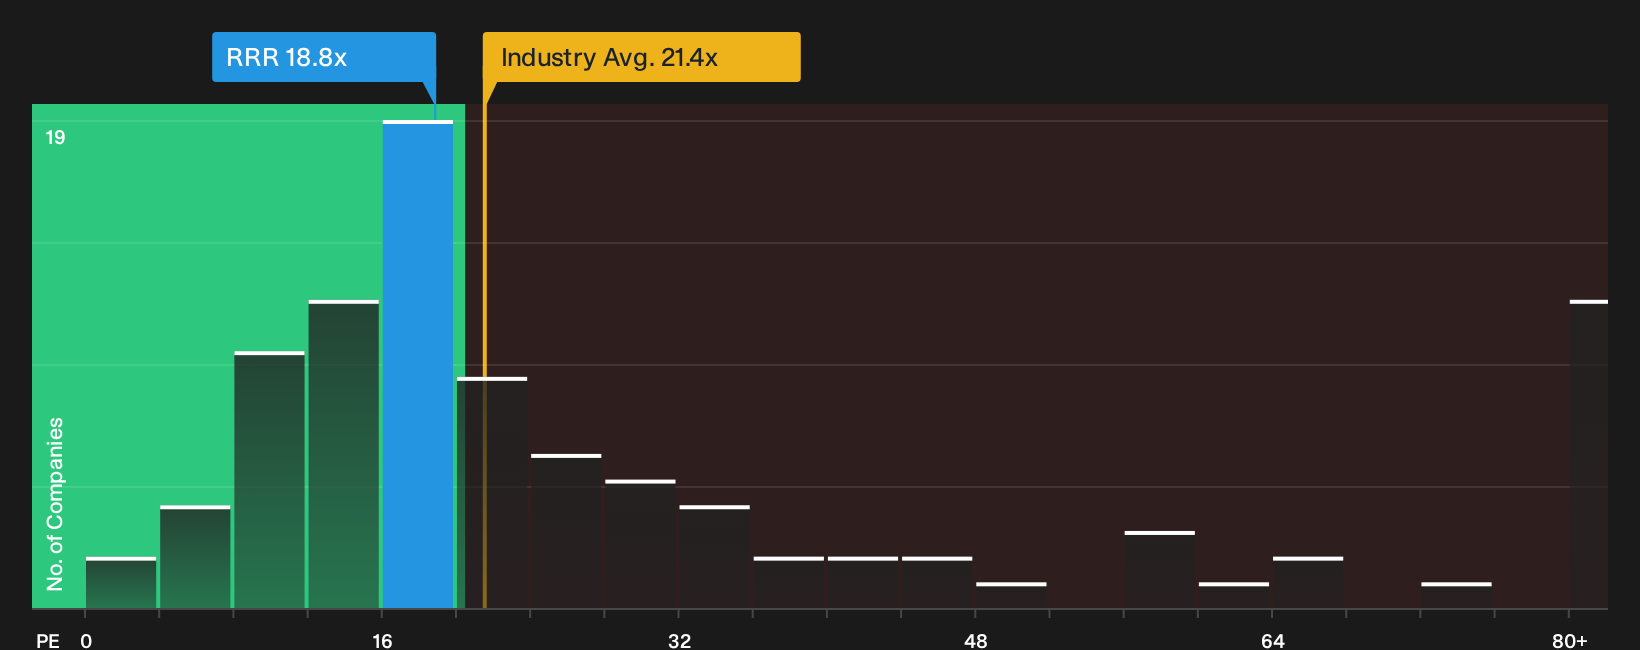
The P/E ratio suits Red Rock Resorts because earnings remain the main anchor for how investors view a mature gaming and hospitality business. At roughly 18.8x earnings, the stock trades above the peer group average of about 14.1x, yet below the wider hospitality industry on roughly 21.4x. That mix indicates the market values Red Rock Resorts at a premium to closer peers while still leaving some gap to the broader sector.
Because the latest quarter showed softer profits even as dividends continued, the P/E discount to the hospitality industry ties back to questions about how durable current earnings are. On the other hand, a more tailored fair P/E level, which blends the company’s margins, growth profile, size and risk, sits above today’s multiple, so on this framework the shares appear undervalued. The employee stock award around the 50th anniversary may help align staff incentives, yet the earnings multiple still prices Red Rock Resorts at a level that reflects some caution around its profit path. Explore the numbers behind Red Rock Resorts's P/E valuation.
The Red Rock Resorts Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the valuation question for Red Rock Resorts leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s price. Each narrative ties its implied number to a clear view on how Red Rock Resorts' expansion prospects, profitability and risk profile could evolve, giving you something concrete to revisit as fresh information comes through.
One of the top community narratives on Red Rock Resorts: 24% undervalued
"The company's large land bank and disciplined approach to new development projects in high-barrier-to-entry locations uniquely position Red Rock Resorts..."
Discover why this Narrative puts Red Rock Resorts at 24% undervalued.
One more angle on Red Rock Resorts that could change your view
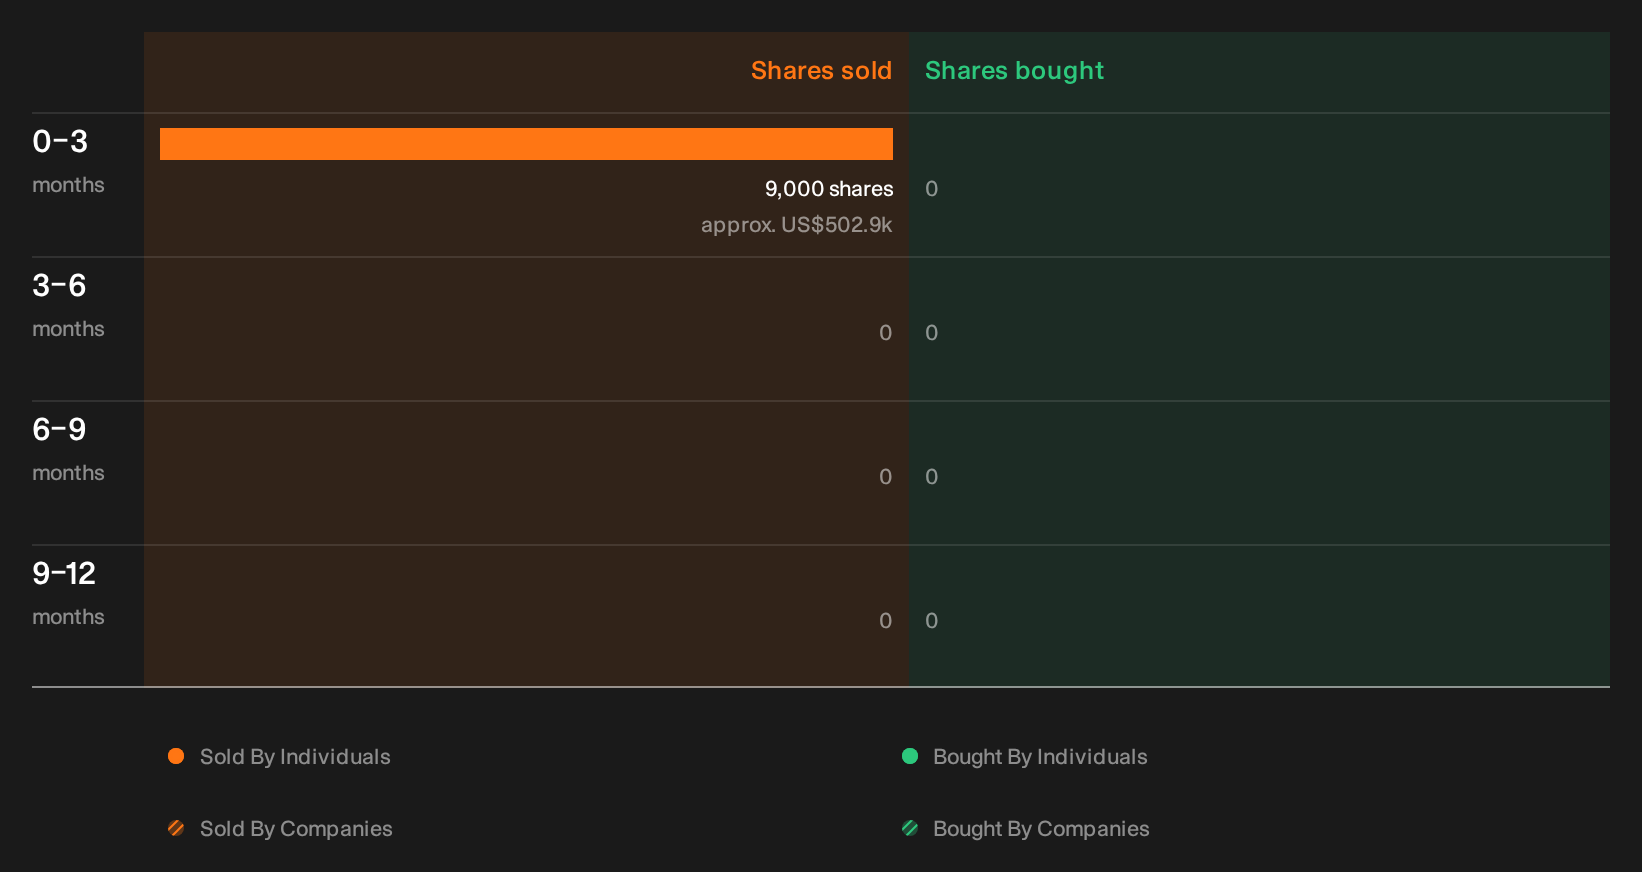
Before you move on from Red Rock Resorts, it is worth checking what recent moves by senior insiders might be signalling about their own conviction in the story. See the recent insider selling flagged for Red Rock Resorts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com