
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Crane (CR) Is Back In Focus, What Is Drawing Attention Now?
Crane (CR) moved back into focus after it agreed to buy Trillium Flow Technologies’ U.S. pumps business for about US$240 million. The deal is anchored in municipal water and wastewater infrastructure.
Crane’s latest move comes after a soft patch in the share price, with the stock down 8.74% over the past month and 3.76% over 90 days. It is still showing a 6.25% year to date share price gain and a 256.58% five year total shareholder return that points to long term momentum rather than a short term story.
Spot opportunities around Crane’s move in critical water infrastructure by scanning our hand-picked 38 power grid technology and infrastructure stocks, which also leans into long-term spending on pipes, pumps, and grid upgrades.Crane now trades below both analyst targets and one estimate of fair value, even as investors cool on the stock after the Trillium deal. Is that discount caution well placed, or overly harsh on the pumps pivot?
Most Popular Narrative: 16% Undervalued
Crane last closed at $199.25, while the most followed narrative anchors fair value at $238.00 using an 8.6% discount rate. That gap frames the Trillium pumps deal as part of a longer, infrastructure heavy earnings story rather than a quick trade.
Continuous shift of the Process Flow Technologies portfolio into higher-growth, resilient segments such as water/wastewater management, cryogenics for space launch, and biopharma (as evidenced by strong order books and recent wins) leverages secular tailwinds around resource efficiency and environmental sustainability, driving revenue growth and margin stability.
See why 5 investors see Crane as 16% undervalued.
Result: Fair Value of $238.00 (UNDERVALUED)
Still, the story around Crane can shift quickly if the integration of recent deals drags on profitability or if weaker European chemical demand squeezes Process Flow Technologies orders.
Find out about the key risks to this Crane narrative.
Another View: What Crane’s P/E Is Telling You
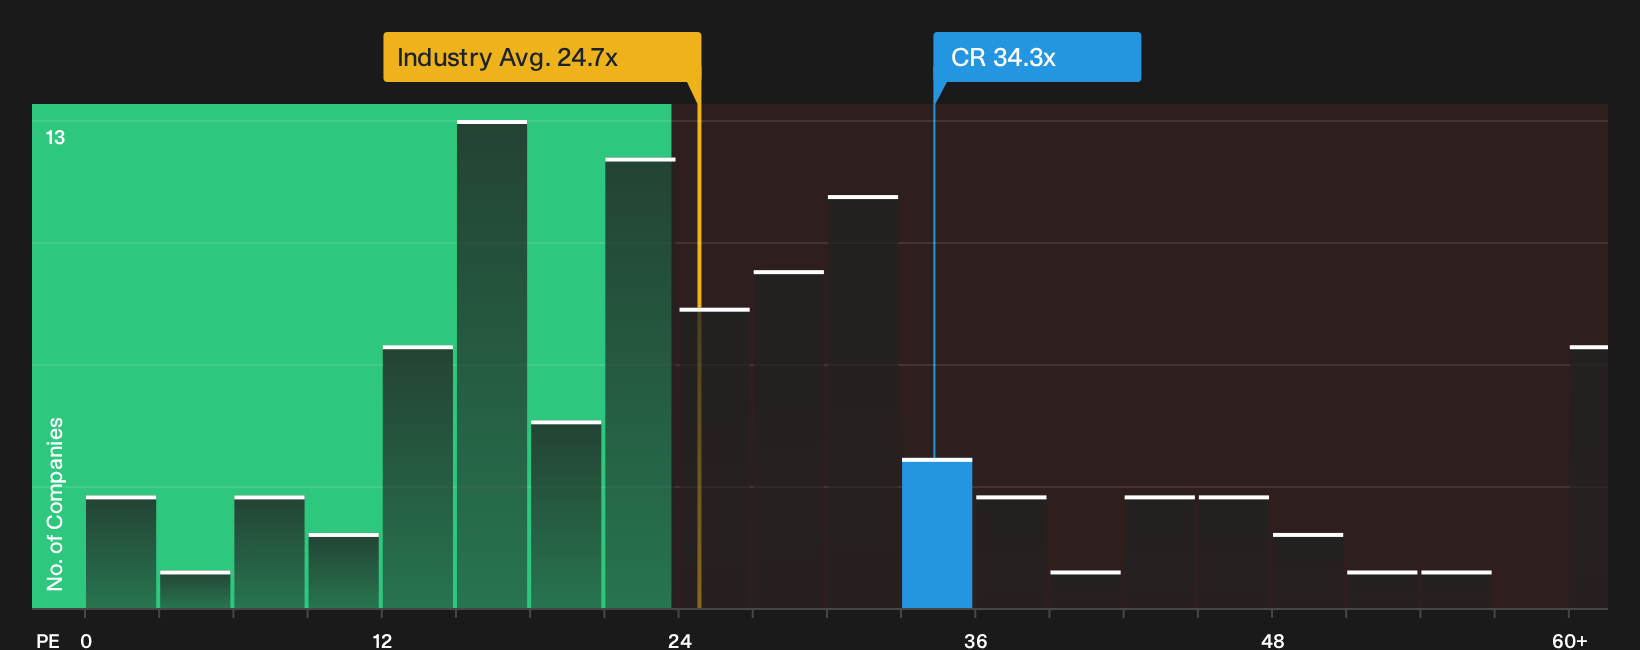
Analyst narratives and fair value models frame Crane as modestly undervalued, yet the current P/E of 34.3x paints a tougher picture. That multiple sits above the US Machinery sector at 24.7x, the peer group at 29.5x, and a fair ratio estimate of 24.1x.
In practice, that means investors are paying a premium today relative to both industry norms and where the fair ratio suggests the market could move. The question is whether Crane’s acquisition track record and critical infrastructure tilt justify paying a higher multiple, or if that premium simply adds extra valuation risk if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of premium P/E and pumps exposure leaves you on the fence about Crane, move quickly to test the numbers yourself and focus on where the risk reward balance really sits. To see that split laid out clearly, walk through the 3 key rewards and 1 important warning sign.
Looking for more Crane investment ideas?
Crane might be front of mind today, but your next strong opportunity could come from a completely different corner of the market if you know where to look.
- Target stability and potential mispricing by scanning our 35 high quality undervalued stocks that filters for quality businesses trading below their estimated worth.
- Strengthen income potential and consistency by reviewing our 6 dividend fortresses built around higher yield payouts with supporting fundamentals.
- Dial down downside risk by focusing on our 11 resilient stocks with low risk scores that highlights companies with more resilient financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com