
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Boxing Partnership Might Change The Case For Investing In Turning Point Brands Stock (TPB)
- ALP Supply Co., part of Turning Point Brands, rolled out its nicotine pouch brand across 11 European markets. Earlier this year, it completed an exclusive Official Nicotine Pouch Partner deal with Matchroom Boxing, securing in-ring, broadcast, on-site and digital exposure at three major UK and Ireland events in September and October 2026.
- The Matchroom Boxing agreement gives ALP and Turning Point Brands concentrated visibility in boxing strongholds of the UK and Ireland. This could test how effectively the business converts premium placement and fan activations into sustainable demand for its modern oral products in new geographies.
- We will now look at how Turning Point Brands' investment narrative could be influenced by ALP's Matchroom Boxing exclusivity in Europe.
Scan how Turning Point Brands' Matchroom Boxing move compares with other consumer-focused plays pushing into new territories by exploring our curated list of 15 high quality undiscovered gems.
Turning Point Brands Investment Narrative Recap
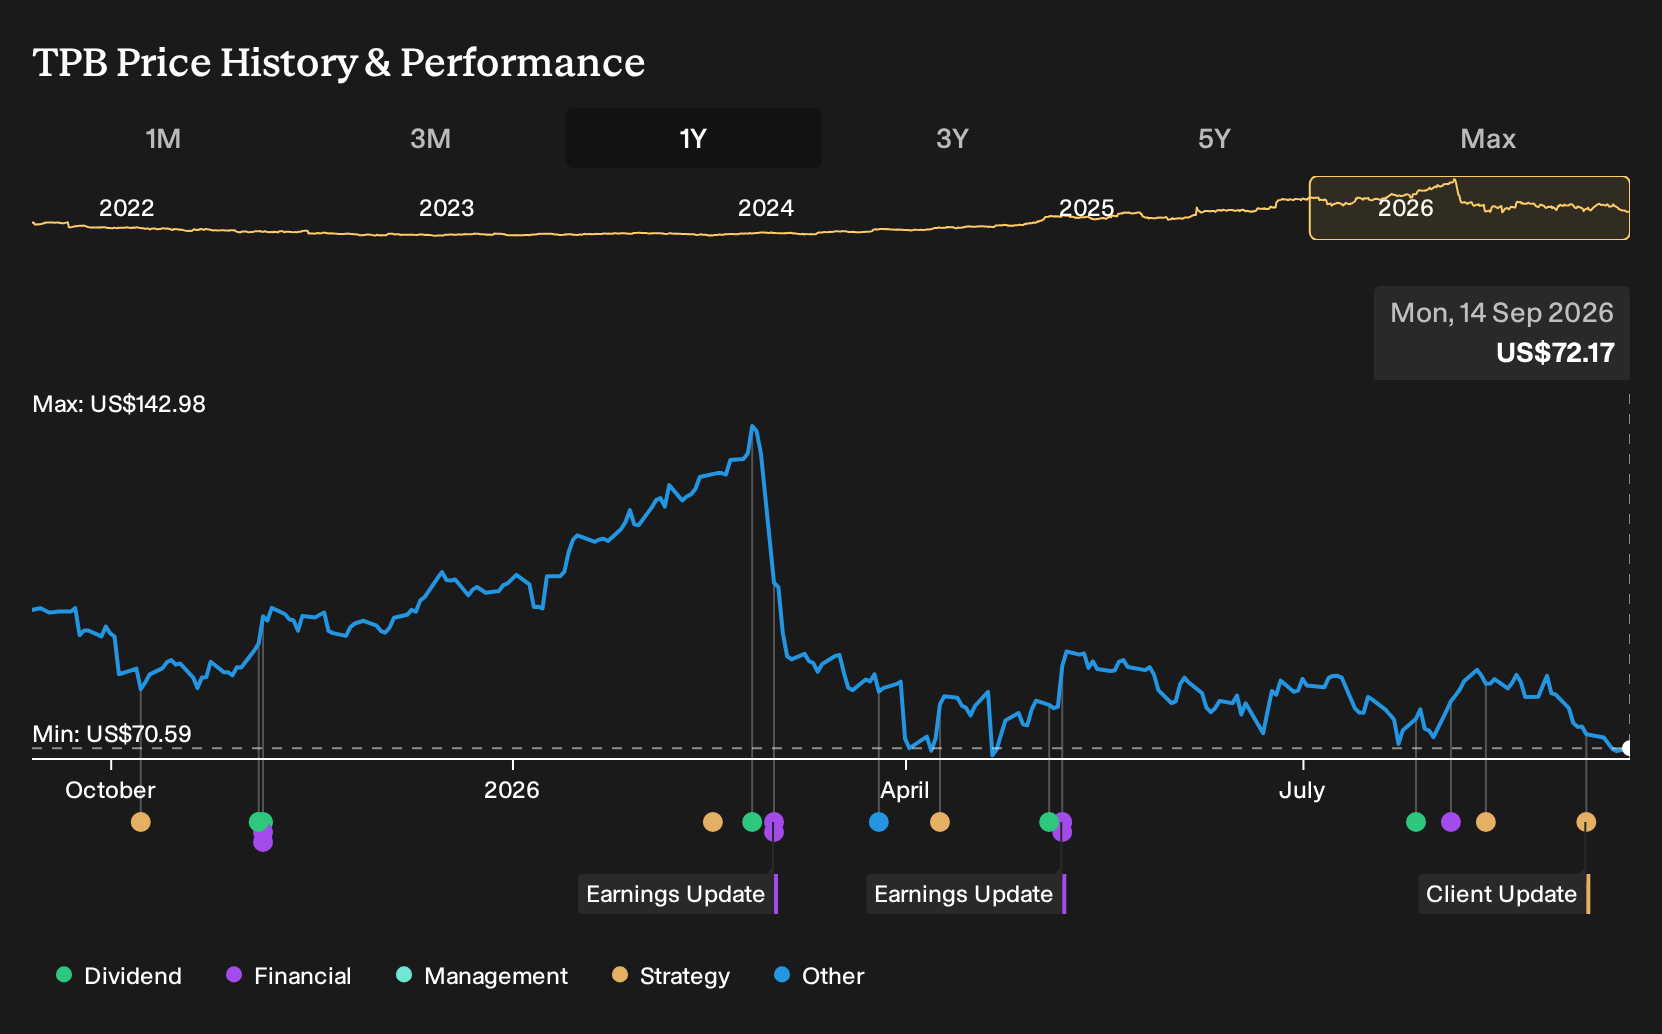
To own Turning Point Brands, you need to believe the shift toward modern oral products can support healthier earnings over time despite recent pressure on margins and a weak 1 year share return. The Matchroom Boxing deal makes that modern oral bet more visible, but it does not change the fact that profit margins fell from 12.6% to 8.8%.
The near term catalyst still sits in execution on distribution and marketing spend for ALP and other premium offerings. The biggest risk remains high exposure to nicotine pouches, where competition, regulation, flavor restrictions, or supply chain issues could weigh on revenue and keep margins from recovering.
The Matchroom Boxing partnership is the clearest recent announcement tied to that catalyst. ALP Supply Co. took exclusive nicotine pouch rights across three major Matchroom events in the UK and Ireland, with in ring, broadcast, on site, and digital presence. That is a concentrated test of Turning Point Brands’ ability to turn brand visibility into sell through in 11 new markets.
For you, the question is whether this kind of marketing-heavy push justifies higher SG&A and keeps the earnings growth narrative intact. Turning Point Brands already leans on modern oral for roughly a quarter of revenue. Execution in Europe needs to work without eroding profit quality further or exposing the business to outsized regulatory or pricing shocks.
Turning Point Brands' narrative projects US$940.6 million revenue and US$144.9 million earnings by 2029. This assumes 25.1% yearly revenue growth and requires earnings to rise by about US$89.5 million from US$55.4 million today.
Discover how Turning Point Brands' fair value indicates a potential 80% upside to its current price before other investors close that gap.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community range from about US$50.76 to US$158.91, so retail opinions on Turning Point Brands already span a wide gap. These estimates predate the Matchroom Boxing news, so you are weighing them against fresh execution risk in modern oral, heavier marketing spend, and possible regulatory shifts. Explore the full spread of Community viewpoints before anchoring on any single outcome.
Explore 3 other Turning Point Brands fair value estimates, including one that suggests potential upside of as much as 120% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and instincts.
- A great starting point for your Turning Point Brands research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Turning Point Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Turning Point Brands' overall financial health at a glance.
Looking For More Investment Ideas Beyond Turning Point Brands?
If Turning Point Brands has sharpened your view on risk, reward, and execution, it can be useful to line that thinking up against other listed companies using the Simply Wall St Screener.
- For investors who care about valuation discipline and fundamentals, compare Turning Point Brands with a curated set of companies flagged as 35 high quality undervalued stocks.
- If stability and balance sheet strength matter most to you, widen your watchlist with a list of solid balance sheet and fundamentals (23 results) that already meet strict financial health checks.
- Those seeking a different mix of potential growth and limited downside can review a 11 resilient stocks with low risk scores that still clear quality filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com