
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 US Financial Stocks Worth Watching If Rates Stay Higher For Longer
With the Federal Reserve expected to lift rates again and signal that higher borrowing costs could stick around through 2026, the market is quietly reshuffling winners and losers. Some financial stocks may see richer interest income while other areas of the market feel valuation pressure. This article walks through three US financial sector stocks exposed to this rate story and explains why their setups might matter for your portfolio decisions right now.
The stocks highlighted below are just a sample, and the full screen surfaced 13 more US financial companies with equally compelling rate exposure stories that are not covered here. To identify your own potential beneficiaries of higher Fed policy, go straight to the US Financial Sector Beneficiaries of Higher Interest Rates screener to filter, analyze, and focus on the ideas that best fit your risk profile.
Capital Southwest (CSWC)
Overview: Capital Southwest is a Dallas based business development company that lends to and co invests in lower middle market US businesses, targeting interest income and selective equity upside.
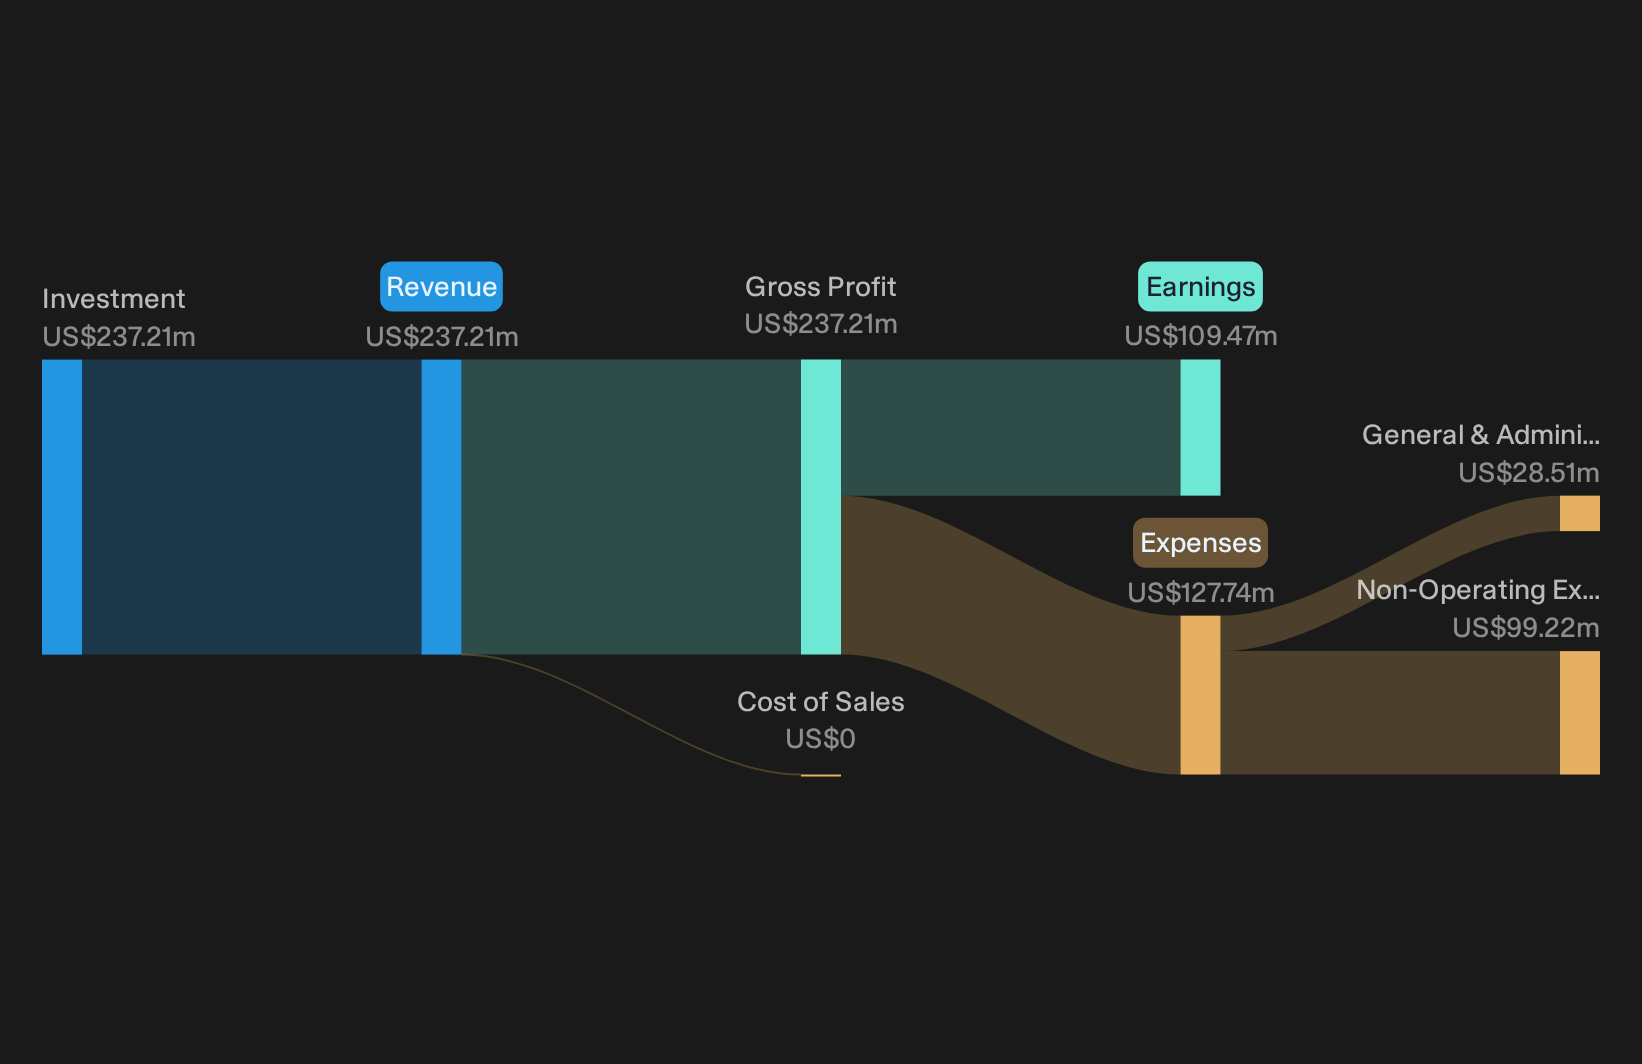
Operations: Capital Southwest generates its entire US$237 million of revenue from investment activities in the United States, reflecting a pure play US credit focus.
Market Cap: US$1.5 billion
Capital Southwest fits this higher rate screener because it primarily earns interest on floating rate loans to US borrowers. As a result, the business is closely linked to the mechanics of Federal Reserve policy rather than stock market sentiment.
"Expansion of the private credit market, fueled by tightening bank regulations and generational wealth transfer among business owners, should enlarge the addressable market and support sustained revenue and asset growth.
What matters next is how pressure on its funding and payout mix ultimately affects margins and dividend resilience.
That payout question is exactly what the full narrative for Capital Southwest unpacks, including how Capital Southwest’s funding mix and rate sensitivity could be masking both risk and upside.
American Integrity Insurance Group (AII)
Overview: American Integrity Insurance Group provides residential and specialty property coverage in Florida, with earnings closely tied to insured weather risk and investment income.
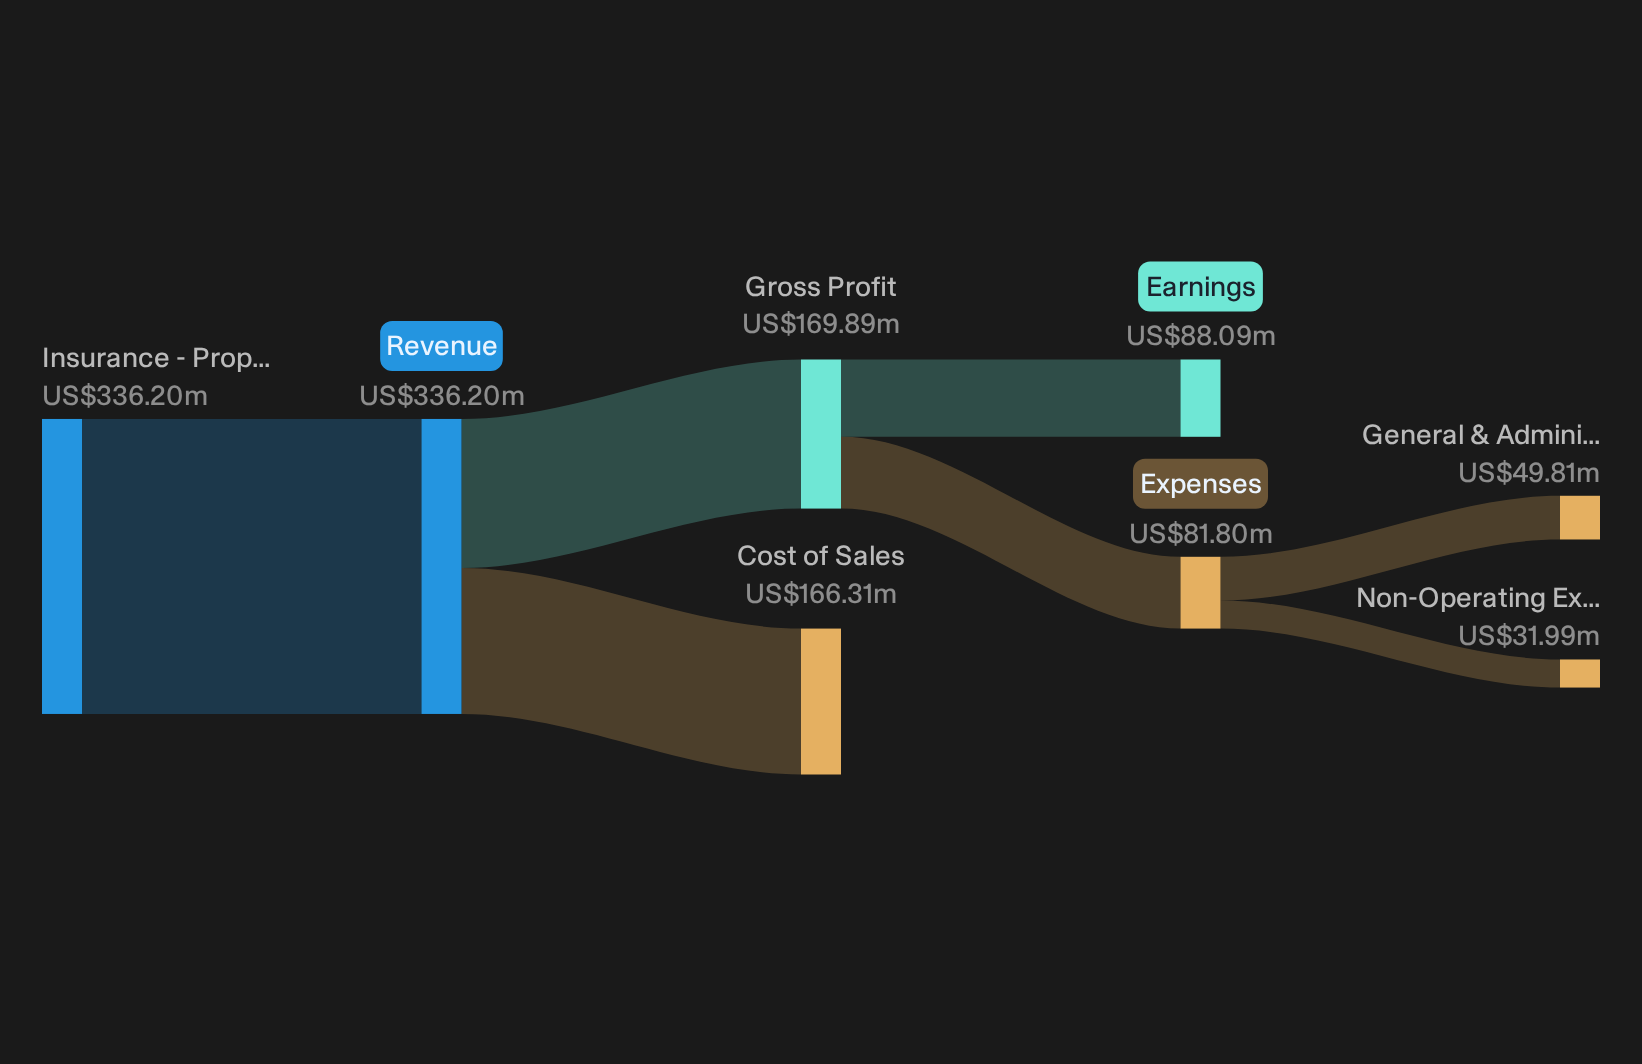
Operations: American Integrity Insurance Group generates US$336 million of revenue entirely from US property and casualty insurance operations.
Market Cap: US$508 million
American Integrity Insurance Group brings a different angle to the higher rate story. Its core Florida homeowners book pairs rate-sensitive investment income with weather-exposed underwriting, making it a pure play on how insurers convert higher-for-longer yields into durable returns.
"AII has a reinsurance program to limit the impact of catastrophic losses; it should be noted that this coverage runs up until June 2026 at which point it needs to be renegotiated, so a big increase in reinsurance pricing could impact earnings in 2026."
What investors will really be watching is how one unresolved cost pressure shapes the balance between strong revenue momentum and future profitability.
That unresolved pressure is exactly why the full narrative for American Integrity Insurance Group explores how American Integrity Insurance Group’s earnings story could be reshaped by reinsurance costs and higher-for-longer yields.
Kingstone Companies (KINS)
Overview: Kingstone Companies is a US property and casualty insurer focused on personal lines like homeowners and renters coverage, as well as niche commercial policies.
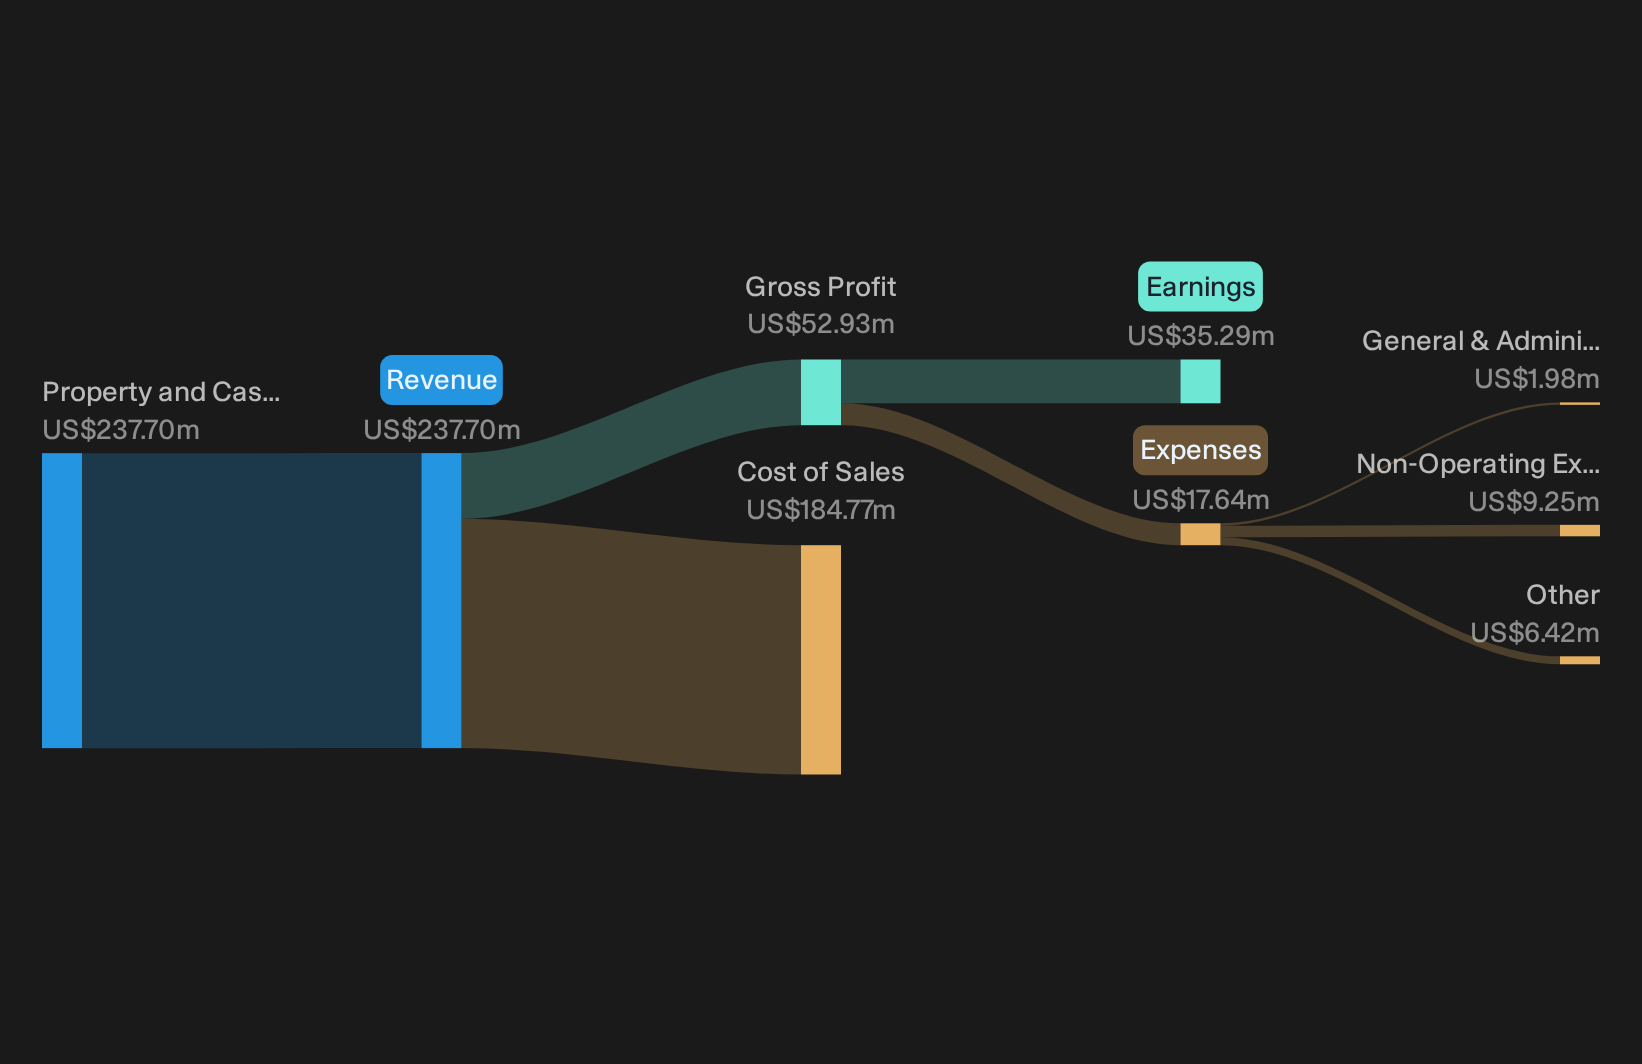
Operations: Kingstone Companies generates all of its US$238 million in revenue from property and casualty insurance written in the United States.
Market Cap: US$278 million
Kingstone Companies fits a higher rate financials screen because it is a US insurer with a sizeable bond portfolio, and management plans to reinvest maturing securities at higher yields, which could affect investment income. For investors watching how that filters through to returns, a shift in bond reinvestment economics may play an important role in determining how much of the rate backdrop reaches the bottom line.
That reinvestment shift is the real hinge, and the Kingstone Companies financial health report shows how Kingstone Companies’ balance sheet strength might amplify or blunt that rate tailwind.
Seeking Fresh Alternatives Before They Fly
Breakout moves often start quietly while momentum builds under the radar. Review these fresh stock ideas before they attract broader attention.
- Target dependable income streams by scanning a curated group of high yield opportunities in the 6 dividend fortresses and consider how changing rates or prices may affect potential entries.
- Explore real-world AI momentum by focusing on companies already translating algorithms into revenue through the 75 profitable AI stocks that aren't just burning cash while expectations and valuations are still developing.
- Evaluate potential policy-sensitive opportunities by filtering critical suppliers in the 91 nuclear energy infrastructure stocks and assessing how infrastructure spending or sentiment changes could affect these stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com