
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
JBT Marel (JBTM) Changed Its Name And Slid This Year, Is It A Bargain?
JBT Marel (JBTM) has drawn fresh attention after its recent name change from John Bean Technologies Corporation in January 2025. This has prompted investors to reassess a food processing equipment specialist with global reach and mixed recent share performance.
Recent trading tells a more cautious story, with the share price falling 2.3% in the last day and down 25.8% year to date. Total shareholder return is down 18.7% over one year but modestly positive over three years, suggesting momentum has faded after earlier gains.
Compare JBT Marel's recent pullback with other machinery and automation players by scanning our hand picked 38 robotics and automation stocks that are already reacting to similar trends in industrial demand.
JBT Marel now trades at a steep discount to both analyst targets and some intrinsic value estimates after a sharp slide. Is that a pricing error or a fair reflection of rising doubt about its prospects?
Most Popular Narrative: 35% Undervalued
JBT Marel's most followed narrative pegs fair value at $172.64, well above the recent $111.79 close. This puts the current sell off in a different light for anyone focused on long term cash flows.
The JBT Marel merger is already realizing synergy benefits, enabling margin expansion through cost savings, portfolio breadth, increased cross selling, and a deeper customer relationship via integrated system sales. Management expects this to continue driving net margin improvement into 2027.
Strategic expansion in aftermarket, service, and refurbishment revenue with high margins and recurring characteristics both improves margin mix and enhances earnings visibility, helping to stabilize and grow free cash flow.
See why 3 investors see JBT Marel as 35% undervalued.
Result: Fair Value of $172.64 (UNDERVALUED)
Still, analyst expectations hinge on smooth integration and tariff relief, and any stumble on merger execution or extended trade friction could quickly challenge this JBT Marel upside story.
Find out about the key risks to this JBT Marel narrative.
Another View On JBT Marel's Valuation
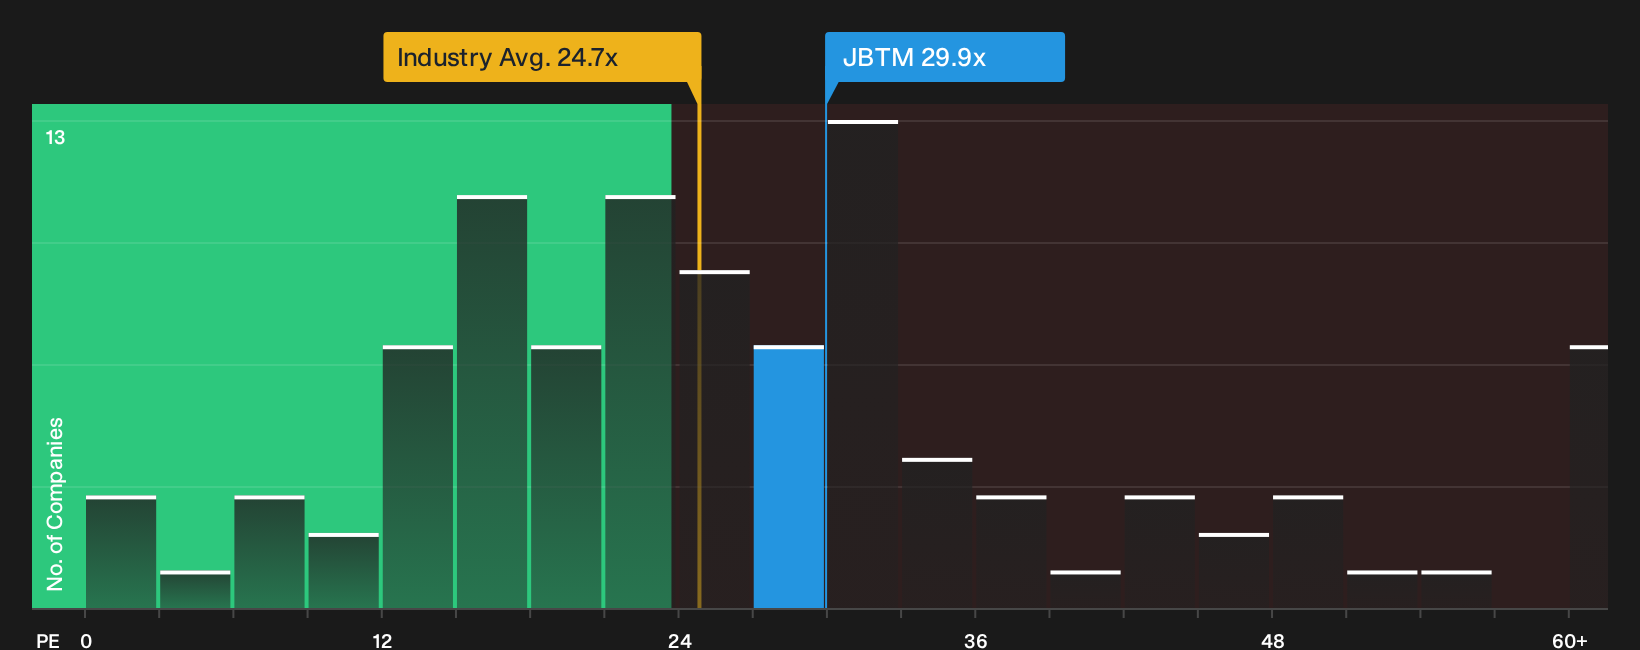
The earlier narrative leans heavily on analyst fair value estimates and long term earnings forecasts. A simple P/E cross check tells a different story. JBT Marel trades on roughly 29.9x earnings, above the US Machinery sector on 24.7x but below a peer group average of 58.5x.
Our fair ratio for JBT Marel sits at 44x. That gap suggests the market is already pricing in some risk, yet not assigning the kind of premium implied by the fair ratio. The question for investors is whether current earnings quality and integration questions justify that discount or leave room for rerating.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of optimism and concern sit side by side in the JBT Marel story, so move quickly, review the numbers yourself, and weigh up the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond JBT Marel?
If JBT Marel has your attention, do not stop there. Broaden your watchlist with a few focused stock ideas that match your preferred balance of value, income, and resilience.
- Target dependable cash generators by scanning a curated 35 high quality undervalued stocks set up to spotlight companies where price and fundamentals appear out of sync.
- Prioritize income and staying power by checking a hand picked group of 6 dividend fortresses that aim to combine yield with staying power.
- Reduce portfolio stress by reviewing a focused 11 resilient stocks with low risk scores chosen for balance sheet strength and lower overall risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com