
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Definium Therapeutics (DFTX) Stock Looks Fully Valued On Fresh Phase 3 Trial News
Definium Therapeutics has delivered a striking run in recent years, and the question now is whether a share price near US$40 has stretched too far beyond what its book value supports. With fresh drug trial headlines in the mix, the key issue for investors is how much of that optimism is already baked into the stock.
- Over the past 3 years, Definium Therapeutics has produced a very large total return of about 8.9x, which puts real weight on whether the balance sheet can justify that kind of rerating.
- Positive Phase 3 results for DT120 in generalized anxiety disorder and FDA Breakthrough Therapy status in major depressive disorder may support expectations for stronger future cash generation, which feeds directly into how investors weigh the company’s equity against its book value.
- The analysts covering Definium Therapeutics have run their own numbers. See what analysts think Definium Therapeutics's shares could be worth.
The issue now is whether Definium Therapeutics' current share price is adequately supported by the value of the assets on its balance sheet when judged against the industry average.
For context on whether Definium Therapeutics' 888.9% three year return and book value premium are unusual, it helps to compare them with other 35 high quality undervalued stocks
Has Definium Therapeutics Run Too Far on Book Value?
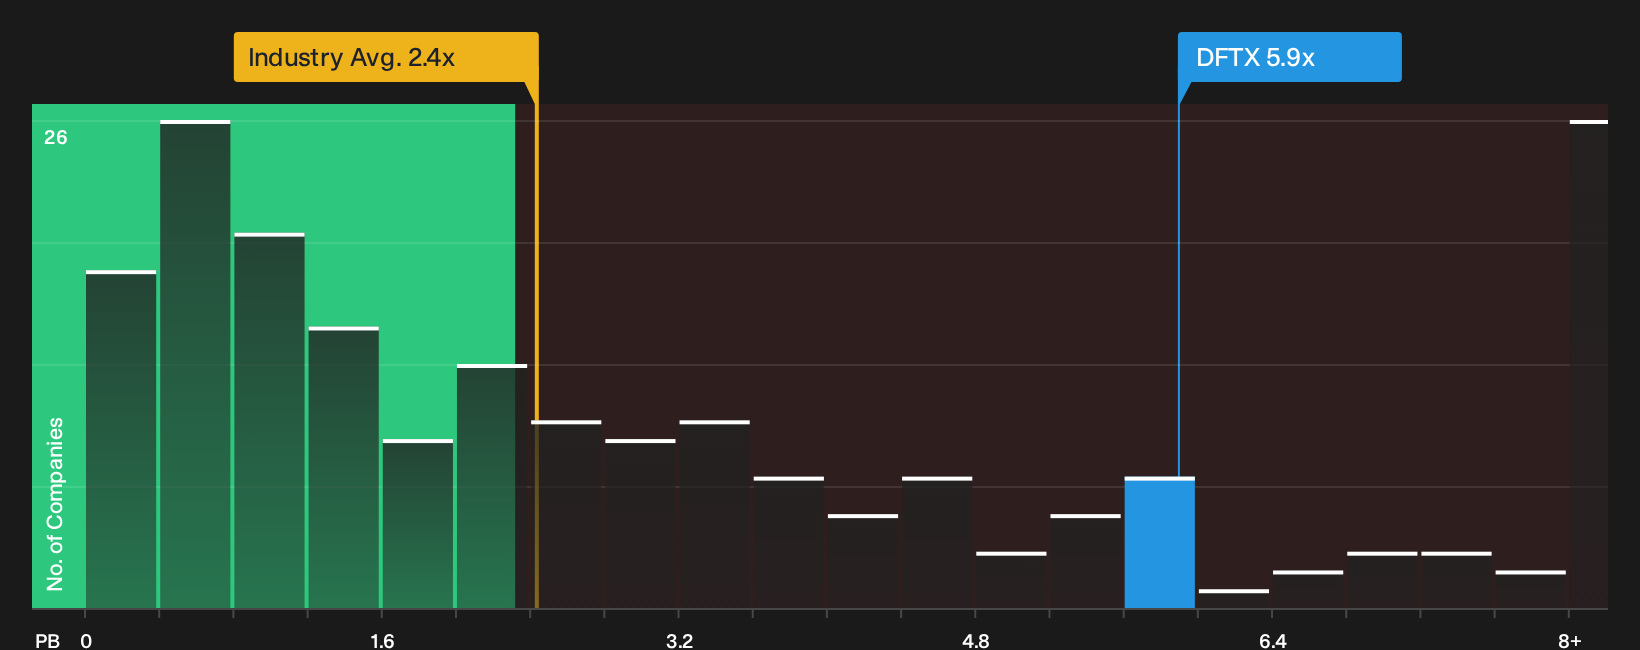
P/B fits Definium Therapeutics because the balance sheet still matters a lot for a business that is not yet built around steady earnings. The stock currently trades on a P/B of 5.9x, compared with an industry average of about 2.4x and a peer group that sits far higher at roughly 57.0x. On this yardstick, the shares screen as overvalued against the broader Pharmaceuticals sector, even though they look far less extreme than some direct biotech peers.
Because the latest Phase 3 DT120 data and FDA Breakthrough Therapy status have lifted expectations, that richer P/B multiple effectively asks you to pay a sizeable premium to the sector for Definium Therapeutics' current equity base. To judge whether that is acceptable, you would need to weigh how comfortable you are with the existing losses, the projected free cash flow path, and the execution risk around DT120 converting from trial success into commercial cash generation. Explore the numbers behind Definium Therapeutics's P/B valuation.
The Definium Therapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Definium Therapeutics pick up where the valuation puzzle leaves off by spelling out which assumptions on growth, profitability and future earnings would need to hold for the shares to be worth materially more or less than today’s price on the Community page. Each narrative treats Definium Therapeutics' fair value as a thesis about the business that you can revisit over time, rather than a one off snapshot.
One of the top community narratives on Definium Therapeutics: 40% undervalued
"Approaching three pivotal Phase III readouts for DT120 ODT in GAD and MDD in 2026 positions the company to potentially transition from a pure R&D story..."
Discover why this Narrative puts Definium Therapeutics at 40% undervalued.
One More Definium Therapeutics Check That Sits Beside The Share Price
Before moving on from Definium Therapeutics, it is worth asking who is actually steering the business and how their pay packets line up with the risks and rewards that current shareholders carry. See who runs Definium Therapeutics and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com