
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Starbucks (SBUX) Could Be 12% Undervalued After Its $1b Store Refresh Plan
Starbucks (SBUX) is committing US$1b to refurbish up to 9,000 North American stores with softer seating and bookstore style touches, a fresh piece of Brian Niccol’s broader turnaround plan.
Investors have already started to price in parts of Starbucks’ refresh story, with the share price up 18.0% year to date to US$99.08, even though the 30 day share price return is down 8.0% and the 1 year total shareholder return sits at 22.9%.
Scan other consumer brands that could be setting up for their own turnaround story with the same kind of store level refresh by reviewing the following: 15 high quality undiscovered gems.
Starbucks shares have climbed hard this year, then cooled over the past month. Is that swing telling you more about the underlying business, or is it simply a reset in sentiment before you look at the valuation?
Most Popular Narrative: 12% Undervalued
On Simply Wall St’s most followed narrative, Starbucks screens as undervalued, with a fair value estimate of about $112.23 against the recent $99.08 close. That gap rests on a specific turnaround script that leans heavily on store upgrades, service changes and international execution.
The Back to Starbucks strategy aims to improve partner engagement and reduce turnover, which is expected to enhance the customer experience and drive higher quality transactions, potentially increasing revenue and net margins.
Plans to reestablish Starbucks as a third place by evolving coffee house designs and expanding in attractive growth markets could lead to increased customer visits and improved unit economics, thus boosting revenue.
See why 225 investors see Starbucks as 12% undervalued.
Result: Fair Value of $112.23 (UNDERVALUED)
Still, the Starbucks narrative depends on labor investments stabilizing margins and on comparable sales avoiding a deeper slide if consumer spending weakens further.
Find out about the key risks to this Starbucks narrative.
Another View On Starbucks Valuation
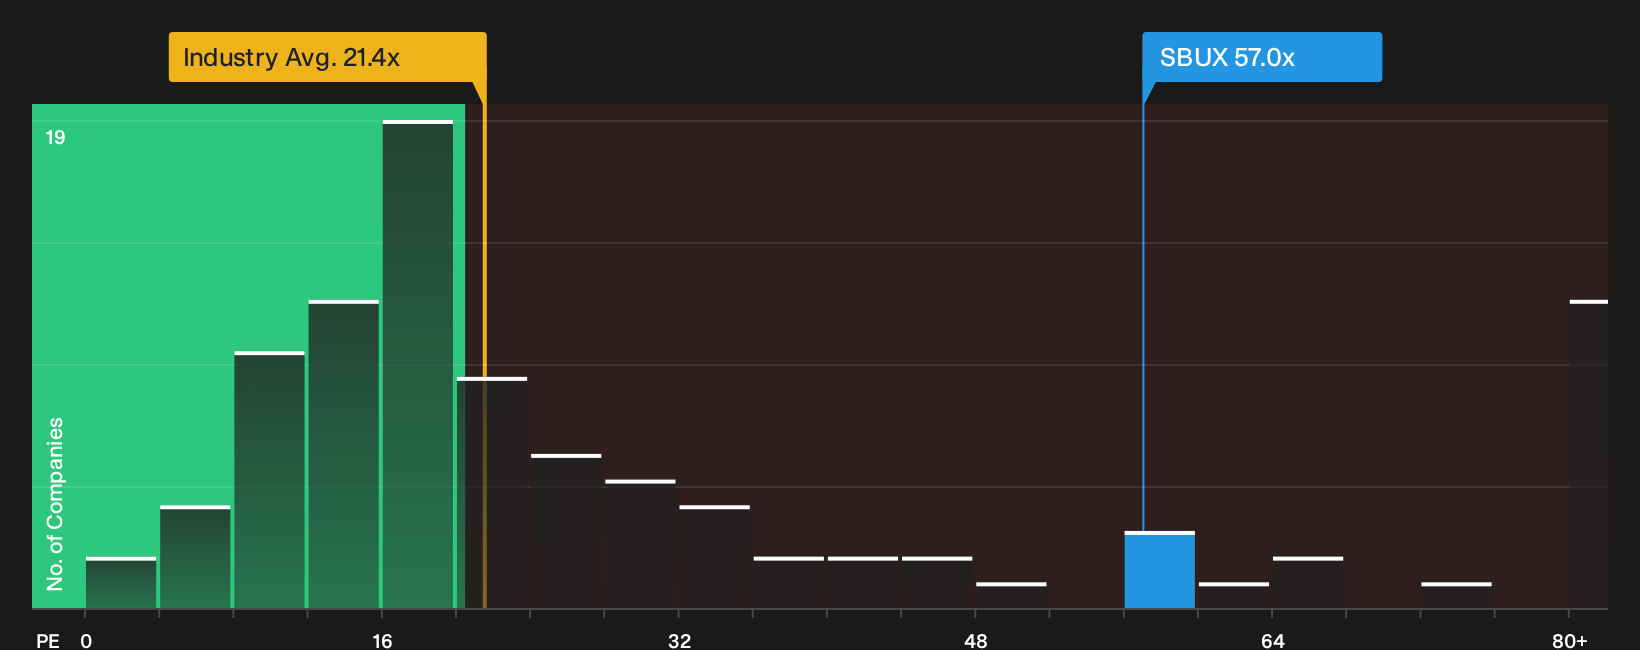
A second lens on Starbucks skips the cash flow narrative and looks at what investors are already paying for its earnings. The stock trades on a P/E of 57x, compared with about 21.4x for the broader US Hospitality group and a 44.2x average for peers.
The fair ratio for Starbucks is estimated at 34.8x, far below the current multiple. That gap points to meaningful valuation risk if sentiment cools or earnings disappoint, rather than obvious upside. Which story do you think holds more weight: the turnaround script or the rich starting point on price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Starbucks do not have to leave you on the fence, especially when both risks and potential rewards are already on the table. Take a closer look at the data, pressure test your own thesis, and weigh the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Starbucks?
Starbucks might be the starting point, not the finish line. Use this momentum to widen your watchlist and pressure test fresh opportunities.
Scan the market with tools that help you filter quickly and focus your energy on ideas that actually fit your approach.
- Target sturdier balance sheets and steadier fundamentals by running a focused search through the list of solid balance sheet and fundamentals (23 results).
- Hunt for potential mispricings by reviewing companies that screen as both financially healthy and attractively valued in the 35 high quality undervalued stocks.
- Prioritise resilience by zeroing in on businesses that currently flag well on financial risk checks within the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com