
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Sartorius (XTRA:SRT3) Could Be 29% Below Fair Value After Conference Focus
Sartorius (XTRA:SRT3) is heading into a busy conference stretch, with management set to speak at Jefferies’ Swiss Healthcare Summit in Zurich on 2 September and Bernstein’s Pan-European Strategic Decisions Conference in London on 9 September.
Sartorius has seen its share price soften recently, with a 1-month share price return of 4.04% and a year-to-date share price return down 8.03%. At the same time, the 1-year total shareholder return of 15.53% contrasts with a weaker 3-year and 5-year total shareholder return, which indicates fading longer term momentum ahead of these conference appearances.
Spot opportunities beyond Sartorius by scanning our hand-picked 616 high quality undiscovered gems that investors may be overlooking.After a choppy stretch for Sartorius, the gap between the current €227.90 share price and the range of fair value estimates is doing the real talking. Where does that spread genuinely leave you in terms of valuation risk and opportunity?
Preferred P/E of 80.2x for Sartorius: Is it justified?
On price, Sartorius sits in an awkward spot for many investors, with the share at €227.90 while different valuation lenses send mixed messages. The discounted cash flow output points to upside, yet the market is also assigning a steep P/E, which raises questions about how much of the earnings story is already embedded in today’s quote.
The preferred gauge here is the P/E ratio. For Sartorius, that sits at 80.2x, which is high for a business that already has an established position in bioprocess solutions and lab products. A P/E compares what you pay per share to the earnings generated per share, so it is essentially the price tag on each euro of profit.
Investors are being asked to pay far more per euro of earnings than many peers. The stock is described as expensive versus the global life sciences group, where the average P/E is 35.3x, and it is also labelled expensive compared to the peer set on 42.1x. The fair P/E level from the SWS fair ratio work sits at 37.1x, which is less than half of the current multiple. This gap clearly frames how far sentiment could shift if the market moves closer to that reference point.
Explore the SWS fair ratio for Sartorius.
Result: Price-to-earnings of 80.2x (OVERVALUED).
Still, the rich 80.2x P/E leaves Sartorius exposed if earnings expectations reset or if sentiment toward high-multiple life science stocks cools further.
Find out about the key risks to this Sartorius narrative.
Another view on Sartorius using our DCF model
P/E paints Sartorius as expensive, yet the SWS DCF model points a different way. With the share price at €227.90 and the future cash flow value estimated at €293.43, the model suggests the stock trades at a discount. Which signal do you trust more?
Look into how the SWS DCF model arrives at its fair value.
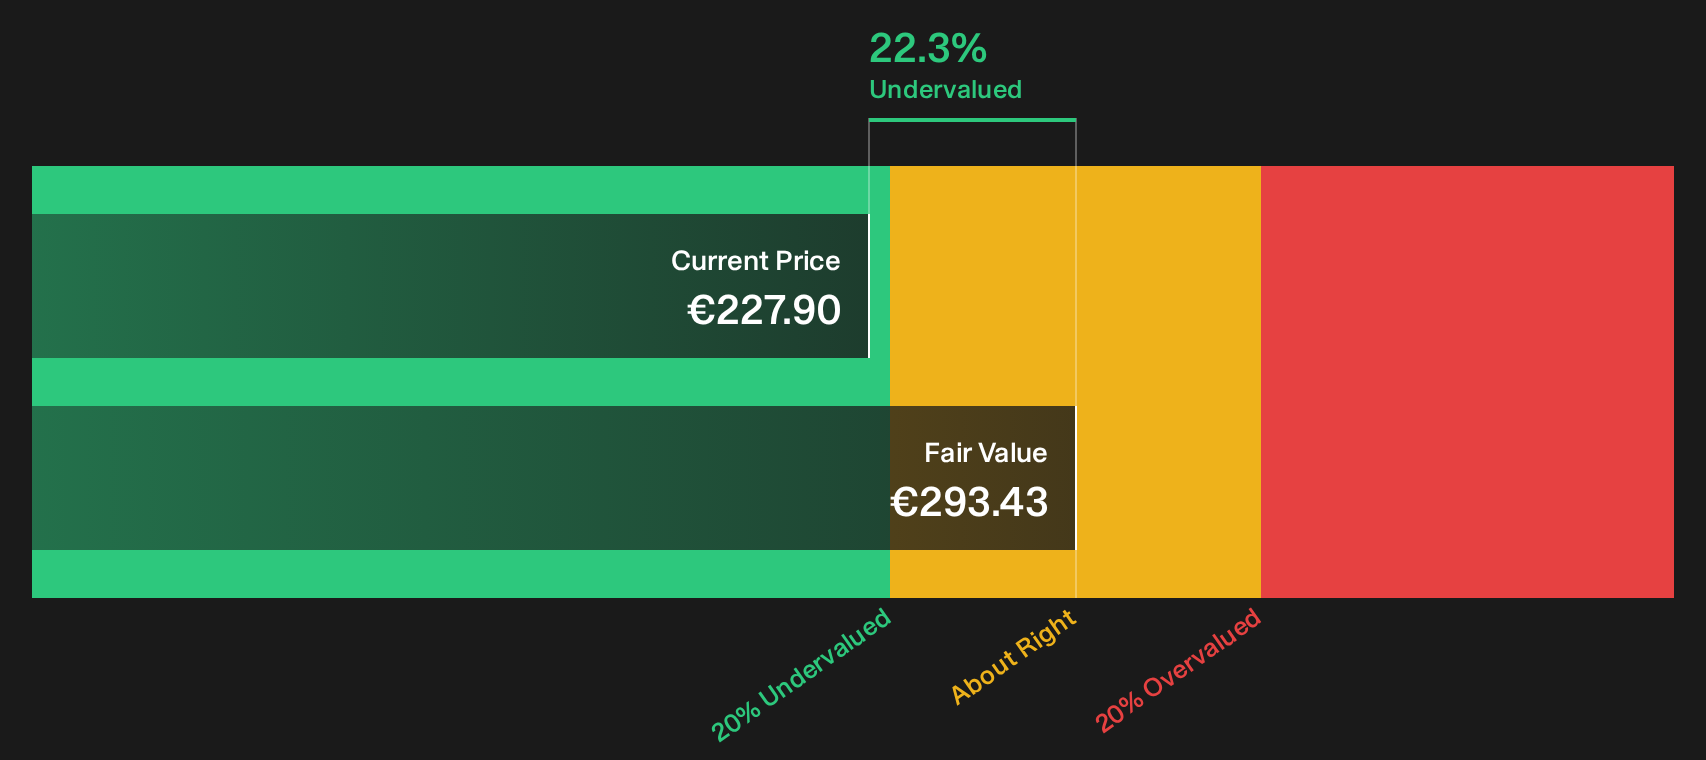
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sartorius for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 189 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed read on Sartorius leaves you uncertain, move quickly from headlines to hard numbers and form your own stance with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Sartorius?
If Sartorius has sharpened your focus on pricing power and quality, you could broaden your watchlist with a few targeted hunting grounds for potential opportunities.
- Explore resilient compounding potential by scanning a curated pool of high quality companies trading below estimated value using the 189 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses with robust cash flows and meaningful payouts through the 161 dividend fortresses.
- Prioritise capital preservation first, then upside, by filtering for financially sturdy, lower risk shares via the 103 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com