
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Flowserve Stock's CFO Change Means For Shareholders
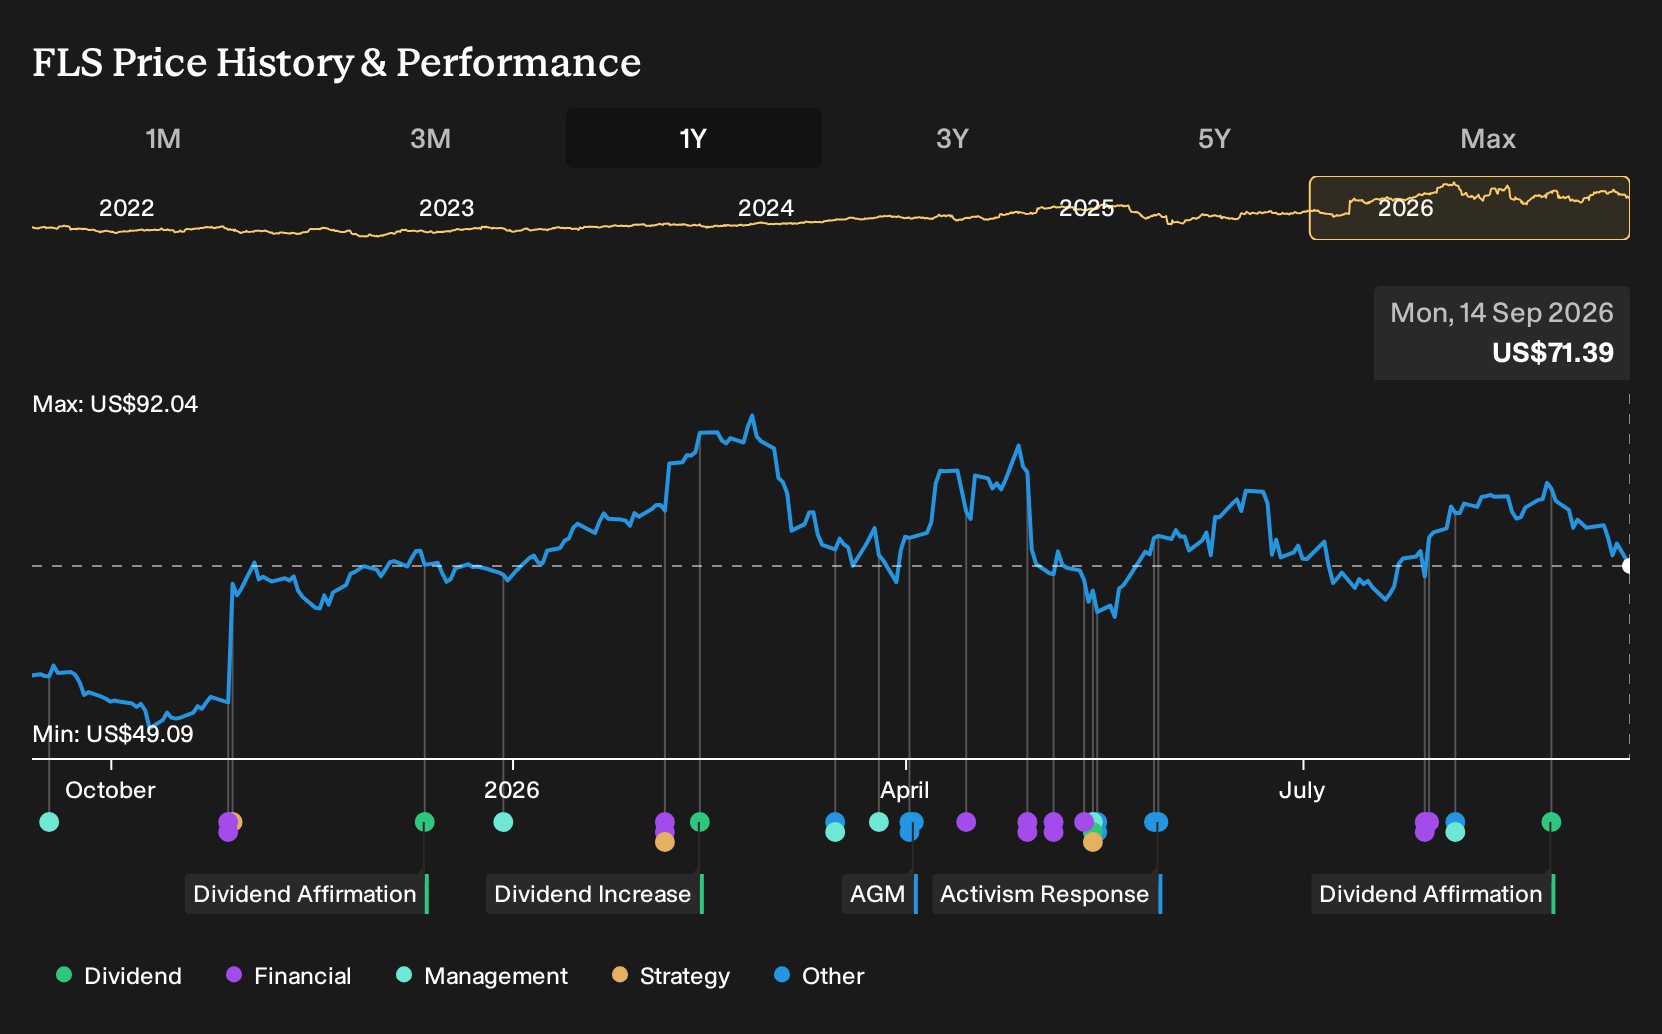
- Flowserve announced that Brian Ezzell, currently Vice President of Financial Planning & Analysis, Treasurer, and Investor Relations, will become Senior Vice President, Chief Financial Officer and interim Chief Accounting Officer on October 1, 2026, following the resignation and September 30, 2026 departure of Amy Schwetz.
- The move places Flowserve’s financial planning, treasury, investor communication, and accounting oversight under one executive. Ezzell has direct experience with global supply chains and has held prior FP&A leadership roles at Kimberly-Clark and Fossil Group.
- Next, attention will be on how Flowserve's investment narrative develops as Brian Ezzell assumes the combined CFO and interim Chief Accounting Officer responsibilities.
Flowserve Investment Narrative Recap
To own Flowserve, you need to believe the order book in pumps and valves for energy, clean energy and water infrastructure can keep underpinning steady projects and aftermarket work, even if approvals in energy and chemicals stay uneven. The key near term swing factor remains execution on that backlog and keeping margins firm as large engineered orders move through the system.
The biggest current operational risk still sits in project delays, pricing pressure on bids and the FCD division's integration issues, not this CFO transition. Management has said full year guidance is unchanged. This suggests the Ezzell appointment itself is not a material near term catalyst or threat to the underlying thesis right now.
The most relevant development here is Flowserve confirming no change to its full year guidance alongside Brian Ezzell's appointment as CFO and interim Chief Accounting Officer. That ties this leadership shift directly to how the business plans to manage earnings quality, capital allocation and debt while it works through a US$2.9b backlog and complexity reduction programs.
For you, the question is whether Ezzell's background in FP&A, treasury, investor relations and global supply chain gives Flowserve enough support to keep pushing on cost optimization, digital offerings like RedRaven and disciplined project selection. Execution against that backlog, while managing high leverage and integration risk in FCD, remains the practical catalyst to watch.
Flowserve's current analyst narrative points to revenues of US$5.5b and earnings of US$718.3m by 2029, based on forecast annual top line growth of 5.9% and an increase in earnings from US$354.0m today to that 2029 consensus level. This represents roughly a doubling of profit over the period.
Uncover why Flowserve's fair value indicates a 26% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on Flowserve focuses on tariff and supply chain risk rather than backlog strength. The most pessimistic analysts already pencilled in earnings of about US$709.4 million on US$5.5b of revenue by 2029, based on a lower 15.9x P/E. With the CFO and interim Chief Accounting Officer roles shifting to Brian Ezzell, you may see those pre news assumptions revisited. Use that spread in views as a prompt to test several scenarios instead of anchoring on a single story.
Explore 4 other Flowserve fair value estimates, including one that suggests it could be worth just $73.50.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider going with your own analysis.
- A useful starting point for your Flowserve research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Flowserve. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Flowserve's overall financial health at a glance.
Looking For More Investment Ideas Beyond Flowserve?
If the Flowserve story has you thinking about position sizing, risk and what else could sit alongside it in a portfolio, the Simply Wall St Screener can help you stress test ideas in a structured way.
- If capital preservation is front of mind, consider starting with 11 resilient stocks with low risk scores that combine steadier risk profiles with more resilient fundamentals.
- For investors who want income to play a bigger role, you could scan for 6 dividend fortresses that may better align with a yield focused approach.
- Those hunting for future compounders may want to comb through 15 high quality undiscovered gems that pair solid financials with lower current attention from the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com