
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Ciena (CIEN) Stock Still Looks Pricey As AI Revenue Guidance Rises
Ciena has delivered very strong share gains over the past few years, all while the story around its earnings power has been reshaped by demand for AI-related network infrastructure. The question now is whether the recent price still lines up with what the business earns.
- Over the past 3 years, Ciena has returned more than 7x, which puts a lot of weight on whether current earnings can support that kind of re-rating.
- Recent news around record revenue and higher long-term revenue expectations suggests investors are treating Ciena's profitability and cash generation as increasingly tied to AI-driven network investment, which can matter a lot for how much they are willing to pay for each dollar of earnings.
- Your read on Ciena is one view; the desks covering it have another. See what analysts think Ciena's shares could be worth.
The stock's next move may depend on whether Ciena's current share price is justified by its earnings when viewed through this earnings-focused lens.
If you want to test the same earnings question you are asking of Ciena across other AI infrastructure plays, run the numbers on 60 AI infrastructure stocks.
Has Ciena Run Too Far on Earnings?
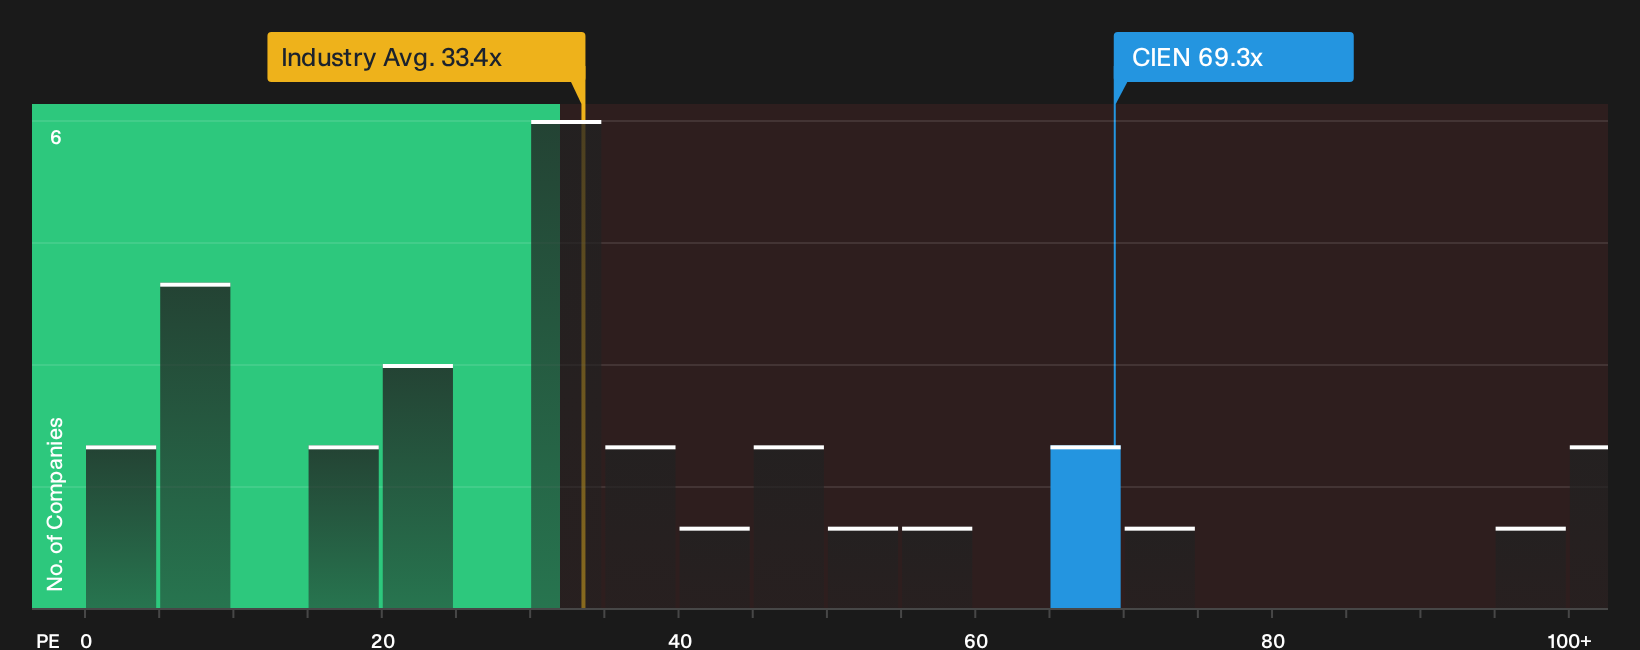
The P/E ratio fits Ciena because the story investors are debating is now very much about earnings power rather than just revenue scale. At roughly 69.3x, Ciena's P/E is well above the Communications industry average of about 33.4x and also ahead of the peer group on roughly 40.6x. This tells you the market is paying a premium price for each dollar of current profit.
That premium screens high relative to the fair P/E level suggested by its own fundamentals and risk profile, so on this yardstick the stock looks overvalued. Despite reporting record Q3 revenue and lifting guidance tied to AI infrastructure, the present multiple already embeds a lot of optimism into the share price. The gap between today's valuation and the earnings level implied by the tailored fair ratio is what the detailed numbers in the next section are designed to unpack. Explore the numbers behind Ciena's P/E valuation.
The Ciena Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Ciena pick up where the valuation question leaves off. They spell out which combinations of future growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than it does today, based on today’s price. Each narrative links a fair value estimate to a specific storyline about Ciena's potential catalysts and key risks so you can track over time which version of events is actually unfolding.
One of the top community narratives on Ciena: 42% undervalued
"Major cloud providers and a new wave of neo-scalers are aggressively investing in high-capacity, low-latency optical networking infrastructure to support AI workloads..."
Discover why this Narrative puts Ciena at 42% undervalued.
One more Ciena check that sits beside the share price
The last missing piece is who is steering Ciena and how their pay lines up with your interests, because leadership incentives can shape how every dollar of profit is chased. See who runs Ciena and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com