
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Raised Guidance At Signet Jewelers (SIG) Has Changed Its Investment Story
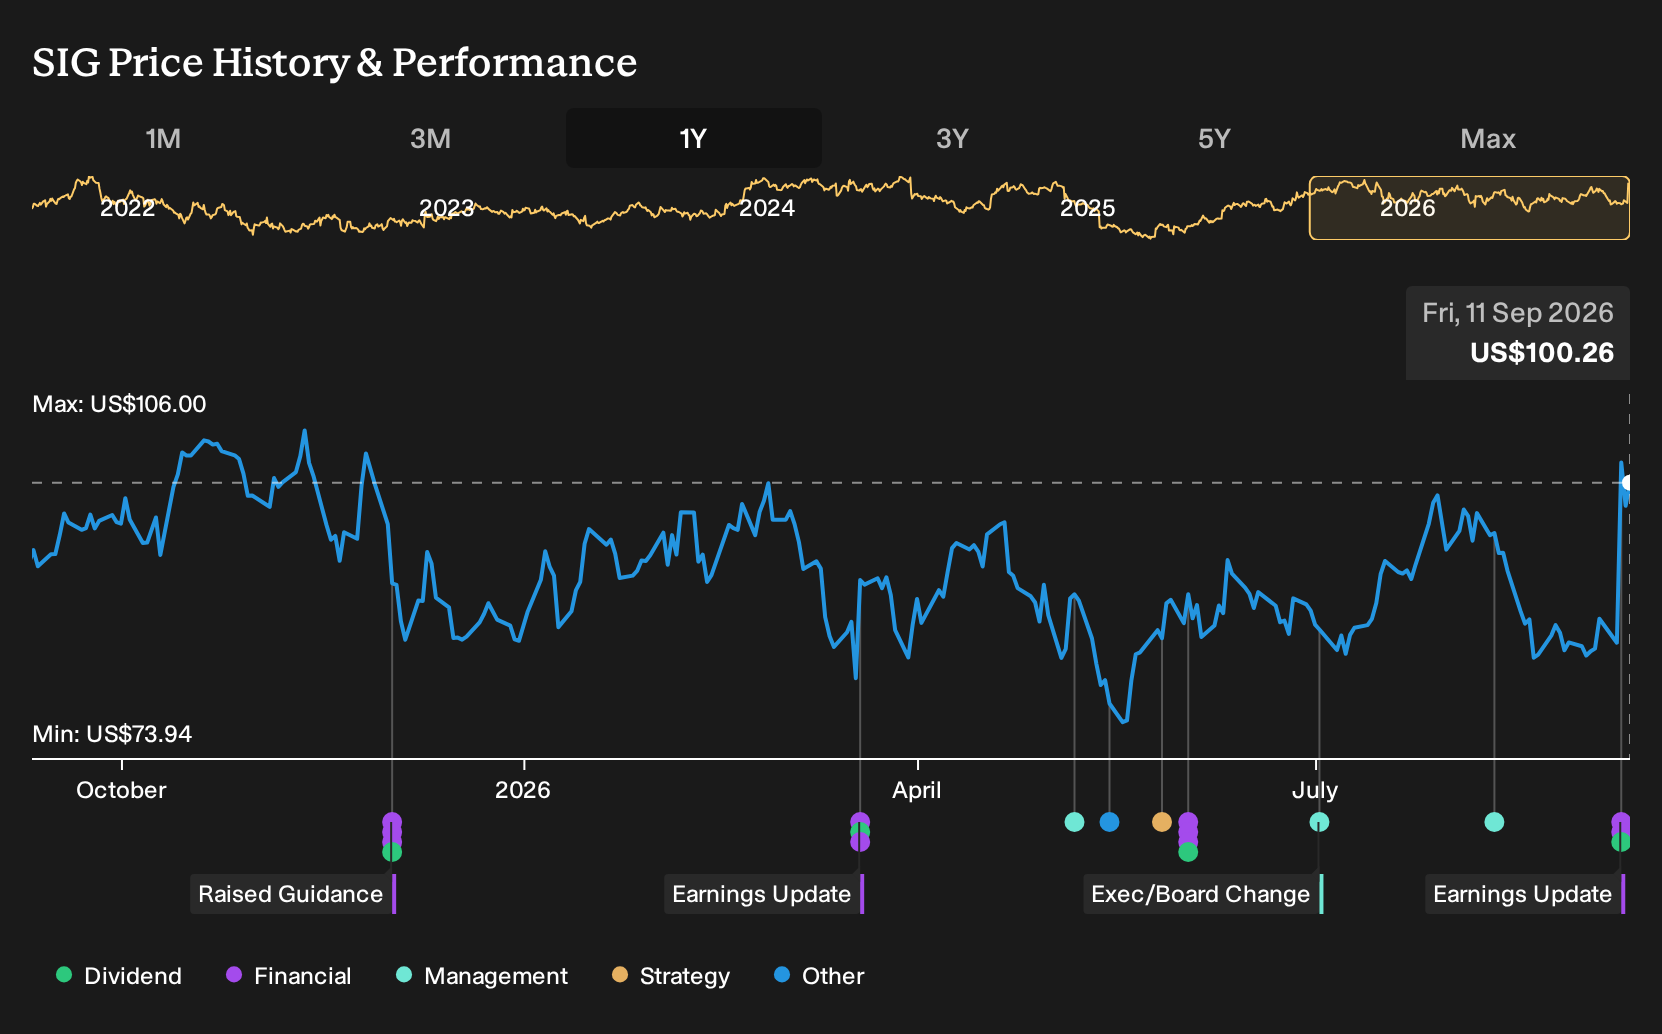
- Signet Jewelers reported Q2 revenue of US$1,528.1 million and net income of US$52.1 million, and confirmed a US$0.35 quarterly dividend along with ongoing share buybacks.
- Management lifted full year fiscal 2027 sales guidance and delivered margin expansion, indicating tighter cost control alongside store closures and brand refresh efforts.
- We will now explore how Signet Jewelers' raised full year outlook reframes the broader investment narrative around profitability and capital returns.
Scan how Signet Jewelers' earnings and buybacks compare with other retailers by reviewing our hand picked list of 35 high quality undervalued stocks.
Signet Jewelers Investment Narrative Recap
For an investor to own Signet Jewelers, the core belief is that the retailer can keep turning a flat to low growth jewelry market into higher profitability through mix, cost discipline and better use of its store base. The Q2 result, with net income of US$52.1 million versus a loss a year earlier, supports that profitability focus without changing the basic story.
The key near term catalyst remains execution on store closures, brand refresh and omnichannel work that supports same store sales and margins. The main risk is that underlying unit demand in bridal and fashion jewelry stays soft, so pricing, lab grown mix and tariffs all become harder to manage without pressuring earnings.
The most relevant fresh data point is Signet Jewelers lifting full year fiscal 2027 sales guidance to US$6.7b to US$6.9b, alongside Q2 revenue of US$1,528.1 million and higher earnings. That update ties directly to the margin story investors are watching, because management is effectively saying the business can support its efficiency push at this new sales range.
Guidance for Q3 sales of US$1.37b to US$1.41b also frames expectations around the store consolidation plan and newer brand platform. If delivery comes in line with that range while tariffs, gold costs and lab grown pricing remain manageable, it would help the current margin expansion narrative. If not, it would highlight how sensitive the model is to modest shifts in demand or costs.
Signet Jewelers' current analyst storyline points to revenues of US$7.1b and earnings of US$470.7 million by 2029. These figures are based on expectations for 1.3% yearly revenue growth and an earnings increase of about US$116.9 million from US$353.8 million today.
Uncover why Signet Jewelers' fair value indicates a 14% potential upside to its current price before the discount closes.
Exploring Other Perspectives
Some of the most optimistic analysts focus on lab grown diamond momentum at Signet Jewelers as a potential accelerator, not just a supporting act. Before this Q2 update, the bullish camp was modeling revenue to reach US$7.2b and earnings of US$512.8 million by 2029. That is far above the more cautious projections and could easily shift again once this new guidance is fully absorbed. Readers like you are looking at the same figures and still reaching very different conclusions, which is exactly why it helps to line up a few alternative narratives side by side.
Explore 3 other Signet Jewelers fair value estimates, including one that suggests up to 108% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Signet Jewelers research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Signet Jewelers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Signet Jewelers' overall financial health at a glance.
Looking For More Ideas Beyond Signet Jewelers?
Once you have a handle on Signet Jewelers, it can help to widen the lens and compare it with other companies that fit different risk, income, and balance sheet profiles.
- For investors who want potential upside with stricter financial filters, consider using the 15 high quality undiscovered gems to surface businesses that combine quality fundamentals with less attention from the market.
- If capital protection and steadier profiles matter most to you, review the 11 resilient stocks with low risk scores to spot companies that screen well on resilience and risk scores.
- For those focused on balance sheet strength as a starting point, sort through the list of solid balance sheet and fundamentals (23 results) to find businesses with fundamentals that may support more durable operations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com