
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
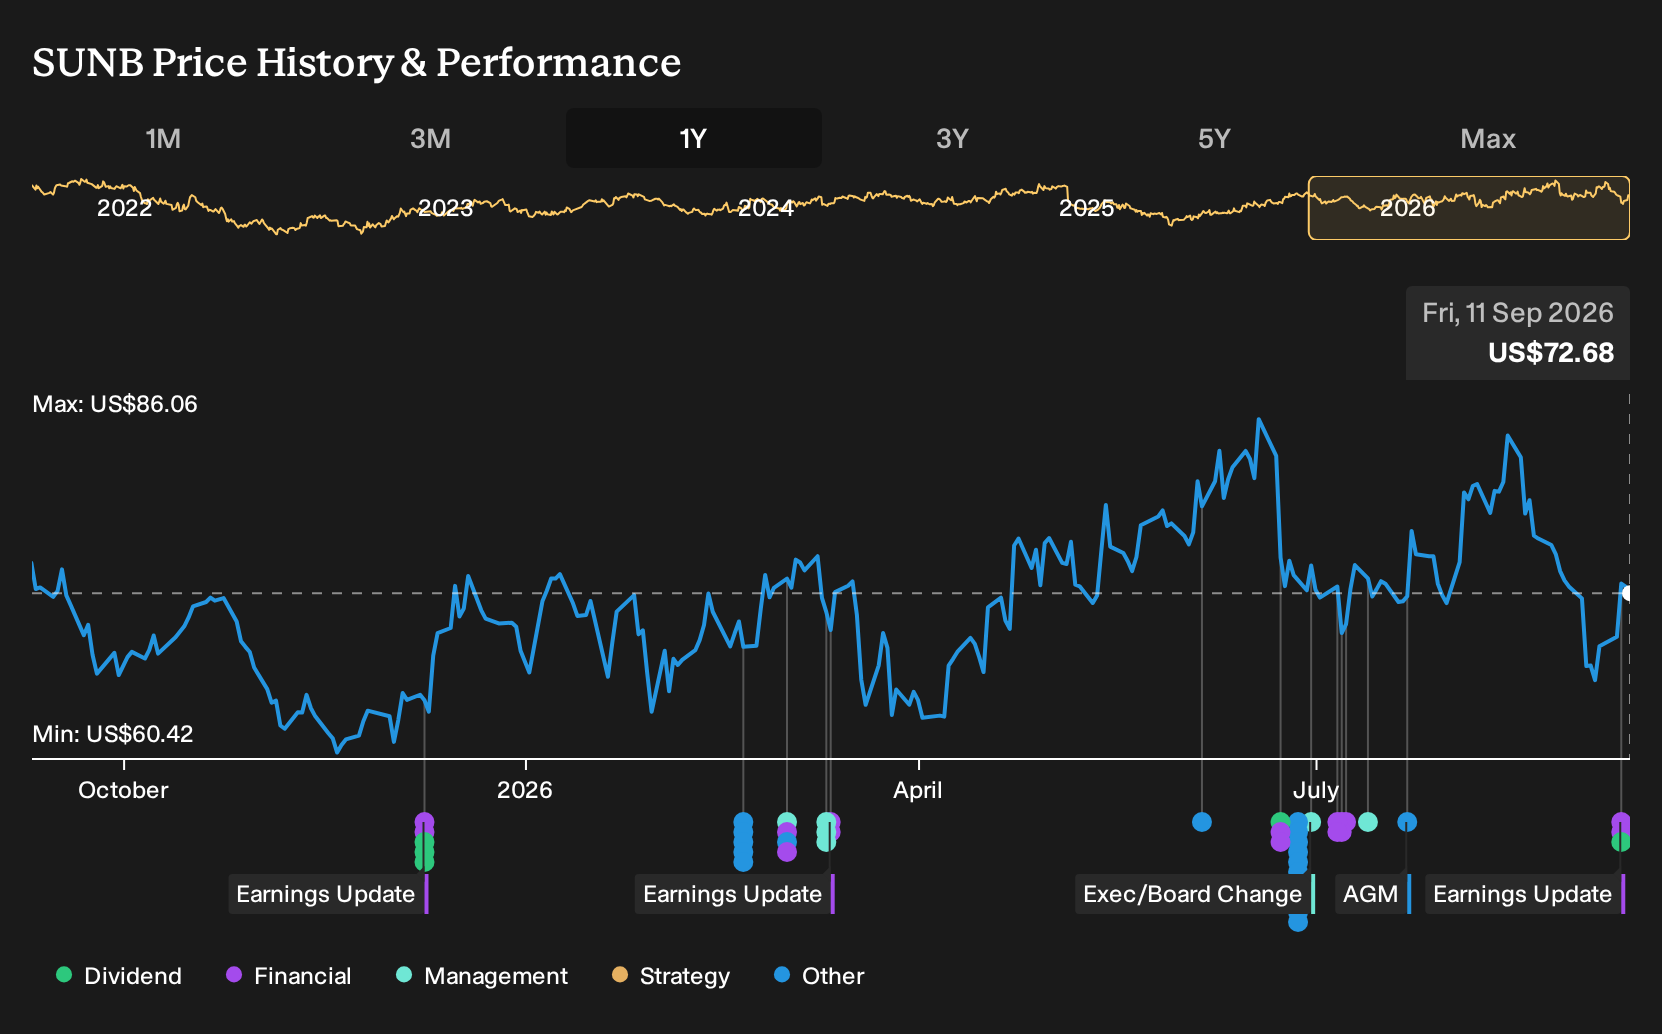
How Investors Are Reacting To Sunbelt Rentals Holdings (SUNB) Raised Revenue Outlook
- Sunbelt Rentals Holdings reported first quarter 2026 results with US$2,927 million in sales, US$3,115 million in revenue and US$438 million in net income, while also completing a US$312.12 million buyback tranche and affirming a new US$0.30 per share quarterly dividend framework.
- The combination of higher earnings per share, an active repurchase program and a shift to regular quarterly dividends indicates management is prioritising shareholder returns while maintaining discipline around cash flow and capital allocation.
- This analysis will review how Sunbelt Rentals Holdings' raised 2027 revenue guidance reframes the existing investment narrative around project driven rental demand.
Scan how Sunbelt Rentals Holdings' buybacks and new dividend framework compare with capital return programs across list of solid balance sheet and fundamentals (23 results).
Sunbelt Rentals Holdings Investment Narrative Recap
To own Sunbelt Rentals Holdings, you need to be comfortable with a rental model that leans on mega projects, local non residential construction and higher return Specialty categories to keep fleets busy and pricing disciplined. The raised 2027 revenue outlook and solid first quarter earnings keep that operating thesis intact. The key near term catalyst is execution on project driven demand and Specialty mix.
The biggest near term risk sits in construction activity slowing or time utilization softening while Sunbelt keeps investing in fleet, greenfields and acquisitions. The latest quarter and guidance update do not remove that exposure. They simply show the business currently has enough volume and rate support to stick with its existing plan.
The shift to a US style quarterly dividend at US$0.30 per share is the most relevant announcement here. It links directly to the raised revenue guidance and completed US$312.12 million buyback, since all three rely on consistent cash generation from the rental network. Together they give you a clearer view of how cash leaves the business.
Sunbelt Rentals Holdings still needs to balance that regular payout with heavy capital needs for fleet, Specialty categories and Sunbelt 4.0 projects. If project pipelines or pricing weaken, the dividend framework could tighten financial flexibility, especially alongside high debt levels. At this stage the move primarily formalises returns rather than changing the core operating catalyst.
Sunbelt Rentals Holdings' current analyst narrative assumes revenue will compound at 6.7% per year, with earnings today of US$1.3b rising to forecast consensus earnings of US$2.0b by 2029. This represents an increase of about US$700m and implies revenues of US$13.5b and earnings of US$2.0b in that forecast year.
Uncover why Sunbelt Rentals Holdings' fair value indicates a 7% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Sunbelt Rentals Holdings focuses less on mega projects and more on local nonresidential construction staying weak for longer. The most optimistic analysts were already pencilling in revenue of about US$14.3b and earnings of US$2.5b by 2029 before this dividend and buyback news. That is a much richer story than consensus. Use this gap as a prompt to explore how your own expectations line up, because these fresh capital return moves could push those narratives in new directions once forecasts are updated.
Explore 2 other Sunbelt Rentals Holdings fair value estimates, including one that suggests as much as 31% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sunbelt Rentals Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sunbelt Rentals Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sunbelt Rentals Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Sunbelt Rentals Holdings?
If the Sunbelt Rentals Holdings story has sharpened your thinking about capital returns and cash generation, you can use that same lens across a wider watchlist. The Simply Wall St Screener can help you quickly filter for companies that fit the kind of balance sheet strength, income profile or risk level you want to focus on next.
- If capital preservation is near the top of your checklist, you can start with companies that screen as more resilient by running the 11 resilient stocks with low risk scores and then see which ones align with your risk tolerance.
- For investors looking for value with quality fundamentals, you can sort through the 35 high quality undervalued stocks and compare how those businesses handle cash flow and reinvestment with what you see at Sunbelt Rentals Holdings.
- If you want a watchlist of sturdier balance sheets, you can use the list of solid balance sheet and fundamentals (23 results) to find businesses that pair financial strength with consistent cash generation that can support dividends and buybacks over time.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com