
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Alcon (SWX:ALC) Could Be 26% Undervalued On UNITY M Launch
Alcon stock reacts to UNITY M surgical microscope launch
Alcon (SWX:ALC) just moved its UNITY platform forward with the commercial launch of UNITY M, a premium ophthalmic surgical microscope now rolling out in the U.S., Japan and other key markets.
That product push comes as Alcon’s share price has been under pressure, with the stock at CHF55.0 and a 30-day share price return of down 9.36%. The 90-day share price return is up 4.72% and the 1-year total shareholder return is down 10.89%, pointing to mixed momentum where recent weakness follows a modest rebound earlier in the year.
Spot similar ophthalmic and medical device plays reacting to new product launches by scanning our hand-picked 616 high quality undiscovered gems. These focus on strong fundamentals and under-followed growth stories.UNITY M reinforces Alcon’s depth in ophthalmic hardware, yet the share price has been weak this year. Is a solid eye care franchise now available at a reasonable valuation, or is it still priced for perfection?
Most Popular Narrative: 26% Undervalued
Alcon’s most followed valuation story points to a fair value of CHF74.01 against a last close of CHF55.00. This setup positions UNITY M and the broader surgical platform as key tests of that upside case.
Accelerated new product launches including Unity VCS, PanOptix Pro, Tryptyr, Precision7, and recent pipeline accretive M&A provide significant near and medium-term opportunities for share gain, mix improvement, and new market entry, underpinning upside to both revenue and net margins as these innovations scale.
See why 24 investors see Alcon as 26% undervalued.
Result: Fair Value of CHF74.01 (UNDERVALUED)
Still, the Alcon story can break if competitive pressure in intraocular lenses persists, or if recent acquisitions deliver weaker returns and slower integration than analysts expect.
Find out about the key risks to this Alcon narrative.
Another View on Alcon’s Valuation
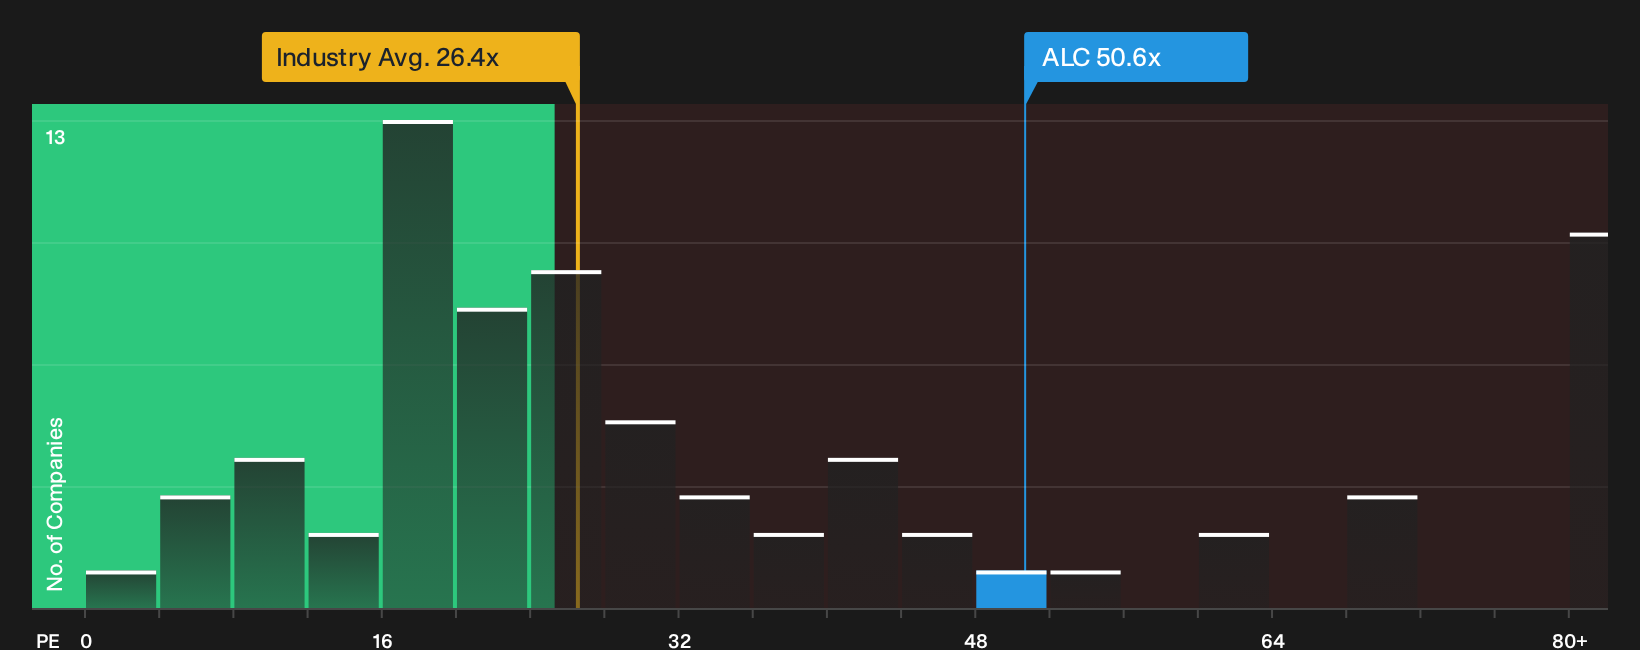
The earlier narrative leans on future earnings and a fair value of CHF74.01 for Alcon. On current numbers, the stock trades on a P/E of 50.6x versus 26.4x for the wider European medical equipment group and a fair ratio of 42x. This points to richer pricing and less margin for error if growth stumbles.
That gap can look like upside if Alcon delivers exactly what the bullish narrative expects, or like compression risk if the market drifts back toward the industry and fair ratio levels. Which side of that trade do you feel more comfortable underwriting?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Alcon’s valuation and product momentum can feel confusing, so move quickly from headlines to hard numbers and shape your own view with the 3 key rewards and 2 important warning signs.
Looking for more Alcon-sized investment ideas?
If Alcon has you thinking about what else might be hiding in plain sight, do not stop here. Some of the most compelling opportunities never make the headlines.
- Target resilient balance sheets and steady fundamentals by scanning our hand picked list of solid balance sheet and fundamentals (194 results) that aim to keep financial risk in check.
- Zero in on potential value opportunities by using the curated 189 high quality undervalued stocks that filters for quality businesses at more modest prices.
- Spot lesser known stories with strong underpinnings through the focused 616 high quality undiscovered gems that many investors might still be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com