
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will $250 Million Notes Offering Change Columbia Bank's (COLB) Narrative
- Columbia Banking System, through Columbia Bank, priced $250 million of 6.721% Fixed-to-Fixed Rate Subordinated Notes due 2036, with the offering having closed in September 2026 subject to customary conditions at the time.
- The bank plans to direct the proceeds toward general corporate purposes, capital adequacy, growth funding, and potentially redeeming up to $250 million of existing trust preferred securities. This approach reshapes how its capital stack is structured rather than simply adding new leverage.
- We will now explore how Columbia Banking System's new 6.721% subordinated notes could influence the existing investment narrative around growth, capital and funding.
Compare how Columbia Banking System is reshaping its funding mix with other banks and financials that are preparing for higher-for-longer rates by scanning our curated list of solid balance sheet and fundamentals (23 results)
Columbia Banking System Investment Narrative Recap
To own Columbia Banking System, you need to be comfortable with a Western U.S. focused lender that is still working through large integrations and a multi year balance sheet remix. The core view is that broader banking, treasury, and wealth services can support steadier earnings, even as loan growth and deposit trends move around.
The new 6.721% subordinated notes mainly fine tune funding. The shift could support the near term catalyst of clean execution on integrations and cost efficiencies by giving management more flexibility. The biggest risk remains regional concentration and funding pressure if deposit competition stays intense or economic conditions weaken locally.
The subordinated notes pricing sits alongside the ongoing Pacific Premier acquisition plan as a key funding decision. Both point to the same operational question: can Columbia Banking System scale its footprint and fee based businesses while keeping capital and funding costs under control as it grows in the Western U.S.?
For catalysts, the combination of a larger franchise and more diversified income only matters if execution risk is contained. Integration expenses, system alignment, and any credit issues in new markets could blunt the benefit of a more efficient capital stack. That is where these new notes intersect most directly with the current story.
Columbia Banking System is currently tracked by analysts who see revenue growing at 6.0% per year, with earnings today of US$709.0 million and a consensus forecast of US$938.7 million by 2029. This implies an earnings increase of about US$229.7 million and supports a narrative that targets US$3.0b of revenue and US$938.7 million of earnings in 2029.
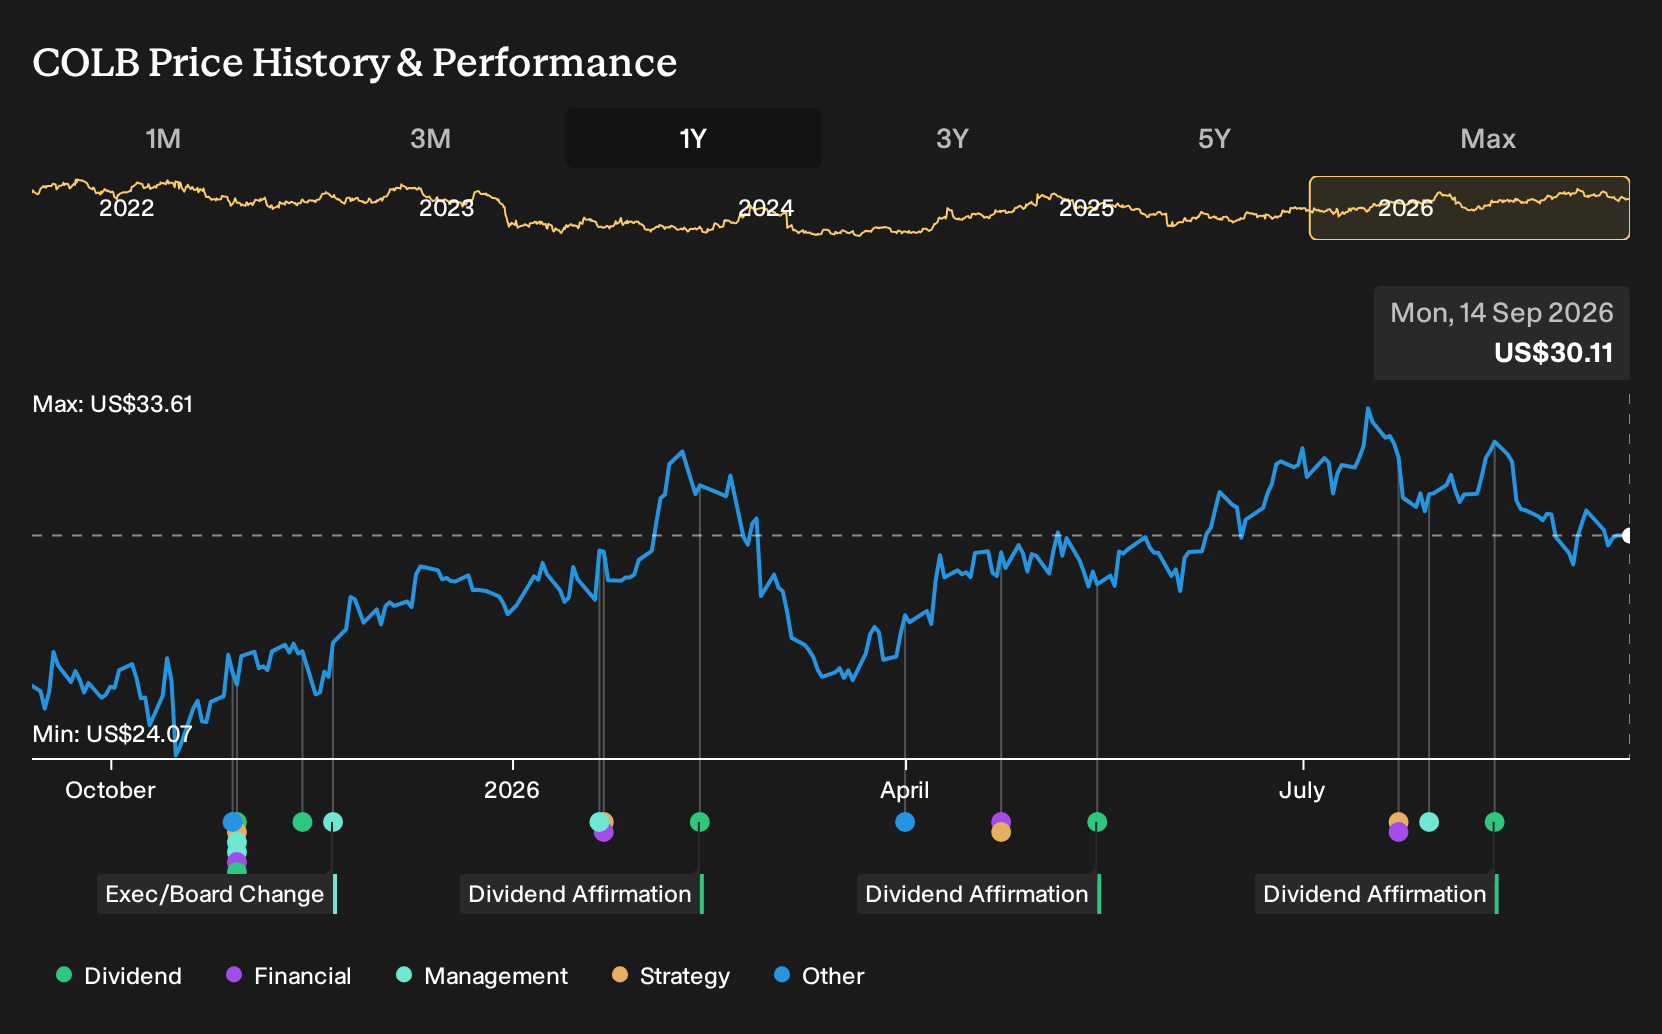
Uncover why Columbia Banking System's fair value indicates a 14% potential upside to its current price before that discount to the market view tightens.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community cluster between US$34.36 and US$51.21, so you see everything from deep discount territory to richer expectations for Columbia Banking System. Those views sit next to real execution questions around Western U.S. concentration and integrations, which could swing future performance sharply in either direction.
Explore 4 other Columbia Banking System fair value estimates, including one that indicates potential upside of up to 70% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A useful starting point for your Columbia Banking System research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Columbia Banking System. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Columbia Banking System's overall financial health at a glance.
Looking for more Columbia Banking System sized ideas?
If the Columbia Banking System story has sharpened your thinking on balance sheets, funding costs, and upside versus risk, you can apply that same lens across a wider watchlist using the Simply Wall St screener tools.
- For investors who want potential value paired with resilient finances, scan a curated set of 35 high quality undervalued stocks that combine quality fundamentals with a margin between price and estimated worth.
- If capital preservation sits high on your priority list, filter for businesses that aim for steadier profiles by focusing on a group of 11 resilient stocks with low risk scores with stronger risk scores.
- When the priority is financial strength over excitement, start with a list of solid balance sheet and fundamentals (23 results) that already screens for robust balance sheets and fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com