
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Asian Market Gems 3 Stocks Possibly Priced Below Intrinsic Value
As Asian markets navigate a complex landscape marked by geopolitical tensions and fluctuating oil prices, investors are increasingly on the lookout for opportunities that may be overlooked in the broader economic narrative. Identifying stocks that are potentially undervalued can offer a strategic advantage, especially when global pressures create discrepancies between market prices and intrinsic values.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Wacom (TSE:6727) | ¥821.00 | ¥1597.92 | 48.6% |
| Thai Vegetable Oil (SET:TVO) | THB26.75 | THB51.97 | 48.5% |
| P.S.P. Specialties (SET:PSP) | THB7.65 | THB14.80 | 48.3% |
| PAL GROUP Holdings (TSE:2726) | ¥1507.00 | ¥2862.46 | 47.4% |
| Niterra (TSE:5334) | ¥7161.00 | ¥13725.77 | 47.8% |
| Innocean Worldwide (KOSE:A214320) | ₩18550.00 | ₩37080.65 | 50% |
| Ichikoh Industries (TSE:7244) | ¥554.00 | ¥1067.62 | 48.1% |
| BuySell TechnologiesLtd (TSE:7685) | ¥2880.00 | ¥5565.38 | 48.3% |
| AK Medical Holdings (SEHK:1789) | HK$4.91 | HK$9.60 | 48.9% |
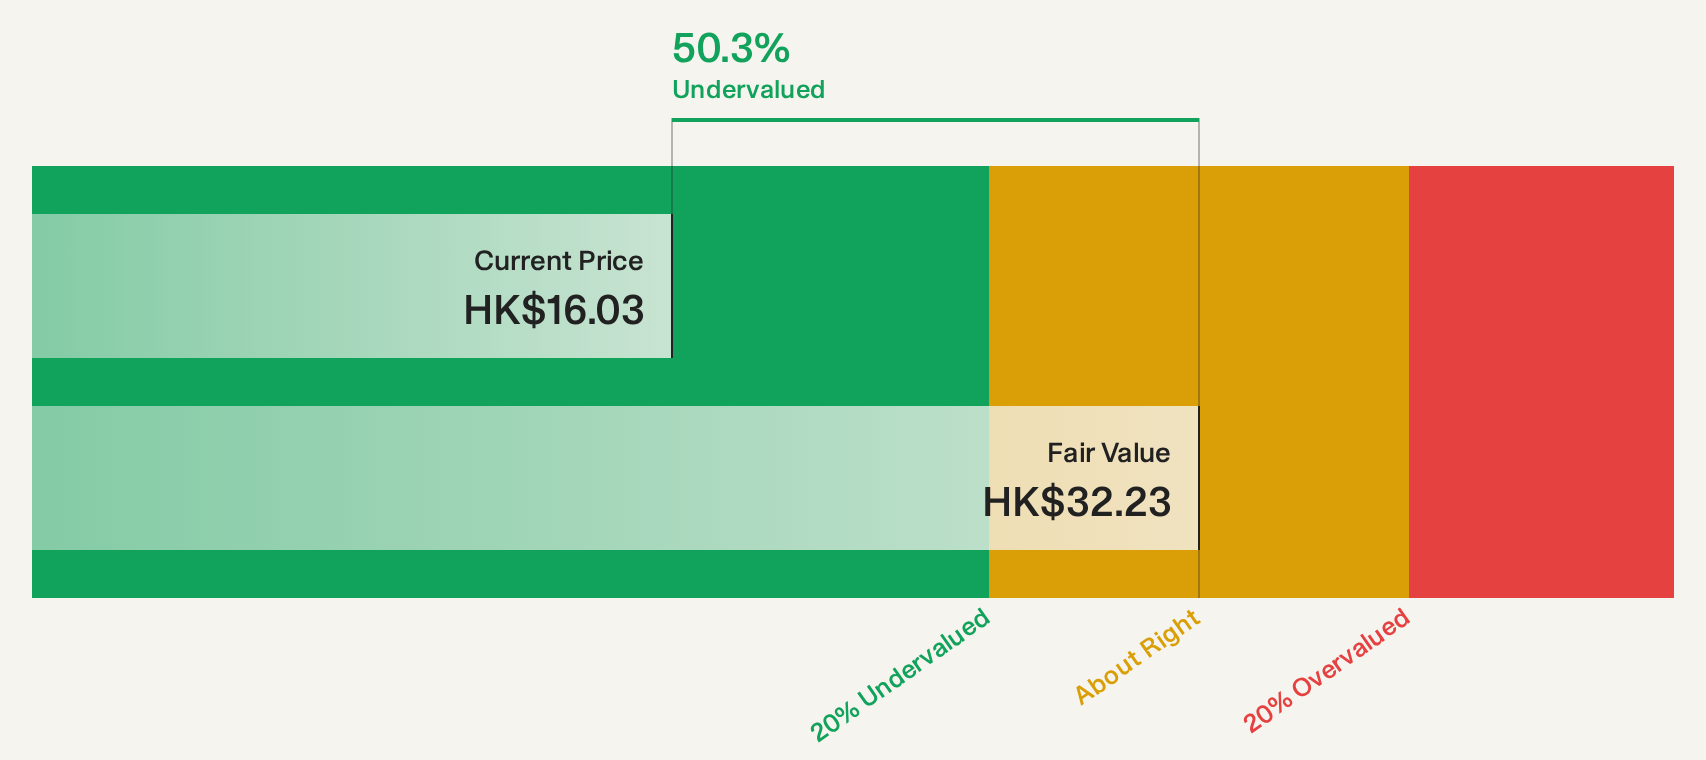
| 3SBio (SEHK:1530) | HK$16.22 | HK$32.25 | 49.7% |
Underneath we present a selection of stocks filtered out by our screen.
3SBio (SEHK:1530)
Overview: 3SBio Inc. is an investment holding company that develops, produces, markets, and sells biopharmaceutical products in China, the United States, and internationally with a market cap of HK$40.42 billion.
Operations: The company generates revenue of CN¥17.87 billion from its involvement in the development, production, marketing, and sale of biopharmaceutical products.
Estimated Discount To Fair Value: 49.7%
3SBio is trading at HK$16.22, significantly below its estimated fair value of HK$32.25, indicating potential undervaluation based on discounted cash flows. Despite a recent 250.7% growth in earnings, future projections suggest declines in both revenue and earnings over the next three years by 16.6% and 40.7%, respectively. Recent share buybacks aim to enhance net asset value and earnings per share, but declining forecasts may temper investor enthusiasm despite current valuation metrics suggesting good relative value compared to peers.
- According our earnings growth report, there's an indication that 3SBio might be ready to expand.
- Click here to discover the nuances of 3SBio with our detailed financial health report.
Henan Mingtai Al.IndustrialLtd (SHSE:601677)
Overview: Henan Mingtai Al.Industrial Co., Ltd. is involved in the production and sale of aluminum products in China, with a market capitalization of CN¥20.51 billion.
Operations: The company's revenue is primarily derived from its aluminum product sales in China.
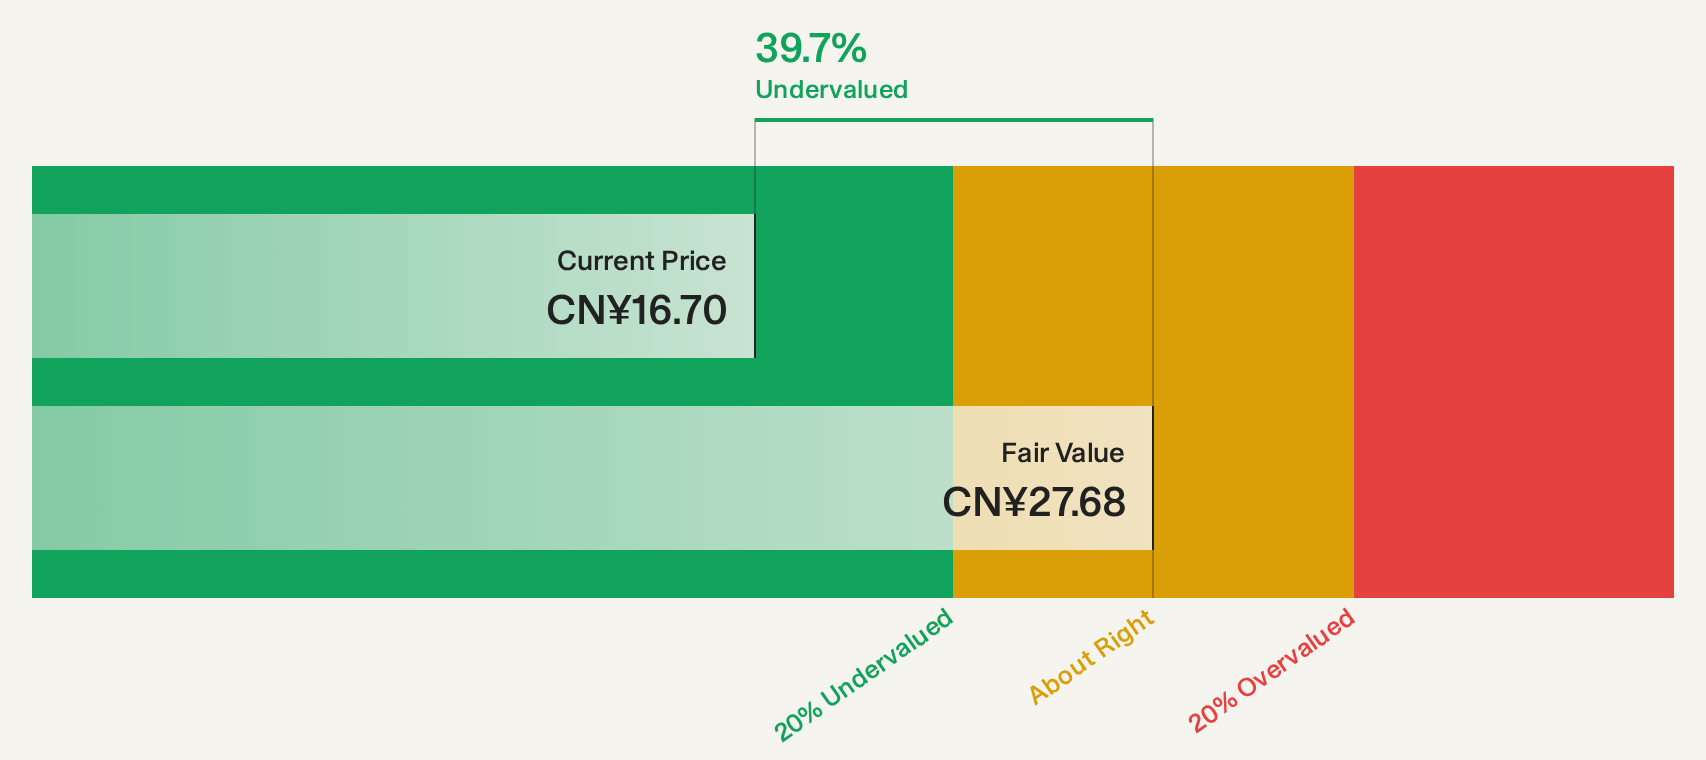
Estimated Discount To Fair Value: 40.3%
Henan Mingtai Al.Industrial Ltd. is trading at CNY 16.49, well below its estimated future cash flow value of CNY 27.62, highlighting potential undervaluation based on discounted cash flows. Recent earnings reports show a robust increase in net income to CNY 1,406.76 million from CNY 940.25 million year-over-year, yet forecasted annual profit and revenue growth remain modest compared to the broader Chinese market, with anticipated figures of 3.4% and 6.3%, respectively.
- Our growth report here indicates Henan Mingtai Al.IndustrialLtd may be poised for an improving outlook.
- Delve into the full analysis health report here for a deeper understanding of Henan Mingtai Al.IndustrialLtd.
Pharmaron Beijing (SZSE:300759)
Overview: Pharmaron Beijing Co., Ltd. operates as a pharmaceutical research and development service platform across North America, Europe, Mainland China, Asia, and internationally with a market cap of CN¥72.02 billion.
Operations: Pharmaron Beijing Co., Ltd. generates revenue through its pharmaceutical research and development service platform, serving markets in North America, Europe, Mainland China, Asia, and internationally.
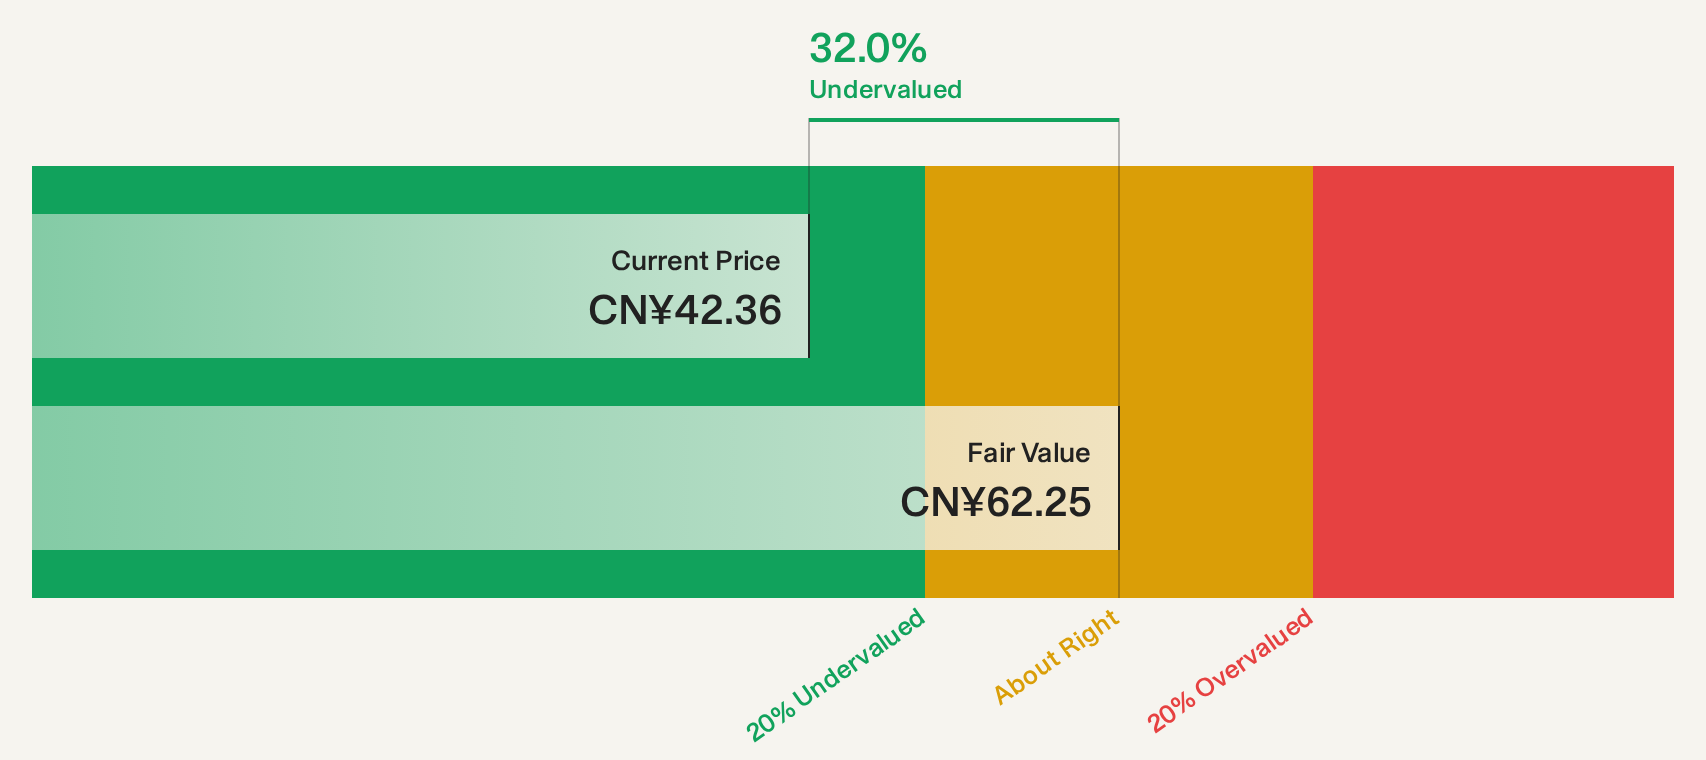
Estimated Discount To Fair Value: 31.7%
Pharmaron Beijing is trading at CN¥42.65, significantly below its estimated future cash flow value of CN¥62.42, suggesting undervaluation based on discounted cash flows. Despite a volatile share price recently, the company reported earnings growth to CN¥750.19 million from CN¥701.4 million year-over-year and forecasts a 26.48% annual profit increase over three years, although this lags behind the broader Chinese market's expected growth rate of 27%.
- Upon reviewing our latest growth report, Pharmaron Beijing's projected financial performance appears quite optimistic.
- Take a closer look at Pharmaron Beijing's balance sheet health here in our report.
Make It Happen
- Discover the full array of 82 Undervalued Asian Stocks Based On Cash Flows right here.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com