
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Avnet (AVT) Cheap On Its Pullback Or Already Fairly Valued?
Avnet (AVT) is back on investor radar after featuring in a Zacks screen of PEG value stocks that combine relatively low valuations with earnings growth expectations, drawing fresh attention to the distributor’s fundamentals.
At around US$92.34 a share, Avnet has seen a sharp 1-day share price decline of 7.32%, even though its year-to-date share price return of 87.15% and 5-year total shareholder return of 184.56% point to strong past momentum that now looks to be cooling in the very short term.
Scan beyond Avnet and review a curated group of value-focused opportunities screened on earnings power and balance-sheet quality with the 32 high quality undervalued stocks.
Avnet has a long operating history and broad global reach, yet the latest share price drop raises a different question. Is a solid electronics distributor now being offered at a reasonable tag, or has the rerating already happened?
Most Popular Narrative: 7% Undervalued
Avnet’s most followed valuation narrative points to a fair value of $99.50, which sits above the last close at $92.34 and frames the current pullback as a potential gap between price and modeled worth.
With improving book-to-bill ratios, a stabilizing inventory environment, and a strong commitment to operational efficiency (cost control and optimized capital allocation), Avnet is positioned to translate industry tailwinds into higher earnings and cash flow, which may support future shareholder returns through buybacks/dividends and potential multiple expansion.
See why 9 investors see Avnet as 7% undervalued.
Result: Fair Value of $99.50 (UNDERVALUED)
Still, the bullish Avnet narrative leans heavily on Asia driven growth and margin recovery, and both could stumble if regional mix shifts and inventory risks intensify.
Find out about the key risks to this Avnet narrative.
Another View On Avnet’s Valuation
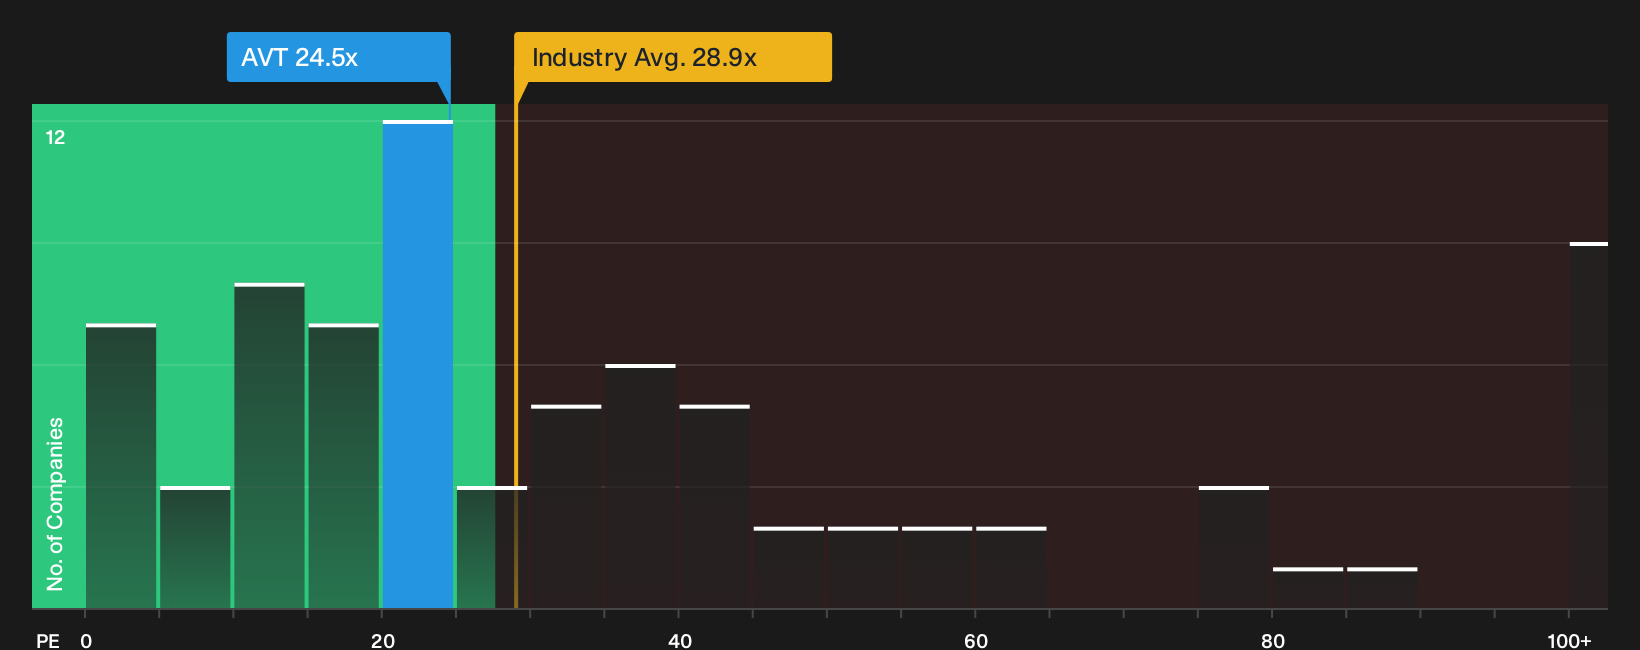
The earlier narrative leans on a fair value of $99.50 based on long term earnings expectations. A different lens uses Avnet’s current P/E of 24.5x, which screens as expensive versus peers at 17.5x, yet still below the US Electronic industry on 28.9x and the fair ratio of 42.2x. That mix hints at both valuation risk against peers and possible upside if the market ever moves closer to the higher fair ratio. The key question is which part of that trade off matters more to you.
For a closer look at how this earnings multiple stacks up in practice, review the valuation breakdown with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and caution around Avnet feels familiar, move quickly to review the numbers yourself, then consider both sides with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Avnet?
Do not stop your research with Avnet. Broaden your playbook with other potential opportunities filtered by quality, income, and downside protection using the Simply Wall St Screener.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (23 results) that can help anchor the risk side of your portfolio.
- Hunt for mispriced quality by reviewing a focused 32 high quality undervalued stocks built to highlight businesses where fundamentals and valuation may not fully line up.
- Prioritise stability and defensive characteristics by checking 11 resilient stocks with low risk scores so you are not the one wishing you had acted when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com