
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Qorvo (QRVO) Gains Momentum As Its IoT Story Meets A Pricey Valuation
Qorvo (QRVO) has drawn fresh attention after recent share gains over the past month and past three months, with the price closing at US$116.65 and year-to-date performance in focus.
The recent 1-month share price return of 18.9% and 90-day gain of 20.8% suggest momentum in Qorvo is building, although the 5-year total shareholder return is down 31.4%. This keeps the longer-term picture more mixed.
Spot fresh momentum in Qorvo, and then size it up against other potential breakouts in our hand picked list of 32 high quality undervalued stocks.Bulls point to Qorvo’s fresh share momentum and recent profit growth. Bears highlight the weaker 5 year return and valuation concerns. Which side do the current numbers support as you consider what the stock may be worth?
Most Popular Narrative: 28% Overvalued
Qorvo last closed at $116.65, while the most followed narrative anchors fair value around $91.46, implying the shares trade well ahead of that framework and putting execution of the long term story under the spotlight.
The proliferation of connected devices in automotive, industrial, and consumer IoT, shown by new automotive ultra-wideband wins, AR/VR design victories, and enterprise network content gains, positions Qorvo to capture growing semiconductor demand and diversify revenue streams, reducing dependence on cyclical end-markets and smoothing earnings.
See why 18 investors see Qorvo as 28% overvalued.
The narrative assumptions use a discount rate of about 12.0% and build toward revenue of roughly $4.0b and earnings of $597.6m by 2029, paired with an earnings multiple of 16.2x. That construct lands at a fair value of $91.46, which sits well below both the recent close and the current analyst price target of $90.17, so the story being priced in by the market is richer than the one implied by this model.
Against that backdrop, the current P/E of 25.8x, the fair value multiple of about 16x in the narrative, and the Simply Wall St estimate that Qorvo trades above an $87.66 future cash flow value all point to investors paying up for earnings quality, recent 395.8% profit growth, and the potential from IoT and defense exposure while accepting risks around handset demand, customer concentration and slower forecast revenue growth of 1.3% per year.
Result: Fair Value of $91.46 (OVERVALUED)
Still, Qorvo’s heavy reliance on a single customer and the shift away from low margin Android 5G could unsettle revenue and challenge the current valuation narrative.
Find out about the key risks to this Qorvo narrative.
Another View: What Qorvo’s P/E Is Really Saying
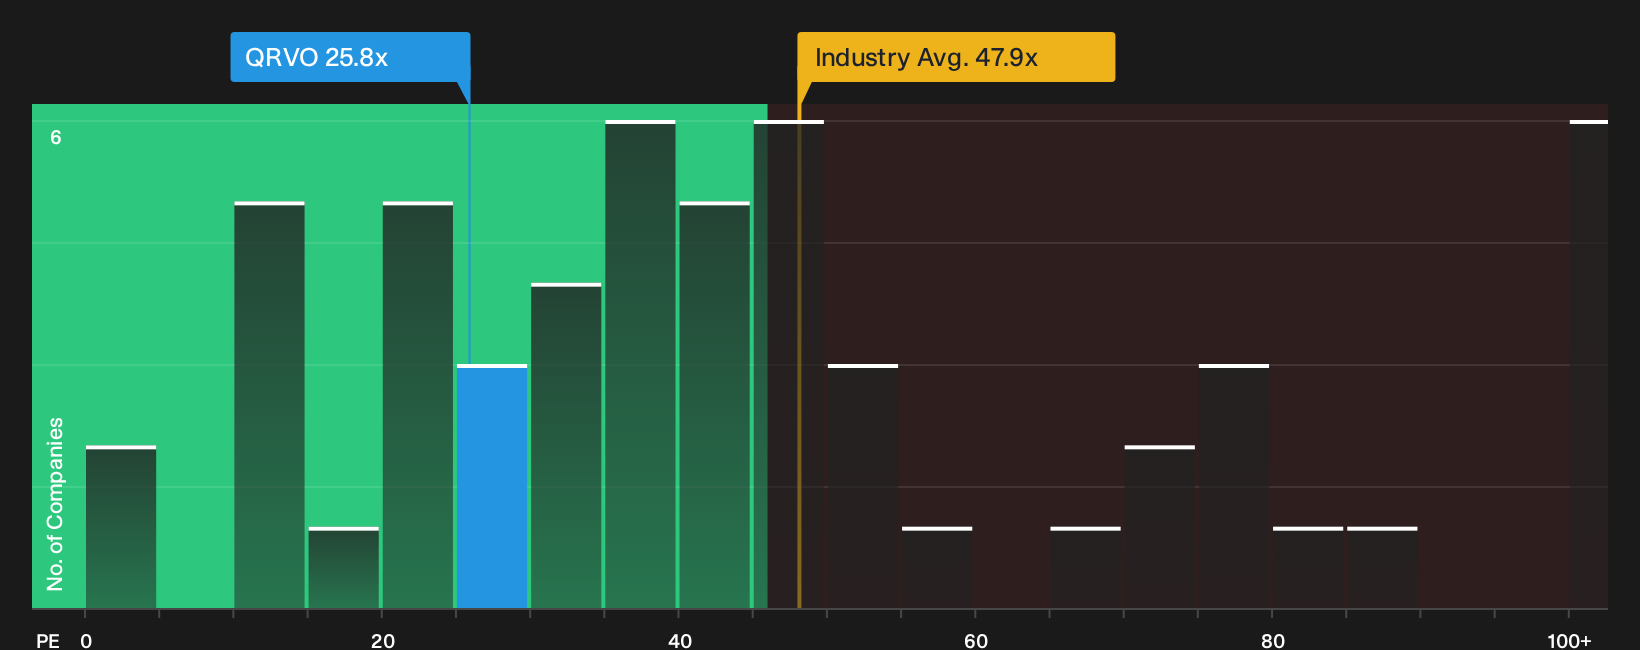
The first narrative flags Qorvo as overvalued, yet the current P/E of 25.8x tells a different story. It sits well below the US Semiconductor industry on 47.9x and under the peer average of 33.1x, but above a fair ratio of 21.9x. That gap suggests investors are paying something for quality and momentum, while still leaving a margin where expectations could reset. Which side of that trade-off you consider more important may depend on your own time horizon.
See what the numbers say about this price in our valuation breakdown, then test whether your assumptions line up with the fair ratio path the market could move toward over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Qorvo’s valuation and risk reward profile are clear. Move quickly, review the underlying data, and pressure test your own thesis with 3 key rewards and 1 important warning sign
Looking for more Qorvo-sized investment ideas?
If Qorvo has you thinking harder about valuation, momentum and risk, do not stop here. Broaden your watchlist with focused ideas built directly from the Simply Wall St Screener and avoid missing opportunities sitting in plain sight.
- Target stronger income potential by reviewing a shortlist of resilient payers in the 6 dividend fortresses.
- Strengthen your downside protection with the 11 resilient stocks with low risk scores, which filters for companies with more robust risk profiles.
- Hunt for potential future market leaders early by scanning the 15 high quality undiscovered gems and spotting quality businesses before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com