
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
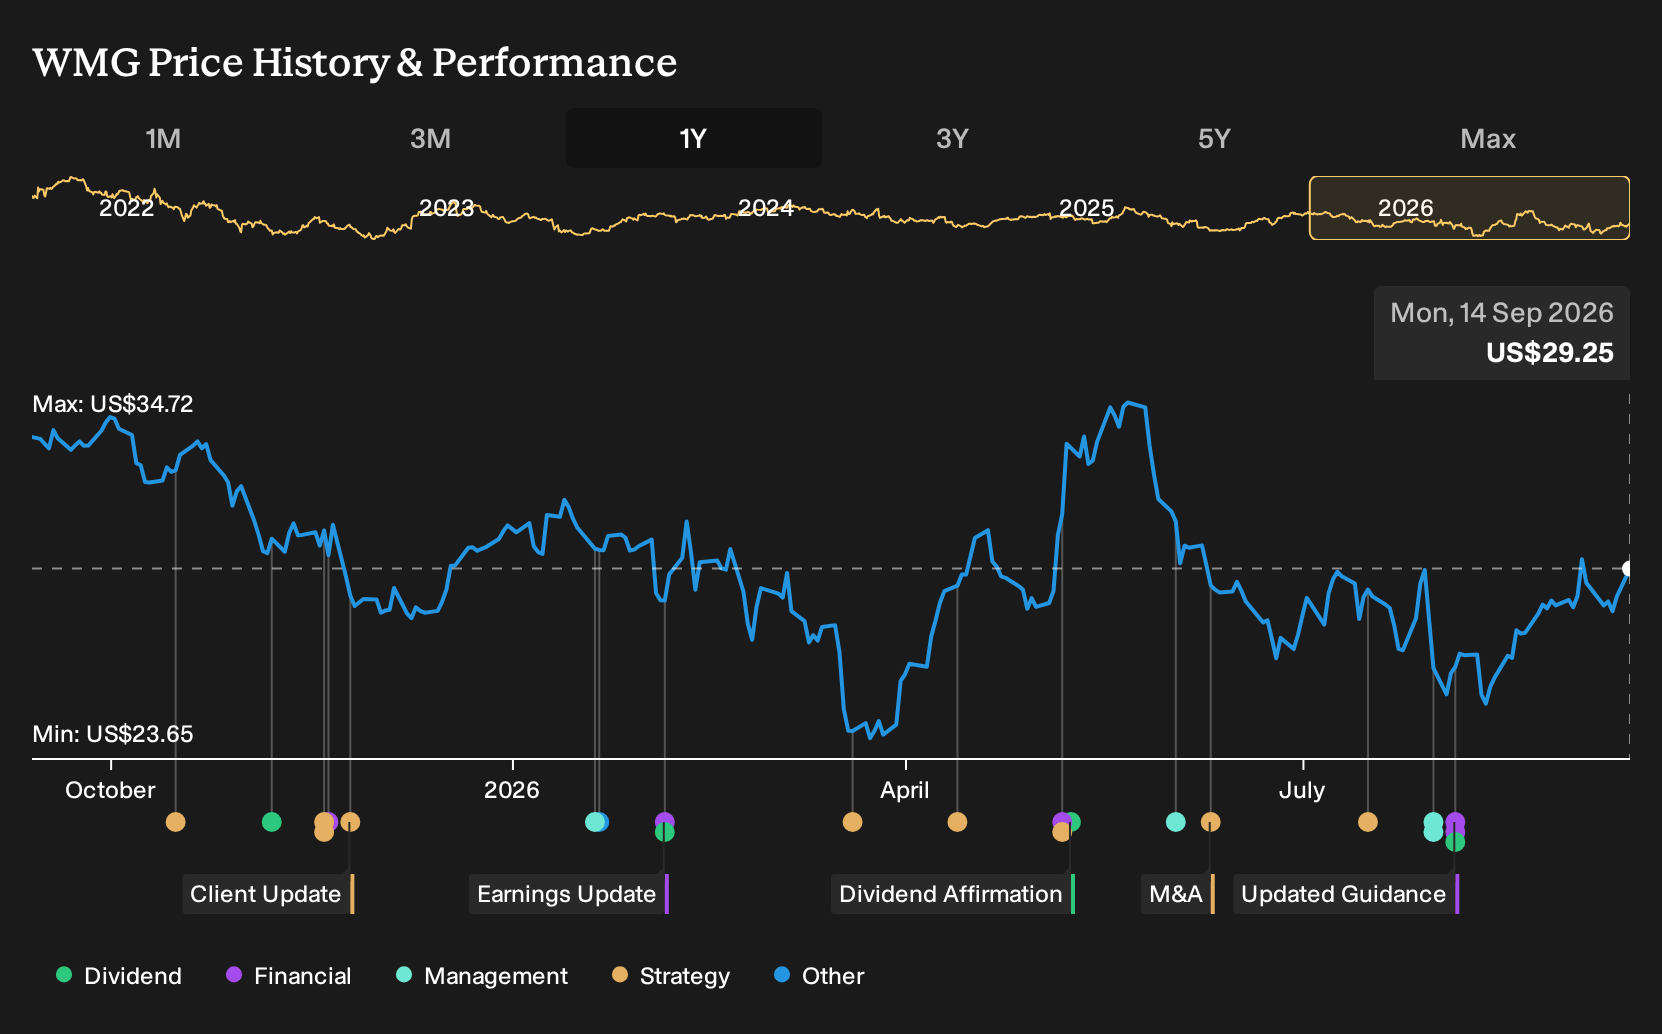
Did Slowing Cash Generation Just Shift Warner Music's (WMG) Investment Narrative?
- Warner Music Group is facing muted 7.7% annual revenue growth over the last five years, combined with flat free cash flow margin expectations and weaker returns on capital.
- The squeeze on cash generation and capital efficiency suggests Warner Music Group’s famous catalog is not translating into strong incremental returns on new investment.
- We will now look at how Warner Music Group's investment narrative is challenged by weak returns on capital and softer growth.
Warner Music Group Investment Narrative Recap
To own Warner Music Group, you need to believe its huge catalog and artist development engine can translate into healthier cash generation over time. Recent data points in the opposite direction. Revenue is growing at 7.7% a year, but free cash flow margins look stuck and returns on capital are weakening, so the short term focus stays on execution rather than expansion.
The key near term swing factor is whether management can turn heavier A&R and catalog spending into steadier operating cash flow without leaning harder on debt. The biggest risk is that cash generation remains tight just as Warner Music Group steps up catalog deals and restructurings, which would keep financial flexibility under pressure.
With no fresh company announcements tied directly to this slowdown in returns, the most relevant reference point is still Warner Music Group's existing plan to deliver US$300 million in annualized cost savings by 2027. That program is meant to support margins, yet the recent cash squeeze suggests the benefits are not clearly visible in free cash flow yet.
For you as a shareholder, the execution question is simple: Can Warner Music Group push through its reorganization, keep investing in artists and catalogs, and still improve coverage of debt and the dividend from internal cash generation? If net profit continues to look cleaner than cash because of one off items and heavy investment, the stock remains closely tied to how credibly management delivers on that efficiency story.
Warner Music Group's current analyst story points to US$8.5b in revenue and US$943.5m in earnings by 2029, based on 5.0% yearly revenue growth. That outlook implies an earnings increase of about US$278.5m from US$665.0m today.
Uncover why Warner Music Group's fair value indicates a 30% potential upside to its current price, which could narrow faster than many investors expect.
Exploring Other Perspectives
One alternate view on Warner Music Group focuses on AI related risk. The most cautious analysts worry that tools from partners like Suno and Udio could pull listening toward content that uses less Warner controlled IP. Before this news, that group was only penciling in about US$8.4b of revenue and US$993.6m of earnings by 2029, which is far more conservative than the consensus path. Those projections were set without today’s developments, so it is possible that both the upbeat and bearish narratives will change as the impact becomes clearer.
Explore 2 other Warner Music Group fair value estimates, including one that suggests it could be worth just $36.88!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Warner Music Group research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Warner Music Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Warner Music Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Warner Music Group?
If Warner Music Group leaves you questioning concentration risk, it can help to widen your opportunity set using the Simply Wall St Screener. You can filter for different types of businesses that better match your tolerance for volatility, income needs, or focus on balance sheet strength.
- For steadier sleep at night, filter for companies with stronger financial resilience and lower risk profiles via the 11 resilient stocks with low risk scores.
- If income is your priority, target companies that offer higher yields with more durable payouts by checking the 6 dividend fortresses.
- To hunt for lesser known opportunities with solid fundamentals, scan the 15 high quality undiscovered gems and see what the market might be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com