
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Capital Raising Require Action From ICBC Shares Investors?
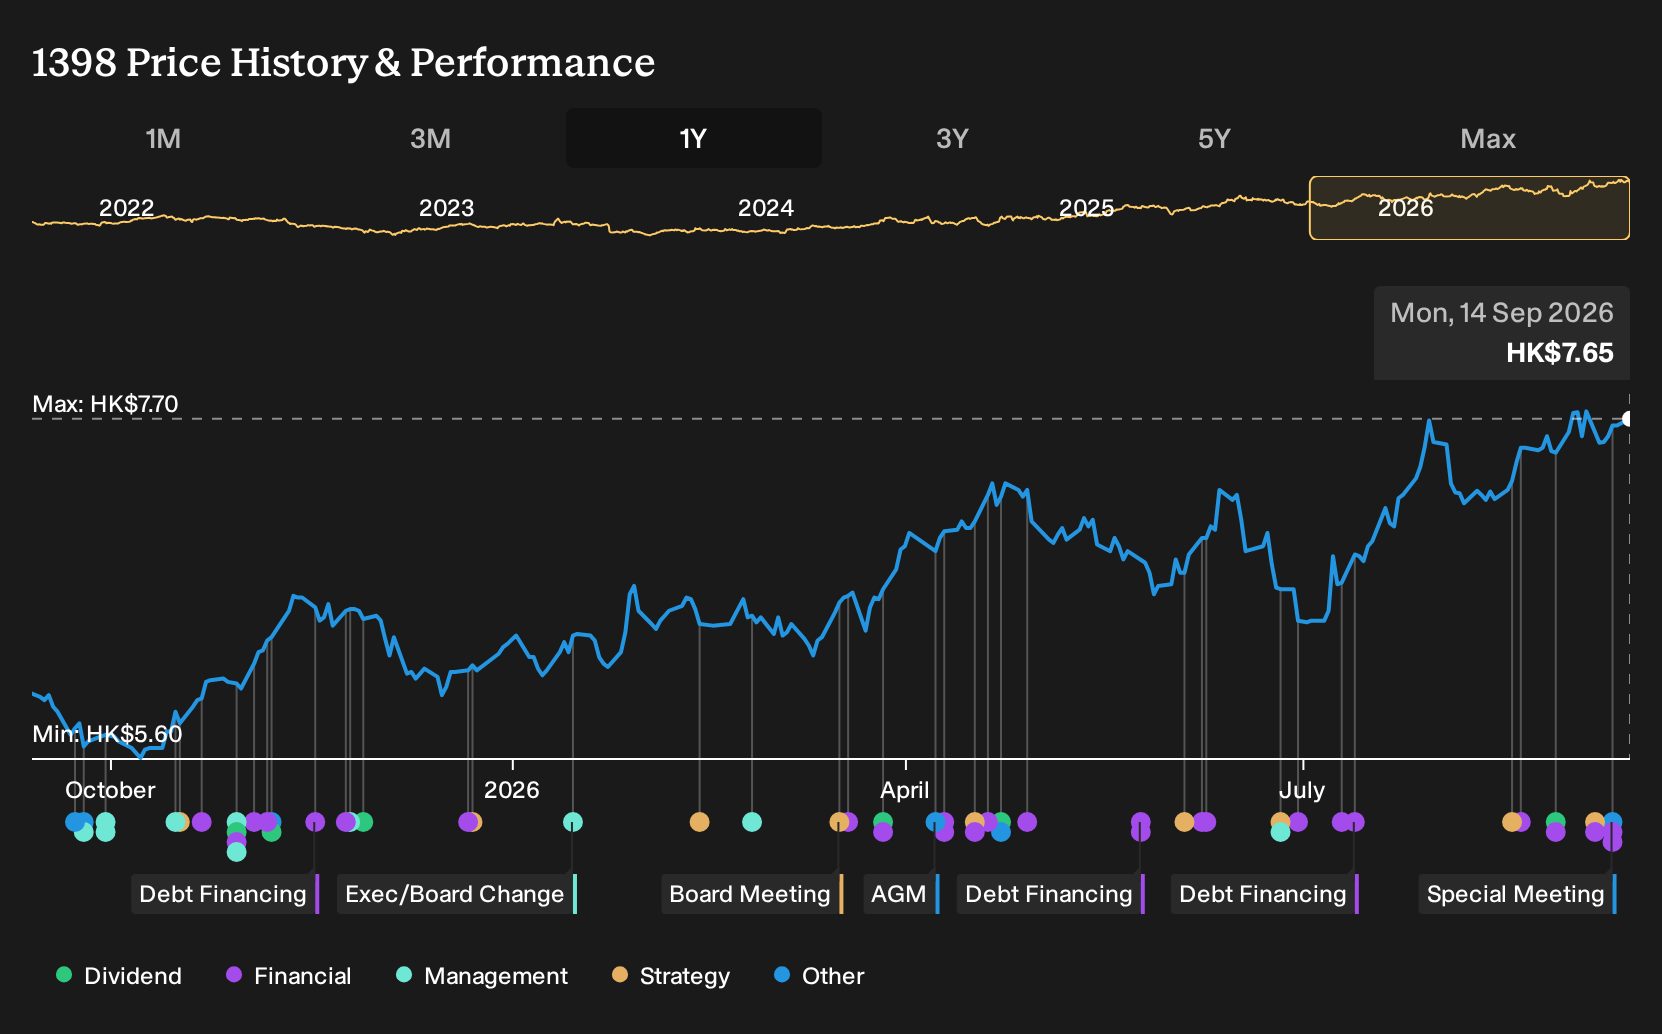
- Industrial and Commercial Bank of China recently completed a RMB 20b undated Additional Tier 1 bond issue at a 1.86% initial distribution rate, while its board approved a private placement plan of up to RMB 100b in A shares to specified investors, subject to further regulatory and shareholder approvals.
- The planned equity injection, with large intended subscriptions from the Ministry of Finance and major tobacco groups, points to strong state linked backing for ICBC’s capital plan and highlights how regulatory requirements and balance sheet strength are shaping the bank’s funding choices.
- This development raises the question of how ICBC’s fresh Additional Tier 1 issuance could influence its capital focused investment narrative for long term investors.
Industrial and Commercial Bank of China Investment Narrative Recap
To own Industrial and Commercial Bank of China, you need to be comfortable with a large, policy aligned lender that leans on scale, digital roll out and fee income to offset pressure on net interest margins. The near term story still turns on how well it can hold asset quality and returns while supporting government priorities across green, inclusive and technology finance.
The fresh Additional Tier 1 issue and planned A share placement mainly address the long running need to keep capital ratios resilient under tighter regulation. This funding mix may ease near term capital pressure, although it does not remove key risks around margin compression, domestic concentration and rising technology and fintech related costs.
The proposed A share private placement of up to RMB 100b, with large intended subscriptions from the Ministry of Finance and tobacco groups, is the clearest companion to this new Additional Tier 1 bond. Together, they point to a balance sheet that is being prepared for ongoing support of policy driven lending while still funding digital, wealth and cross border initiatives.
For you as a shareholder, that matters to the catalyst that many watch most closely, which is ICBC’s ability to keep growing fee and commission income while managing tighter returns on equity. A stronger capital stack can support that execution, although frequent capital raising and policy alignment remain important ongoing risks for per share earnings and dividend flexibility.
Industrial and Commercial Bank of China is framed around analyst projections that revenue could reach CN¥1,033.7b and earnings CN¥414.5b by 2029, based on an assumed 15.4% yearly increase in revenue and an earnings rise of about CN¥54.9b from CN¥359.6b today.
Uncover how Industrial and Commercial Bank of China's fair value indicates a 9% potential upside to its current price, while that discount still feels within reach for long term holders.
Exploring Other Perspectives
One alternate view puts ICBC’s capital strength itself in the spotlight. The most optimistic analysts were already pencilling in CN¥1,072.2b of revenue and CN¥428.0b of earnings by 2029, before this fresh capital raise. You might see this new Additional Tier 1 issue as a reason those projections could shift, in either direction.
Explore 4 other Industrial and Commercial Bank of China fair value estimates, including one that suggests as much as 123% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Industrial and Commercial Bank of China research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Industrial and Commercial Bank of China. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Industrial and Commercial Bank of China's overall financial health at a glance.
Looking For More Ideas Beyond Industrial and Commercial Bank of China?
If you want to cross check the Industrial and Commercial Bank of China story against other opportunities, the Simply Wall St Screener can help you quickly surface stocks with balance sheets, income profiles and risk levels that match what you are looking for.
- For investors who care most about financial resilience and debt capacity, start with a list of solid balance sheet and fundamentals (194 results) that can handle tougher conditions without stretching the balance sheet.
- If you are hunting for potential mispricing, take a look at companies in the 188 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect them yet.
- Income focused investors can scan for yield opportunities with the 162 dividend fortresses that screens for payout levels above 5% supported by relatively stable profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com