
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Karman Holdings (KRMN) Stock Still Looks Expensive On Its 54% Slump
Karman Holdings has seen its share price fall sharply this year, which naturally puts a spotlight on whether the current valuation still lines up with what its earnings can support. With the stock now well below where it started the year, investors are increasingly asking if the recent move reflects a reset in expectations or an overreaction to near term concerns.
- The share price is down 54.1% year to date, which raises the question of whether the current earnings profile fully explains such a steep reset in market value.
- Karman's recent acquisition of Walker Precision Engineering may support future revenue and profit opportunities, but it can also reshape how investors think about the timing and durability of the group’s earnings base.
- There is a second opinion on Karman Holdings worth weighing. See what analysts think Karman Holdings's shares could be worth.
The issue now is whether Karman Holdings' current share price is appropriately reflecting what its earnings justify today.
If you are weighing whether Karman Holdings’ earnings can really support this kind of share price reset, it can help to compare it with other listed businesses screened for 32 high quality undervalued stocks
Does Karman Holdings Look Pricey on Earnings?
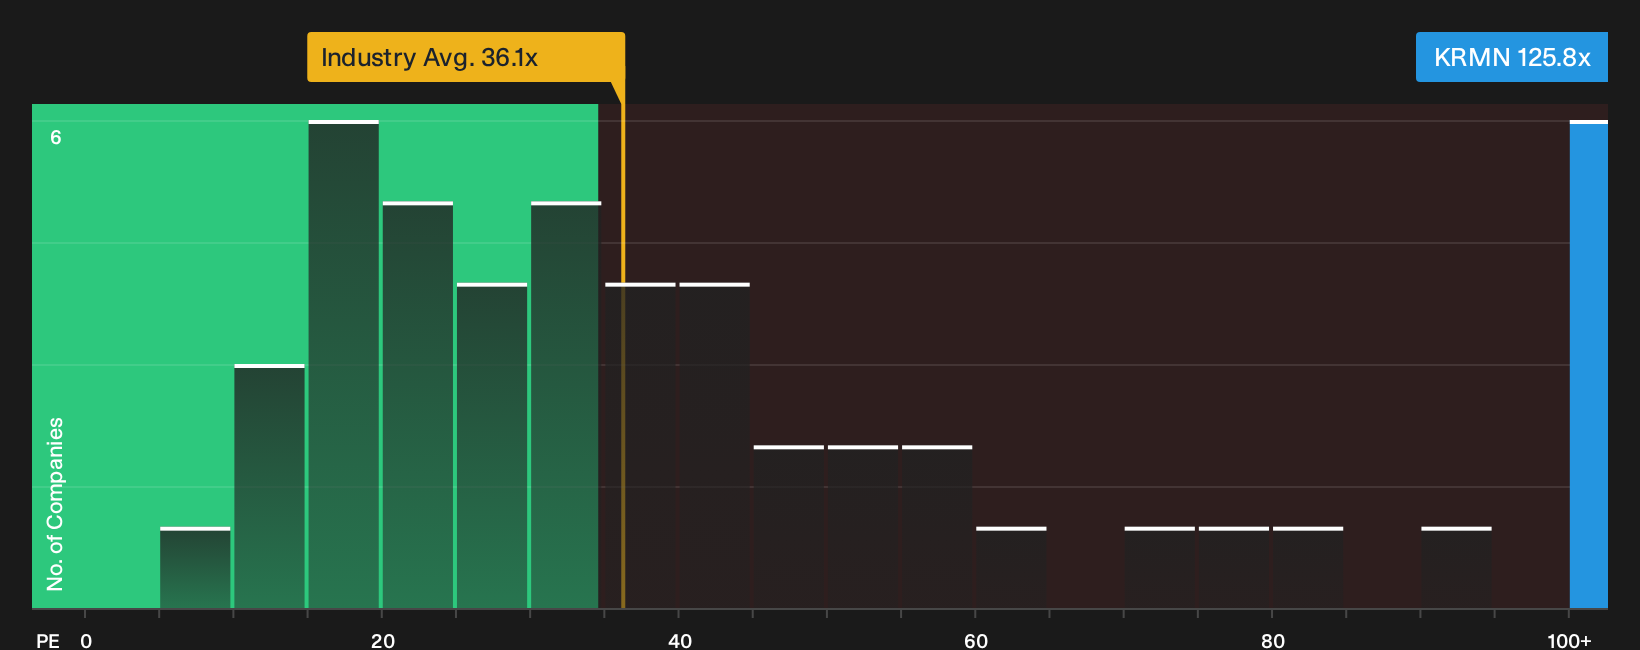
The P/E ratio is a useful lens for Karman Holdings because investors are focused on how much they are paying for every dollar of current earnings. On this metric, the stock trades on a P/E of 125.8x, compared with an Aerospace & Defense sector average of 36.1x and a peer group average of 57.9x. That is a hefty premium to both the broader industry and closer listed comparables.
The tailored fair value model, which blends Karman Holdings' growth profile, profitability, scale and risk, points to a lower P/E than where the shares change hands today, so the multiple currently screens as overvalued against that benchmark. Because the Walker Precision Engineering acquisition has raised expectations for future European defense activity, the market appears willing to assign a rich earnings multiple despite the gap to this fair value yardstick. Investors weighing Karman's valuation need to decide whether that optimism around the enlarged business is enough to justify paying such a high earnings ratio relative to its reference point. Explore the numbers behind Karman Holdings's P/E valuation.
The Karman Holdings Narrative: What Would Justify Today's Price?
Narratives on Karman Holdings pick up where this valuation puzzle leaves off by spelling out which growth, margin and earnings paths would need to play out for the shares to be worth materially more or materially less than today’s price. Rather than centering everything on a single multiple or model, each scenario explains the assumptions that sit behind its fair value view so you can track those inputs against actual results over time on Simply Wall St’s Community page.
One of the top community narratives on Karman Holdings: 67% undervalued
"Once Karman's part is designed into a missile or rocket, switching suppliers mid-program is prohibitively expensive and disruptive..."
Discover why this Narrative puts Karman Holdings at 67% undervalued.
One more piece to weigh on Karman Holdings before making a call
Before reacting to where Karman Holdings trades today, it is worth checking how professional analysts currently map out its revenue, margins and earnings a few years from now, and lining that up against the current share price. Explore where analysts expect Karman Holdings to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com