
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Vontier (VNT) AI Charging Tool Launch
- Vontier subsidiary Driivz recently introduced its AI-powered Network Optimization Agent at ICNC26, showing how its intelligence layer turns large volumes of charging, energy and customer data into faster operational decisions for EV charging operators.
- The new tool focuses on real-time network management and aims to support charger uptime, site profitability, first-time-right charging and customer retention, while helping to keep operational complexity in check as charging networks expand.
- We will now look at how Vontier's investment narrative could be influenced by Driivz's new AI driven Network Optimization Agent.
Scan beyond Vontier and Driivz by reviewing a hand picked group of EV and AI infrastructure peers in the 89 AI infrastructure stocks to see how other platforms are positioned for this shift.
Vontier Investment Narrative Recap
To own Vontier, you need to be comfortable with a business that is still anchored in traditional fueling and repair solutions while working to grow its software and EV focused platforms. The near term story hinges on execution in Mobility Technologies and steady demand for replacement and monitoring systems. Driivz's Network Optimization Agent fits that push into higher value, recurring software, but on its own it does not rewrite the short term picture.
The biggest immediate risk remains exposure to legacy fuel dispensers and environmental equipment at a time when EV adoption is rising. High leverage adds another layer of pressure if operating conditions tighten or customers delay capital projects. Driivz's AI tools may help Vontier compete in EV charging software and improve customer stickiness, yet the real test is whether this newer portfolio can offset any strain in Environmental and Fueling Solutions and Repair Solutions.
The Driivz announcement is the clearest operational link between Vontier's historic fuel centric base and its EV and data driven ambitions. An intelligence layer that manages charger uptime, energy usage and customer behavior feeds directly into the Mobility Technologies segment, which already includes Vontier's EV charging network platform and telematics tools. That is where recurring SaaS revenue is most likely to build over time, assuming customers adopt and stay engaged.
For catalysts, investors may want to watch how quickly Driivz's Network Optimization Agent is rolled out across existing and new charging operators, and whether that is reflected in a higher software mix or better retention within Mobility Technologies. The main risk is execution. EV software is crowded and Vontier is competing with larger software players while also carrying meaningful debt and managing softer Repair Solutions performance. The thesis on Vontier partly depends on whether products like Driivz can shift the revenue mix toward higher margin, stickier services before any long term decline in legacy fueling becomes more visible.
Vontier's current analyst narrative points to revenues of US$3.3b and earnings of US$539.8m by 2029, based on a forecast revenue growth rate of 2.2% per year and an earnings increase of about US$127.3m from current earnings of US$412.5m.
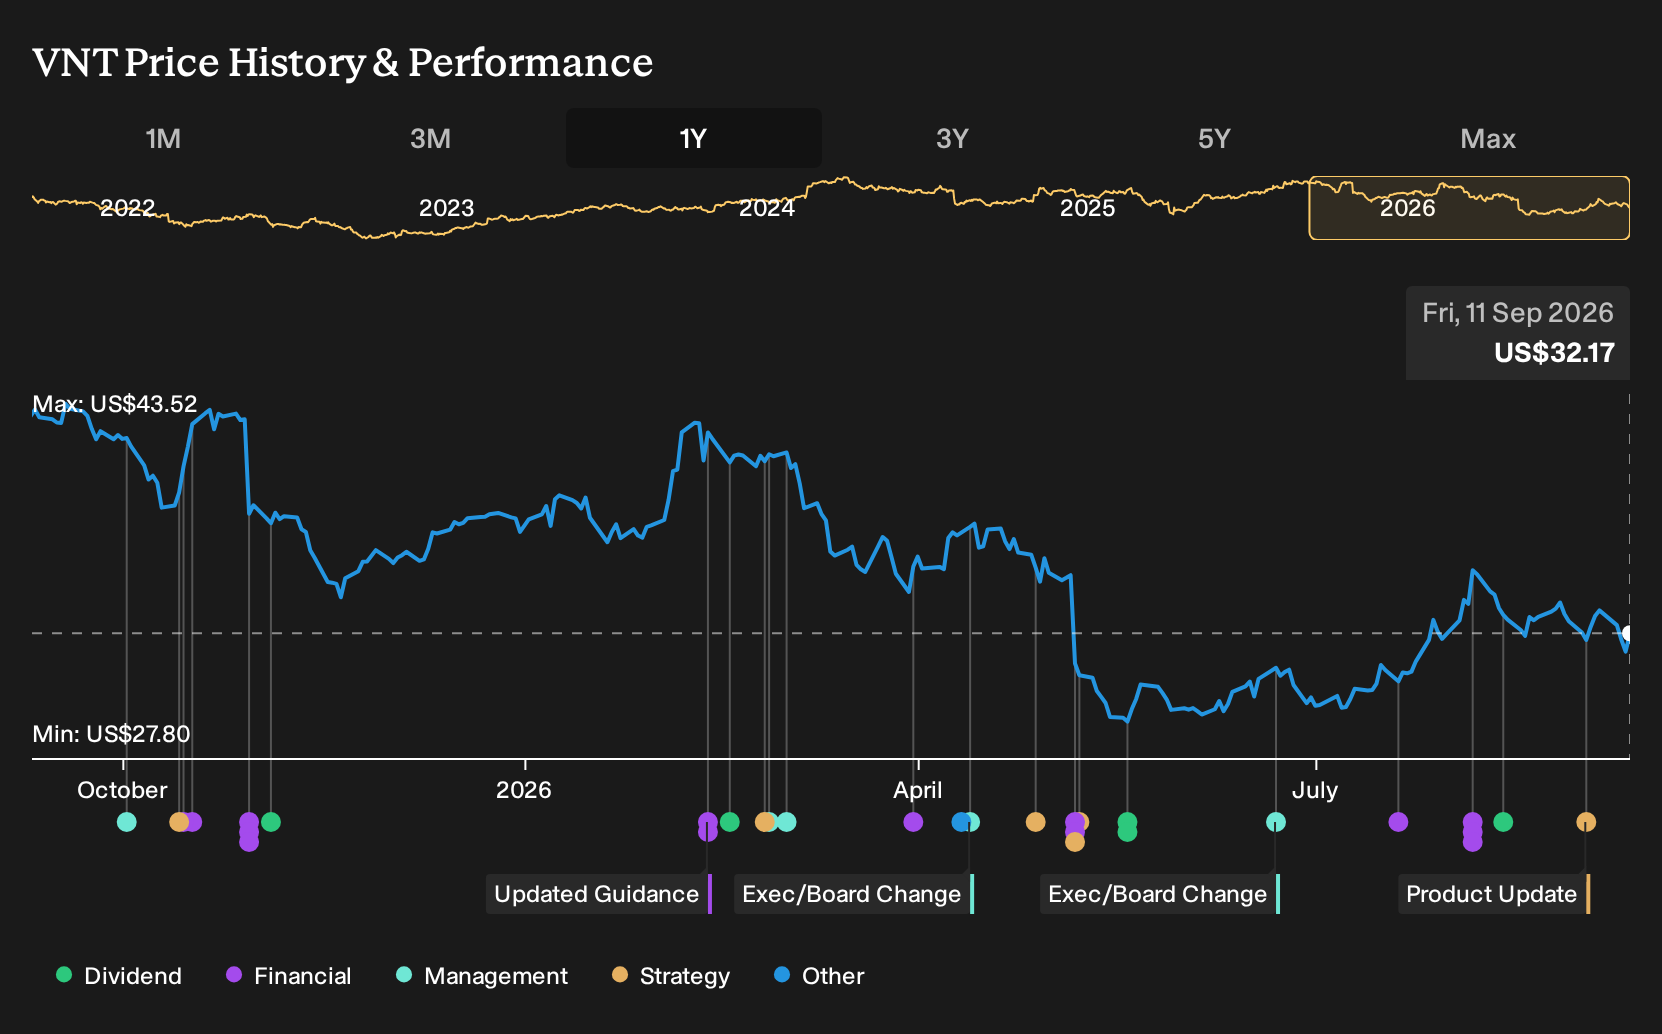
Uncover why Vontier's fair value indicates a 27% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community span a wide band from US$15 to US$70, which shows how far apart views on Vontier can be. These retail perspectives do not yet reflect Driivz's AI rollout, so you may want to weigh them against risks around legacy fueling demand and competition in EV software.
Explore 4 other Vontier fair value estimates, including one that suggests as much as 53% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vontier research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Vontier. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vontier's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vontier?
Once you have formed a view on Vontier, it can help to set it alongside other opportunities that match your risk tolerance and income needs using the Simply Wall St Screener.
- For investors who want potential upside without paying up for quality, compare Vontier against a curated set of attractively priced businesses in the 32 high quality undervalued stocks.
- If capital preservation sits high on your priority list, weigh Vontier next to companies in the 11 resilient stocks with low risk scores that focus on resilience and lower volatility.
- For those hunting for future leaders that are not yet widely followed, balance your Vontier thesis with opportunities in the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com