
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Mitsubishi HC Capital (TSE:8593) Is Drawing Attention Again, What Is Behind It?
Recent freight coverage has spotlighted Mitsubishi HC Capital (TSE:8593) as a lender that continued financing truck carriers while many rivals retreated. This has created a different competitive field for equipment funding.
That support for freight carriers sits against a share price of ¥1,398.5 and a 90 day share price return of 6.39%, while total shareholder return over 1 year is 16.73% and 5 year total shareholder return is 185.62%. This points to momentum that has built up over time rather than just a short burst around the latest trucking headlines.
Scan beyond Mitsubishi HC Capital and see how other lenders and asset financiers are positioned with our curated list of list of solid balance sheet and fundamentals (19 results)
Mitsubishi HC Capital now trades close to ¥1,400, while analyst targets cluster nearer ¥1,492 and one intrinsic value model suggests a far steeper gap. Which reference point best reflects fair value after the recent freight driven move?
Price-to-Earnings of 14.7x: Is it justified?
Mitsubishi HC Capital screens as inexpensive on one key measure, with a P/E ratio of 14.7x that flags up against several reference points.
The P/E multiple compares what investors are paying today for each unit of current earnings. For a diversified financier like Mitsubishi HC Capital operating across leasing, aviation, logistics and real estate, that lens helps you judge how the market is pricing the earnings power from a broad portfolio of assets rather than a single product line.
On the numbers provided, the share price of ¥1,398.5 sits below an estimated fair P/E of 17.6x. This indicates the earnings stream may be priced more cheaply than the regression based fair ratio level that some investors might consider. Compared to a peer average of 19.9x, the stock trades on a lower earnings multiple. Relative to the broader JP diversified financial industry on 14.2x, it edges slightly higher, which suggests the market is paying a modest premium to the sector but a discount to closer peers.
Explore the SWS fair ratio for Mitsubishi HC Capital.
Result: Price-to-Earnings of 14.7x (UNDERVALUED)
Still, the Mitsubishi HC Capital story can change quickly if freight demand softens or credit conditions tighten for highly leveraged transport borrowers.
Find out about the key risks to this Mitsubishi HC Capital narrative.
Another View on Mitsubishi HC Capital's Valuation
The first lens on Mitsubishi HC Capital focused on its P/E, which pointed to some value support. A different tool, our DCF model, presents an estimated fair value of ¥2,986.95 versus the current ¥1,398.5, implying the shares screen as heavily undervalued. Which signal should carry more weight in your framework?
Look into how the SWS DCF model arrives at its fair value.
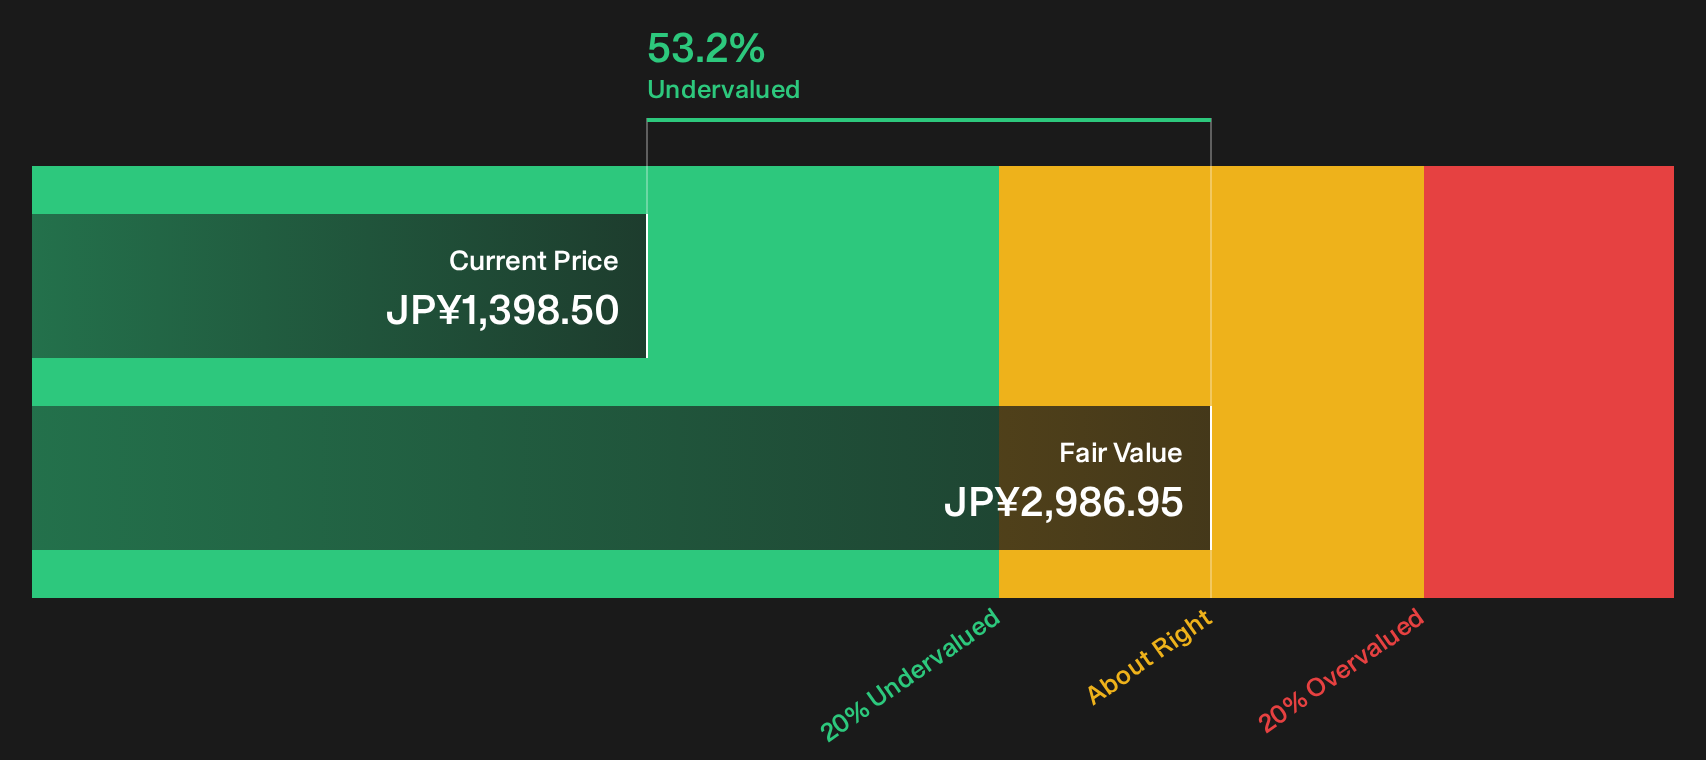
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsubishi HC Capital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Mitsubishi HC Capital feel tricky to interpret, it may be helpful to quickly review the full risk and reward picture yourself. To round out your research, weigh both sides in our breakdown of 2 key rewards and 2 important warning signs
Looking for more Mitsubishi HC Capital style ideas?
Do not stop your research with Mitsubishi HC Capital alone. Use the Simply Wall Street Screener to spot other opportunities that match your checklist before the market does.
- Target higher potential by scanning for companies that still look mispriced using our focused list of 17 high quality undervalued stocks.
- Build more resilient income by concentrating on businesses offering robust yields and consistent payouts across our hand picked 18 dividend fortresses.
- Protect your downside by filtering for companies with strong finances and durable fundamentals through the carefully curated 12 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com