
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
OPKO Health (OPK) Could Be 64% Undervalued On Its $125 Million Royalty Backed Financing
OPKO Health (OPK) is back in the spotlight after it expanded its financing relationship with HealthCare Royalty through US$125 million of senior secured notes, which are tied to future mazdutide royalty payments in China.
OPKO Health’s financing update lands after a choppy year for the stock, with a 30 day share price return of 13.77% and a year to date gain of 23.62%, contrasting with a 5 year total shareholder return that is down 58.58%. This suggests short term momentum is improving even as long term investors remain under water on the position.
Spot fresh financing stories like OPKO Health’s and compare them with other handpicked healthcare and royalty-driven opportunities using our 15 high quality undiscovered gems.OPKO Health just tapped future China mazdutide royalties instead of fresh equity, which lifts the stock but not the share count. Is most of the easy upside already reflected, or is this move only setting the stage?
Most Popular Narrative: 64% Undervalued
Analysts following OPKO Health see a wide gap between the current share price of $1.57 and a fair value estimate of $4.38, and that view leans heavily on how its diagnostics and pharmaceutical pipelines reshape the business over time.
The sale of BioReference's oncology and related clinical testing assets to Labcorp is expected to sharpen OPKO Health's focus on its core testing business, drive significant cost savings, and support the Diagnostics segment's transition to cash flow positive and profitability in 2025, providing margin expansion and stabilizing earnings.
See why 14 investors see OPKO Health as 64% undervalued.
Result: Fair Value of $4.38 (UNDERVALUED)
Still, OPKO Health carries real execution risk if recurring losses continue and heavy R&D spending fails to translate into commercially successful products.
Find out about the key risks to this OPKO Health narrative.
Another View On OPKO Health’s Valuation
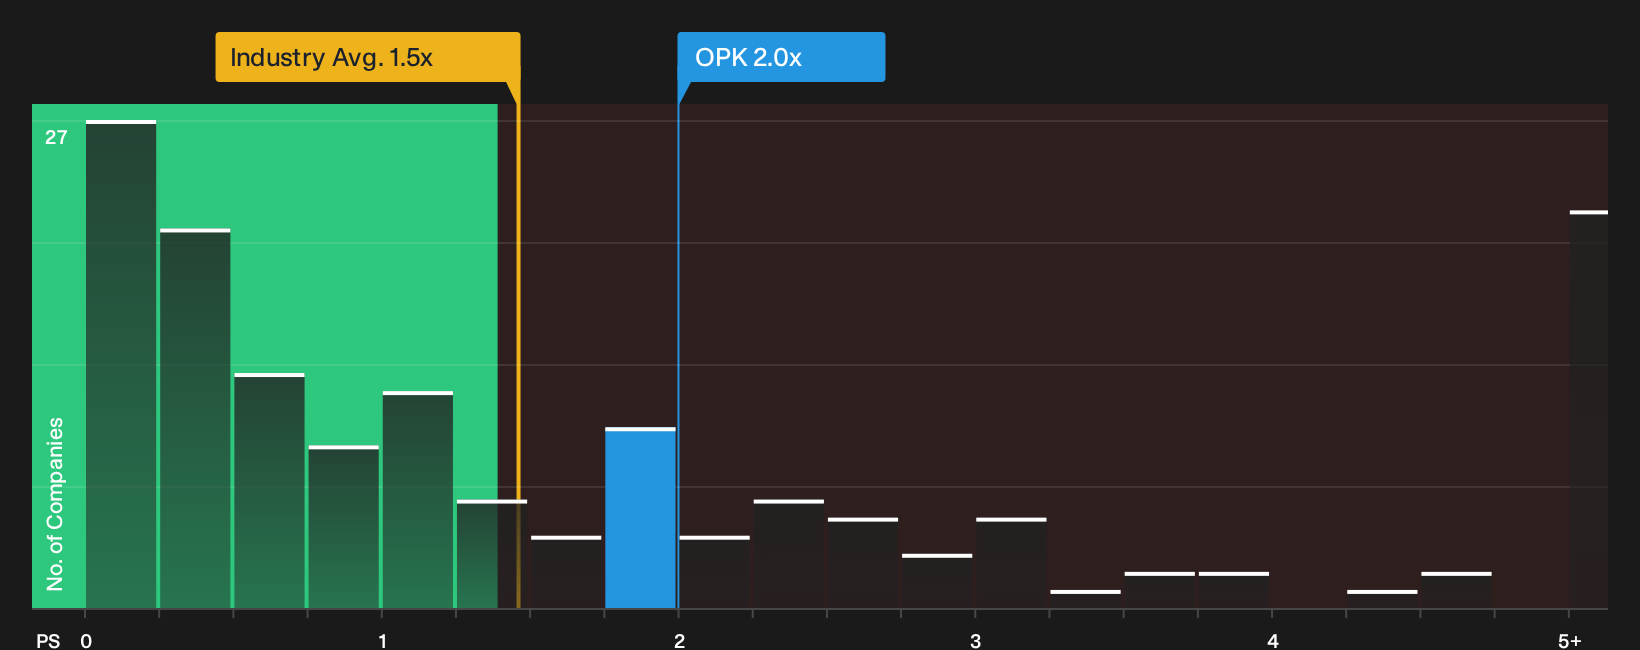
The first take on OPKO Health leans heavily on long term forecasts and a fair value of $4.38. A simpler yardstick tells a very different story. On P/S, OPKO trades at roughly 2x revenue, compared with 1.5x for the wider US Healthcare sector and 1.4x for close peers, while the fair ratio sits nearer 0.6x. That kind of gap points to real valuation risk if sentiment cools or revenue delivery falls short. Which signal do you trust more: the discounted future story, or what today’s sales multiple is already asking you to believe?
Before relying on any single approach, it helps to see how the current price stacks up against our full valuation breakdown and peer checks, including the fair ratio, in one place, which you can do through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
There are mixed signals on OPKO Health so far. If you want to move quickly and decide where you stand, start by reviewing its 3 important warning signs.
Looking for more investment ideas beyond OPKO Health?
If OPKO Health has your attention, do not stop there. Broaden your watchlist with a few focused idea hubs built from the same data-driven process.
- Target potential value opportunities early by scanning our hand picked pool of quality candidates through the 32 high quality undervalued stocks.
- Strengthen your defensive side by reviewing companies that combine resilient finances with lower risk profiles using the 11 resilient stocks with low risk scores.
- Track lesser known opportunities that show solid fundamentals inside the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com