
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Kroger (KR) Stock Looks Hard To Call Despite Raised Profit Outlook
Kroger has delivered a solid multiyear return for shareholders, yet the recent share price level raises a simple question for you as an investor: Is the current valuation of the stock adequately supported by the earnings power of the underlying grocery business?
- Over the past 5 years, Kroger shares are up about 61.3%, which puts more weight on whether the current earnings justify that longer run-up.
- The company has recently lifted its full year profit outlook while working through sales headwinds, which can shift how you think about the durability and timing of future earnings and cash generation.
- There is a second opinion on Kroger worth weighing. See what analysts think Kroger's shares could be worth.
The issue now is whether Kroger's recent share price around US$58.49 is reasonably aligned with what its earnings suggest investors are paying for.
If you are weighing Kroger against similar earnings focused stories, it can help to line it up next to 32 high quality undervalued stocks.
Where Does Kroger Sit on Earnings?
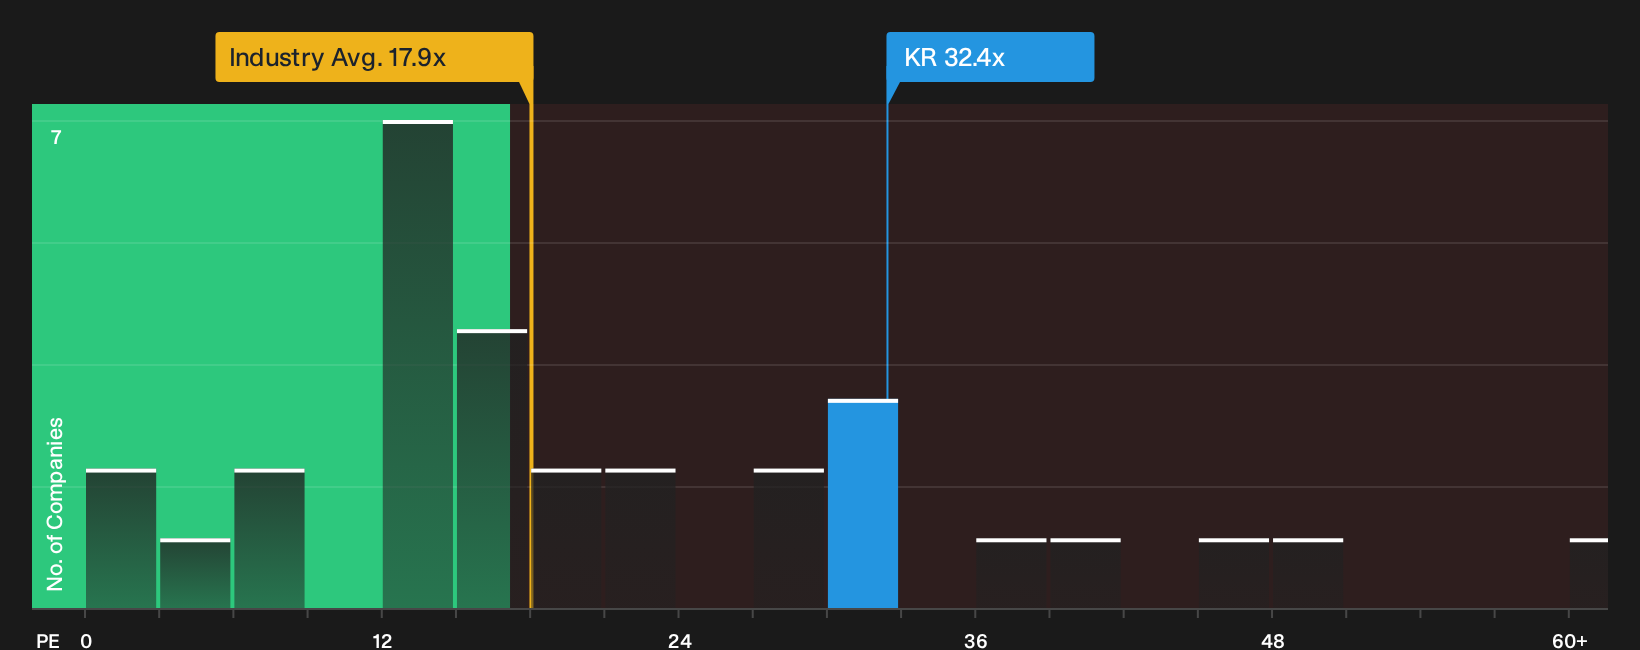
The P/E ratio fits Kroger because earnings are a central yardstick for a mature grocery and retail operation. At a current P/E of about 32.4x, Kroger trades below the Consumer Retailing peer group at roughly 39.0x, yet well above the broader industry average of about 17.9x. That combination indicates the stock is priced richer than the typical retailer in the sector but at a lower multiple than similar earnings-focused peers.
The fair P/E that drops out of the model sits close to Kroger's current 32.4x, so the market price and that tailored yardstick are pointing in a similar direction. Because management recently raised the full-year profit outlook after beating quarterly earnings guidance, the present multiple already reflects investors treating that earnings profile as relatively strong. For you as a shareholder or potential buyer, the key question is whether Kroger can keep justifying a P/E in the low 30s compared with both its own history and the economics of food retailing. Explore the numbers behind Kroger's P/E valuation.
The Kroger Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Kroger pick up where the valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to hold for the stock to look meaningfully higher or lower than today’s price based on those assumptions. Each narrative ties a fair value to a clear storyline about Kroger's possible catalysts and risks so you can track over time which version of events appears to be unfolding.
Community views on Kroger split between those who see meaningful upside in the transformation plan and those who think expectations are already largely reflected in the price.
Bull case: 15% undervalued
"Aggressive cost optimization efforts, including further supply chain automation, adoption of AI and data analytics for shrink reduction, and a comprehensive review of store performance, are expected to enhance operational efficiency…"
Discover why this Narrative puts Kroger at 15% undervalued.
Bear case: roughly fairly valued
"Although Kroger is ramping new store openings and improving store execution to capture more of the essential food at home market, long running competition from clubs, discounters and supercenters may continue to fragment share and temper revenue and margin expansion…"
Explore why this Narrative puts Kroger at roughly fairly valued.
One more Kroger question before you act
Everything so far has focused on what Kroger looks like today, but professional analysts have mapped out where they expect this business to be in a few years, which gives you another angle to compare with the current pricing. Explore where analysts expect Kroger to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com