
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
General Motors (GM) Reaches New Unifor Deals, Is It Still Below Fair Value?
Labor agreements in Canada reshape the General Motors investment story
General Motors (GM) reached new three-year collective agreements with Unifor in Canada, combining more than US$1 billion in committed plant investment with wage and benefit gains for about 4,600 Ontario workers.
The new Unifor agreements arrive after a mixed stretch for General Motors, with the share price down 2.4% over the last week and 1.3% over the past month, yet still ahead 5.7% year to date. Total shareholder return sits at 46.5% over one year and 164.7% over three years, suggesting longer term momentum remains stronger than the recent pullback.
Spot opportunities that rhyme with General Motors’ mix of labor stability and capital investment by screening for companies with resilient operations and fresh capital commitments using the list of solid balance sheet and fundamentals (23 results).For General Motors, that mix of fresh Canadian investment and a short term share pullback raises a simple issue. Are traders cooling on the story while the underlying business stays on track, or is sentiment flagging for a reason that shows up in the valuation next?
Most Popular Narrative: 14% Undervalued
General Motors is trading at $85.62 against a widely followed fair value estimate of about $100. This places fresh focus on how its mix of AI, software, defense and manufacturing plans feeds into that valuation story.
The growing monetization of software and services such as Super Cruise and OnStar, evidenced by $4 billion in deferred revenue and rapid subscriber growth, creates higher-margin recurring revenue streams, supporting long-term earnings expansion beyond traditional vehicle sales.
See why 96 investors see General Motors as 14% undervalued.
Result: Fair Value of $100.04 (UNDERVALUED)
Still, persistent tariff headwinds of US$4b to US$5b and higher warranty costs tied to early EV launches could quickly undermine the General Motors upside narrative.
Find out about the key risks to this General Motors narrative.
Another View: General Motors On Earnings Multiples
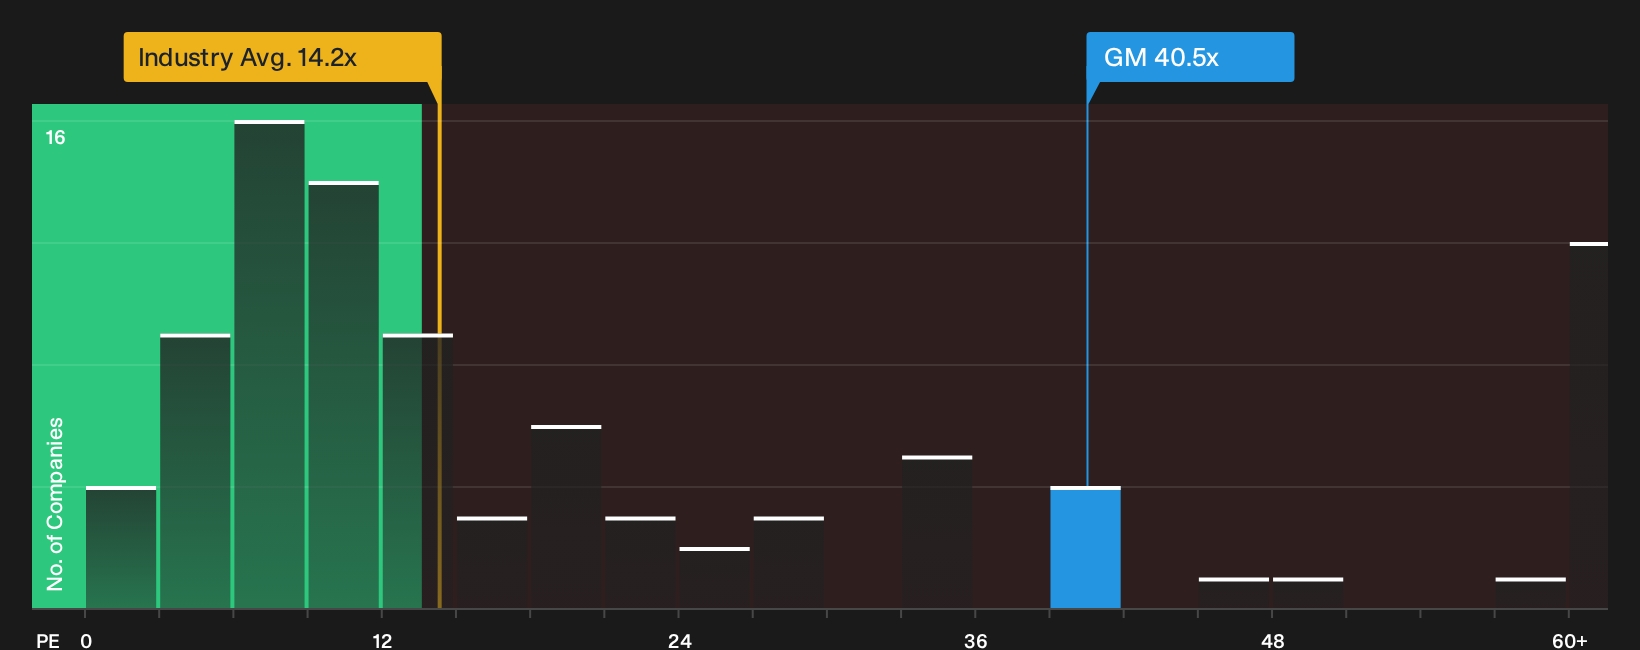
The SWS DCF model points to General Motors trading at a discount to modeled cash flows, yet the P/E ratio tells a different story. GM changes hands at 40.5x earnings compared with 14.2x for the global auto group, peers at 27.5x, and a fair ratio estimate of 25.6x. That gap implies investors are already paying up for growth and execution, so how comfortable are you with that premium if sentiment turns?
For readers weighing this earnings based view against the cash flow approach, it is worth testing how much of that premium still feels reasonable as new information comes through, which is exactly what the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this all feels like a tug of war between optimism and concern around General Motors, consider moving quickly, reviewing the evidence yourself, and then stress testing that view against the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond General Motors?
Once you have a view on General Motors, do not stop there. Broader idea generation can help you pressure test your thesis and spot new opportunities early.
Use the Simply Wall St Screener to widen your field of potential investments with a curated set of targeted ideas that match different risk and return preferences.
- Target potential mispricings by scanning for quality companies trading below estimated value using the 32 high quality undervalued stocks.
- Prioritise resilience and capital strength by focusing on businesses with solid balance sheets through the list of solid balance sheet and fundamentals (23 results).
- Hunt for underfollowed prospects with strong fundamentals using the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com