
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Infomart (TSE:2492) Fully Valued On Oasis Activism And Governance Pressure?
Infomart activism triggers fresh governance questions
Oasis Management has opened an activist dialogue with Infomart (TSE:2492) after proposing asset disposals, boardroom changes, and partial business abolition aimed at corporate value and governance over the coming year.
Infomart’s 1 day share price return of 2.00% and 30 day gain of 16.29% sit on top of a 90 day share price return of 92.45% and a 1 year total shareholder return of 105.11%. This points to strong momentum that activist involvement is now testing against longer term three and five year total shareholder performance figures of 52.20% and a decline of 32.44% respectively.
Scan how Infomart’s activism story compares with other potential breakout targets on our hand picked screener of 74 high quality undiscovered gems across the market.
After a 92.45% move in 90 days and fresh pressure from Oasis, the question around Infomart is simple: Is meaningful upside still ahead, or has most of the rerating already happened before the valuation case is tested?
Price-to-earnings of 84.9x for Infomart: Is it justified?
Infomart now trades at a P/E of 84.9x, which is far richer than both peers and the wider JP Professional Services group. As a result, the recent share price surge is sitting on an already demanding valuation multiple.
The P/E ratio compares the current share price with earnings per share. For a platform business like Infomart, this metric effectively shows how much investors are willing to pay today for each unit of current profit, based on expectations for future expansion in areas such as its BtoB-PF FOOD and BtoB-PF ES segments.
Against its direct peer set on 14.7x earnings, Infomart’s 84.9x P/E implies the market is pricing in much stronger profit growth than similar companies. The gap to the estimated fair P/E of 32.8x is also wide. This is a level the multiple could move towards if sentiment cools or earnings do not keep pace with this optimism.
Compared with the broader JP Professional Services industry on 13.3x earnings, the premium is even more pronounced. That scale of difference signals investors are ascribing a substantial quality or growth premium to Infomart that goes well beyond sector norms.
Explore the SWS fair ratio for Infomart.
Result: Price-to-earnings of 84.9x (OVERVALUED)
Still, Infomart’s 84.9x P/E, compared with a 32.8x fair level and a share price above the ¥420 analyst target, leaves limited room if sentiment or earnings expectations slip.
Find out about the key risks to this Infomart narrative.
Another view on Infomart’s valuation
While the P/E discussion paints Infomart as expensive, the SWS DCF model points to an even harsher verdict. At a share price of ¥714 and an estimated future cash flow value of ¥158.47, the stock looks very fully priced on cash flow assumptions. That gap raises a simple question for investors: Are you backing momentum or the cash flow math.
Look into how the SWS DCF model arrives at its fair value.
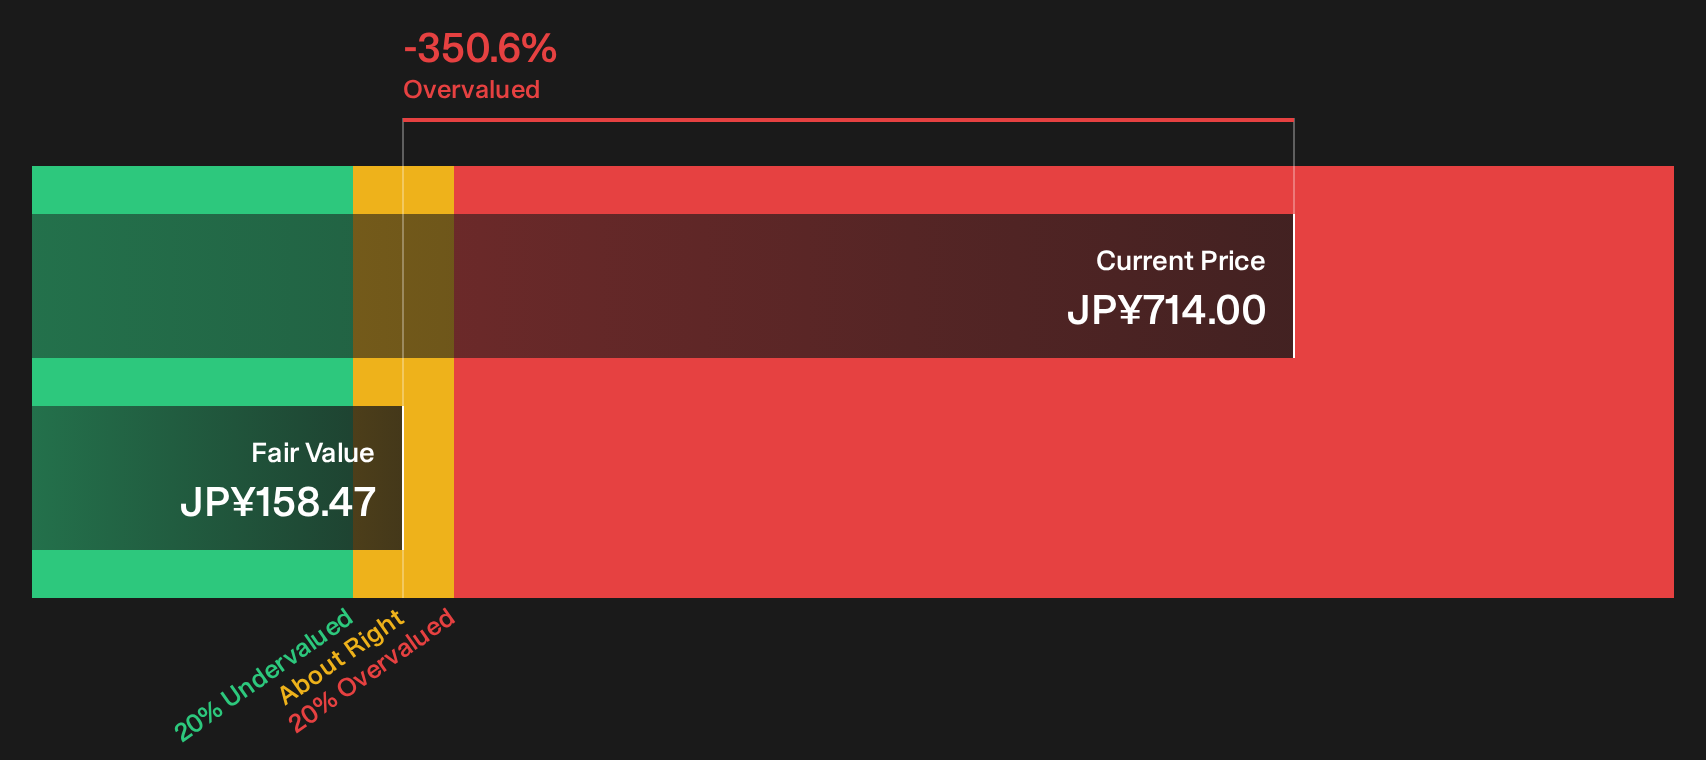
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Infomart for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Infomart is clearly split, with both risk flags and upside angles in play. It makes sense to move fast and stress test the numbers yourself before the narrative moves on. To see how those concerns and potential bright spots stack up side by side, review the 2 key rewards and 2 important warning signs
Looking for more Infomart-sized opportunities?
If Infomart has caught your eye, do not stop here. Broaden your watchlist with fresh ideas now so you are not chasing the next move late.
- Target potential bargains with resilient fundamentals by running the Simply Wall St screener focused on 17 high quality undervalued stocks.
- Prioritise resilience and capital protection by checking companies that feature in the low volatility and risk focused 10 resilient stocks with low risk scores.
- Strengthen your income ideas by reviewing high yielding opportunities highlighted in the focused list of 18 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com