
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Krystal Biotech (KRYS) Cheap On Its Cantor Conference Spotlight?
Krystal Biotech (KRYS) is set to present at the 12th Annual Cantor Fitzgerald Global Healthcare Conference in New York on September 10, 2026. The presentation is drawing fresh attention to its genetic medicines portfolio.
Recent trading shows Krystal Biotech shares at $347.0, with a 1-day share price return of 0.42% and a 30-day share price return of 4.43%. The year-to-date share price return of 40.54% and a very large 5-year total shareholder return of 528.05% point to momentum that long-term holders will be closely watching as this conference appearance approaches.
Scan biotech peers showing similar momentum and clinical catalysts by running the curated 15 high quality undiscovered gems alongside Krystal Biotech ahead of the Cantor conference.
Krystal Biotech now trades about 11% below the average analyst target after a strong year-to-date run. Is that discount a genuine opportunity, or a signal that caution around this genetic medicines story still makes sense?
Most Popular Narrative: 10% Undervalued
Krystal Biotech last traded at $347, while the most followed narrative pegs fair value closer to $385. That gap puts the focus on whether the current price reflects the expected mix of genetic medicine launches, profitability and risk that analysts have built into their models.
The expansion of Krystal's pipeline, including imminent and near-term clinical readouts in lung disease (AATD, CF), ophthalmology, oncology (NSCLC), and aesthetics, leverages increased R&D productivity, which could drive future revenue growth and diversify earnings beyond a single product.
Favorable dynamics in global healthcare, such as greater willingness to reimburse curative, high-value genetic therapies and broadening awareness due to successful launches and patient outcomes, should support sustainable long-term revenue growth and premium pricing, boosting revenue visibility and potentially net margins.
See why 31 investors see Krystal Biotech as 10% undervalued.
Analysts who contribute to this narrative have combined those pipeline and reimbursement assumptions with a 7.39% discount rate to arrive at the $385 fair value estimate. Their work reflects expectations for stronger revenue and profit margins over time, while using a future P/E that is lower than today to account for execution and competitive risks.
Result: Fair Value of $385 (UNDERVALUED)
Still, the Krystal Biotech story leans heavily on VYJUVEK and smooth execution on international reimbursement, so any setback there could quickly challenge this undervaluation view.
Find out about the key risks to this Krystal Biotech narrative.
Another Angle On Krystal Biotech’s Valuation
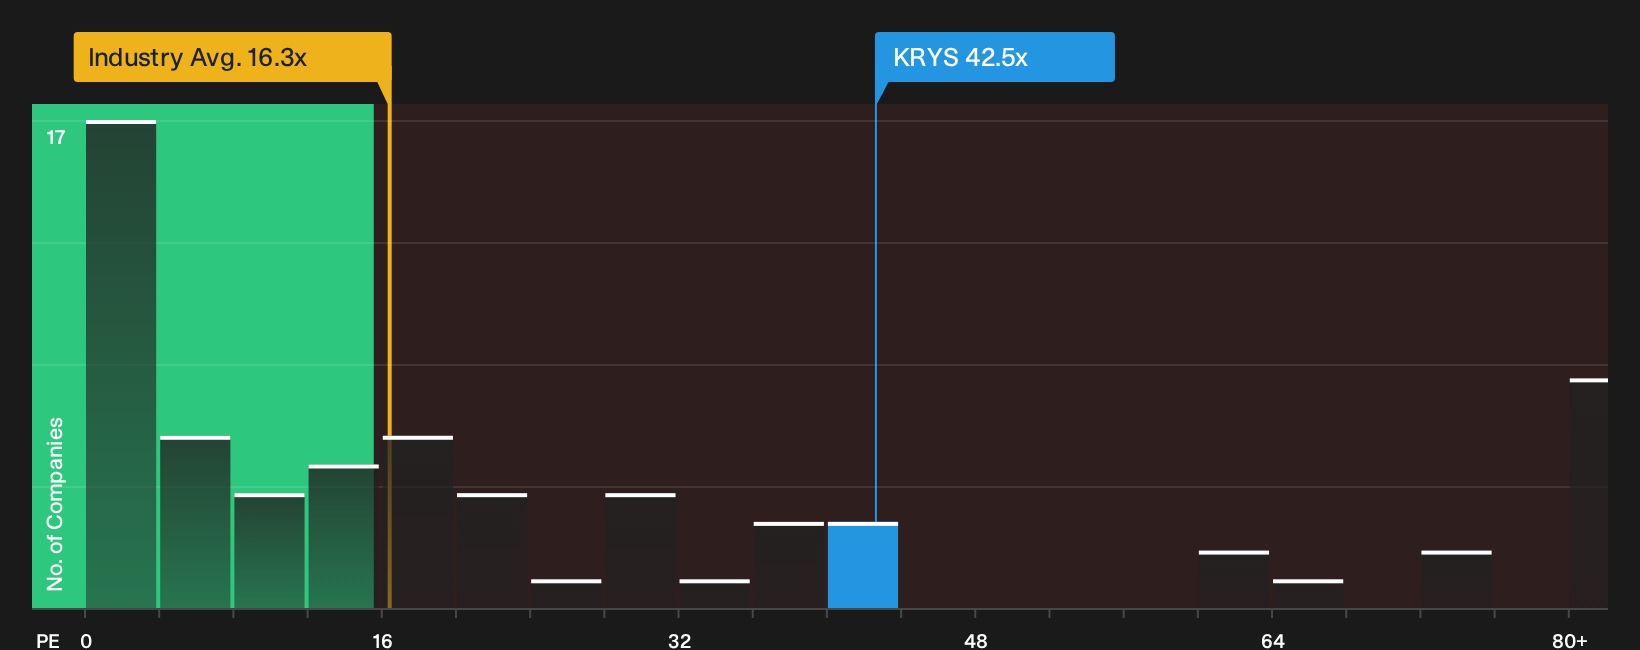
The narrative work around Krystal Biotech leans on fair value of $385, yet the current P/E of 42.5x tells a different story. The US Biotechs industry sits at 16.3x and the fair ratio is 33.8x. That gap points to rich expectations. Is the premium comfort or concern for you?
See what the numbers say about this price: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals across Krystal Biotech’s valuation and narratives can feel messy. Act while the data is fresh and pressure test the balance of 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Krystal Biotech?
Do not stop with Krystal Biotech when you can quickly scan focused stock ideas that match your risk appetite and income goals using the Simply Wall Street Screener.
- Target potential upside by comparing quality businesses trading below their estimated worth through the 32 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on companies with robust finances using the list of solid balance sheet and fundamentals (23 results).
- Lock in dependable portfolio cash flow by searching for income opportunities through the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com