
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Product Launch Require Action From Waters (WAT) Investors?
- Waters Corporation has launched the BD FACSDiscover A7 Cell Analyzer globally, adding a new flow cytometry instrument that combines BD SpectralFX and FACSTruQ calibration technology with guided BD FACSChorus workflows to support highly standardized, high-parameter cell analysis across academic, pharma, and CRO labs.
- The A7’s focus on automation, consistency across sites, and a price-to-performance balance points directly at demand for reproducible, scalable cell analysis in drug development and biomarker research.
- The next area of attention will be how Waters' investment narrative could shift as this high-parameter spectral cytometry platform targets reproducible multi-site workflows.
Scan beyond Waters and see which lab-technology players could be next in line to benefit from high-parameter biology workflows with the 38 robotics and automation stocks.
Waters Investment Narrative Recap
To own Waters, you need to believe the company can turn its analytical workflows strength into durable demand from pharma, CDMOs, and regulated testing, while managing integration risk from BD’s Biosciences and Diagnostic Solutions assets. The immediate swing factor remains how quickly the combined portfolio can translate into steadier recurring revenue and service growth.
The launch of the BD FACSDiscover A7 Cell Analyzer looks directionally helpful but not transformational on its own. It aligns with the push into higher parameter biology and connected lab ecosystems, yet does not change the key near term risk, which is execution on large scale integration while margins sit at 3.6% after a sizeable one off loss.
Among recent developments, the planned combination with BD’s Biosciences and Diagnostic Solutions business is most relevant to this A7 launch. The analyzer leans into biologics and cell based research workflows that BD’s portfolio already serves. That creates a clearer product story for pharma R&D, cell and gene therapy customers, and CROs using multi color flow cytometry.
For you as a shareholder, the link between this deal and the A7 is about whether Waters can actually deliver the projected US$345m cost and US$290m revenue synergies while defending pricing in labs where funding is under pressure. Smooth integration, consistent instrument performance across sites, and uptake of software driven workflows will determine whether this expanded platform becomes a real earnings catalyst rather than just a bigger, more complex operation.
Waters' narrative projects US$7.9b revenue and US$1.4b earnings by 2029. This assumes 19.3% yearly revenue growth and an earnings increase of about US$1.2b from US$166.6m today.
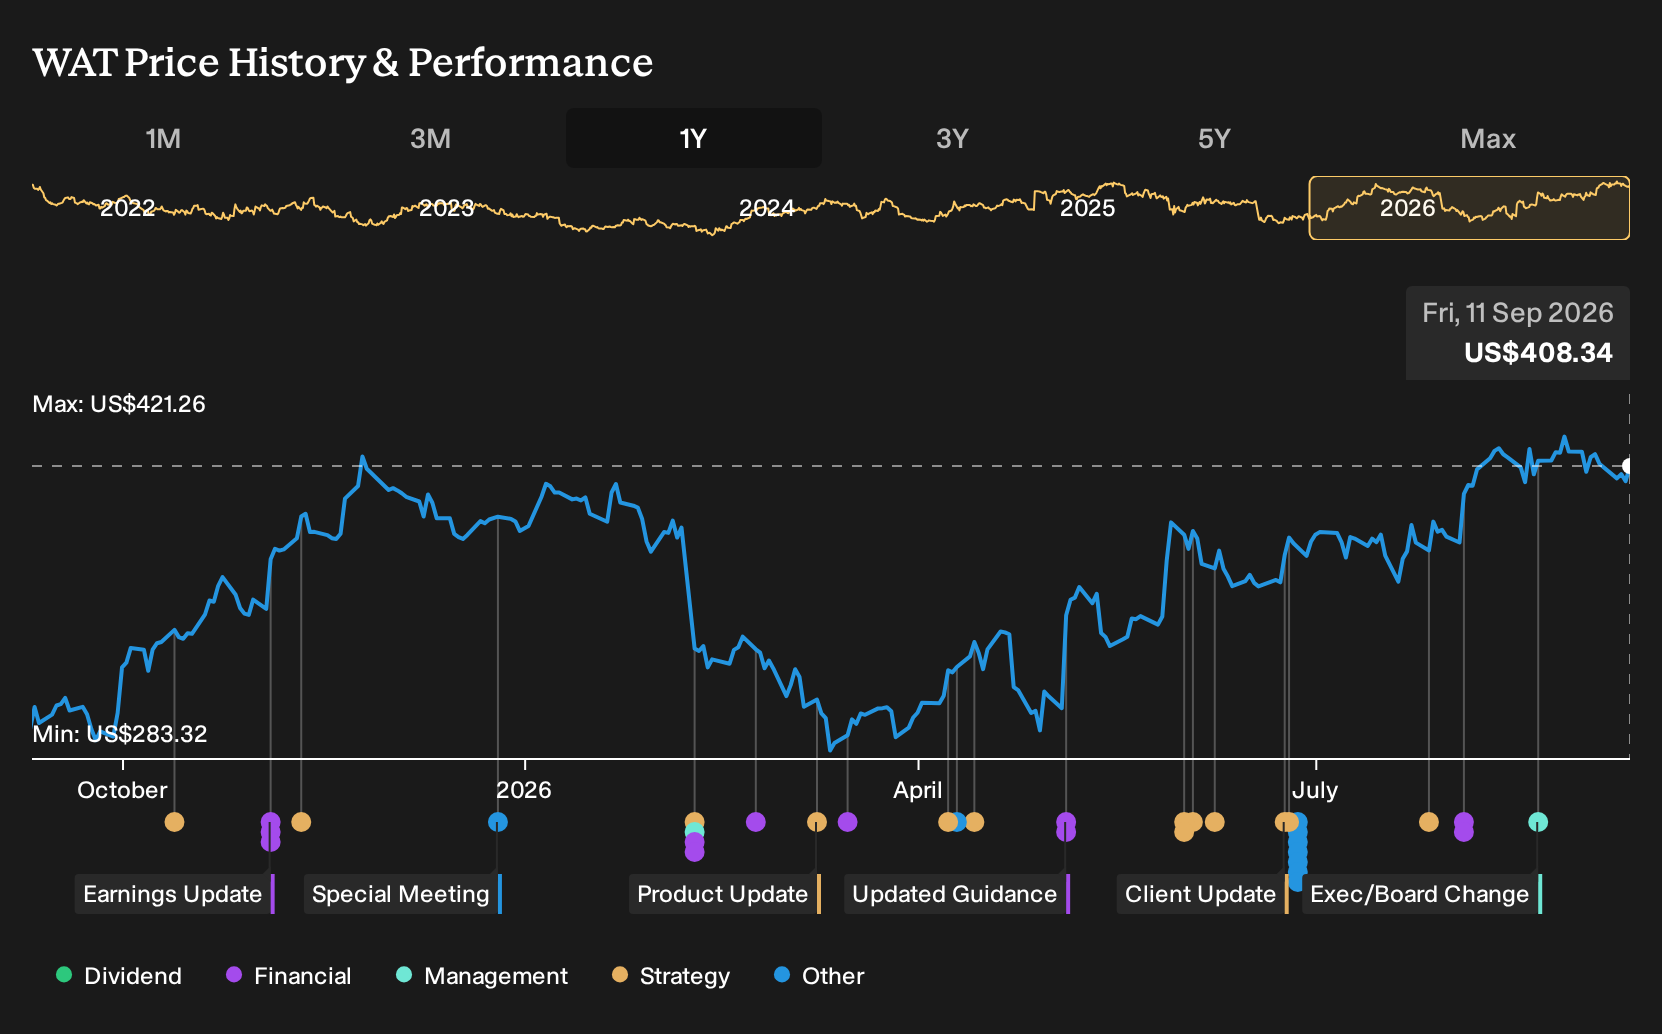
Uncover why Waters' fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You also have a very different story on Waters if you focus on the bearish angle around slower synergy delivery. The most cautious analysts were pencilling in US$7.9b of revenue and US$1.1b of earnings by 2029, versus US$1.4b in the baseline view, before this A7 launch even appeared on the radar. That gap shows how widely opinions can spread. Use it as a prompt to explore several alternative forecasts and decide which version of the future feels closest to your own expectations.
Explore 3 other Waters fair value estimates, including one that suggests it could be worth just $439.70.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Waters research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Waters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Waters' overall financial health at a glance.
Looking For More Investment Ideas Beyond Waters?
If the Waters story has sharpened your thinking about risk, growth, and execution, it can be useful to test that framework across a wider watchlist using the Simply Wall St screener.
- Target strong cash generation and sensible pricing by scanning for businesses that look attractively valued on both quality and fundamentals with the 32 high quality undervalued stocks.
- If capital preservation sits higher on your priority list than aggressive upside, filter for companies with sturdier financial profiles using the 11 resilient stocks with low risk scores.
- For investors hunting for under-followed ideas with solid foundations, broaden the search with a 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com