
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Paylocity Holding (PCTY) Lands Jets Deal As Fair Value Stays In Focus
Paylocity Holding (PCTY) just landed a new partnership with the New York Jets, becoming the NFL franchise’s official human capital management platform for HR, payroll, and spend management on a single system.
Despite the Jets partnership putting Paylocity Holding back in the headlines, the stock has been under pressure in the short term. The 7-day share price return is down 6.96% and the 30-day share price return is down 4.46%. At the same time, the 90-day share price return is up 35.81%, while the 1-year total shareholder return is down 15.21%. This combination points to momentum building recently after a tougher stretch for longer term holders.
Scan beyond Paylocity Holding and this Jets partnership by sizing up other HR and workflow platforms on our hand picked 15 high quality undiscovered gems that could be flying under most investors' radar.
Paylocity Holding now sits in an awkward middle ground, with recent gains colliding with longer term pain. Does that reset leave the risk reward still tilted toward buyers, once the valuation numbers are unpacked next?
Most Popular Narrative: 17% Undervalued
Analysts following Paylocity Holding see a fair value of $171.53 compared with the last close at $141.66. This frames the Jets news against a story driven more by recurring software demand and margin assumptions than short term sponsorship headlines.
Strong client retention (92%+) and accelerating cross-sell of new modules (including Paylocity for Finance) are associated with steady margin expansion and improved operating leverage, evidenced by rising adjusted EBITDA margins and free cash flow.
See why 12 investors see Paylocity Holding as 17% undervalued.
Result: Fair Value of $171.53 (UNDERVALUED)
Still, slowing revenue guidance around 7% to 9% growth and intense competition from larger HCM providers could challenge the upbeat Paylocity Holding narrative.
Find out about the key risks to this Paylocity Holding narrative.
Another View: Paylocity Holding Looks Expensive On Earnings
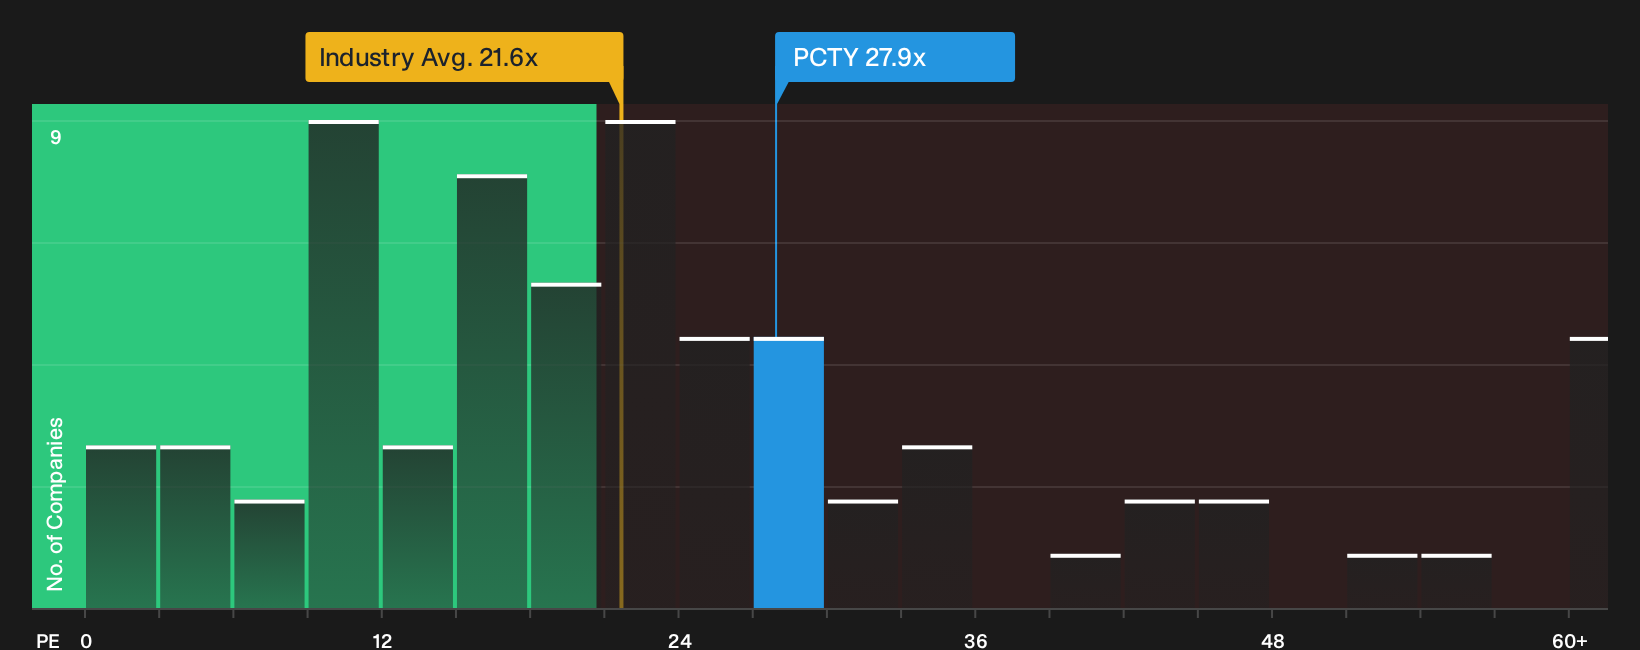
The SWS DCF model points to upside for Paylocity Holding, yet the current P/E of 27.9x tells a different story. That multiple sits well above both the peer average at 19.7x and a fair ratio of 21.8x. This signals meaningful valuation risk if sentiment cools or growth expectations slip.
For investors weighing this gap between cash flow upside and premium pricing, the key question is whether Paylocity Holding has earned enough conviction to justify paying so far above both peers and the fair ratio, or whether patience makes more sense while those expectations are tested in future results.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Paylocity Holding can feel confusing, so move quickly, test the numbers for yourself, and weigh both sides. A balanced starting point is to review the 4 key rewards and 1 important warning sign.
Looking for more Paylocity Holding sized investment ideas?
If Paylocity Holding has you rethinking your watchlist, do not stop here. Use data driven tools to scout fresh opportunities that match your style.
- Target potential bargains by zeroing in on companies that screen as high quality and attractively priced through the 32 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that qualify as consistent high yield payers on the 6 dividend fortresses.
- Prioritise resilience by filtering for companies with dependable financial footing using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com