
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
FedEx Freight Holding Company (FDXF) After Executive Exit And Why Valuation Still Looks In Focus
FedEx Freight Holding Company (FDXF) is under fresh scrutiny after the board removed Executive Vice President Michael B. Lyons for Code of Conduct violations. The move is raising questions about culture, controls, and leadership continuity.
The latest Code of Conduct breach lands on top of a tougher tape for FedEx Freight Holding Company, with the share price at US$128.31 after a 1-day share price return of 3.46%, but a 30-day share price return down 14.63% and a year-to-date share price return down 15.03%, suggesting recent sentiment has weakened even as management talks about demand stabilization and investors watch oil-linked moves and leadership changes closely.
Compare FedEx Freight Holding Company with a curated set of transport and logistics peers that currently screen as 32 high quality undervalued stocks on Simply Wall St.
After a sharp pullback and fresh questions over leadership, FedEx Freight Holding Company looks caught between investors who see most of the bad news priced in and those who think the rebound has already happened. Which camp do the numbers support next?
Preferred P/E of 29.3x: Is it justified for FedEx Freight Holding Company?
On simple valuation terms, FedEx Freight Holding Company trades on a P/E of 29.3x while the last close sits at $128.31, and the stock screens as cheaper than several peers that average 80x earnings.
The P/E ratio compares what investors pay for each dollar of profit. For a freight carrier like FedEx Freight Holding Company, it reflects how the market weighs its earnings profile, exposure to the transport cycle, and expectations for future profitability.
Analysts currently expect earnings to grow 15.46% per year, which is slower than the broader US market forecast of 17.2% but still points to an improving profit base. Against that backdrop, a 29.3x multiple suggests investors are already paying up for forecast earnings growth, yet not to the same extent as the peer average of 80x, where the market is putting a much richer price on each dollar of earnings.
Compared with the US Transportation industry P/E of 34.2x, the stock trades on a lower multiple that implies a discount to sector pricing, even though analysts are in good agreement that the share price could rise 27.8% from here based on their collective price target.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 29.3x (UNDERVALUED).
Still, FedEx Freight Holding Company faces real pressure from leadership upheaval and recent share price weakness, which could quickly change how investors treat that 29.3x P/E.
Find out about the key risks to this FedEx Freight Holding Company narrative.
Another View on FedEx Freight Holding Company: Cash Flows Paint a Different Picture
The earlier look at FedEx Freight Holding Company focused on the 29.3x P/E, which pointed to a discount versus peers. A second lens using the SWS DCF model values the shares at $157.12, compared with the current $128.31 price, implying the stock trades about 18.3% below that cash flow estimate.
This kind of gap suggests investors are either cautious about the forecasts feeding into the model or are putting a heavier weight on near term earnings volatility and governance concerns. The key question for you is simple: Does the current discount reflect risk that has already been fully aired, or is it compensation for issues that are still unfolding?
Look into how the SWS DCF model arrives at its fair value.
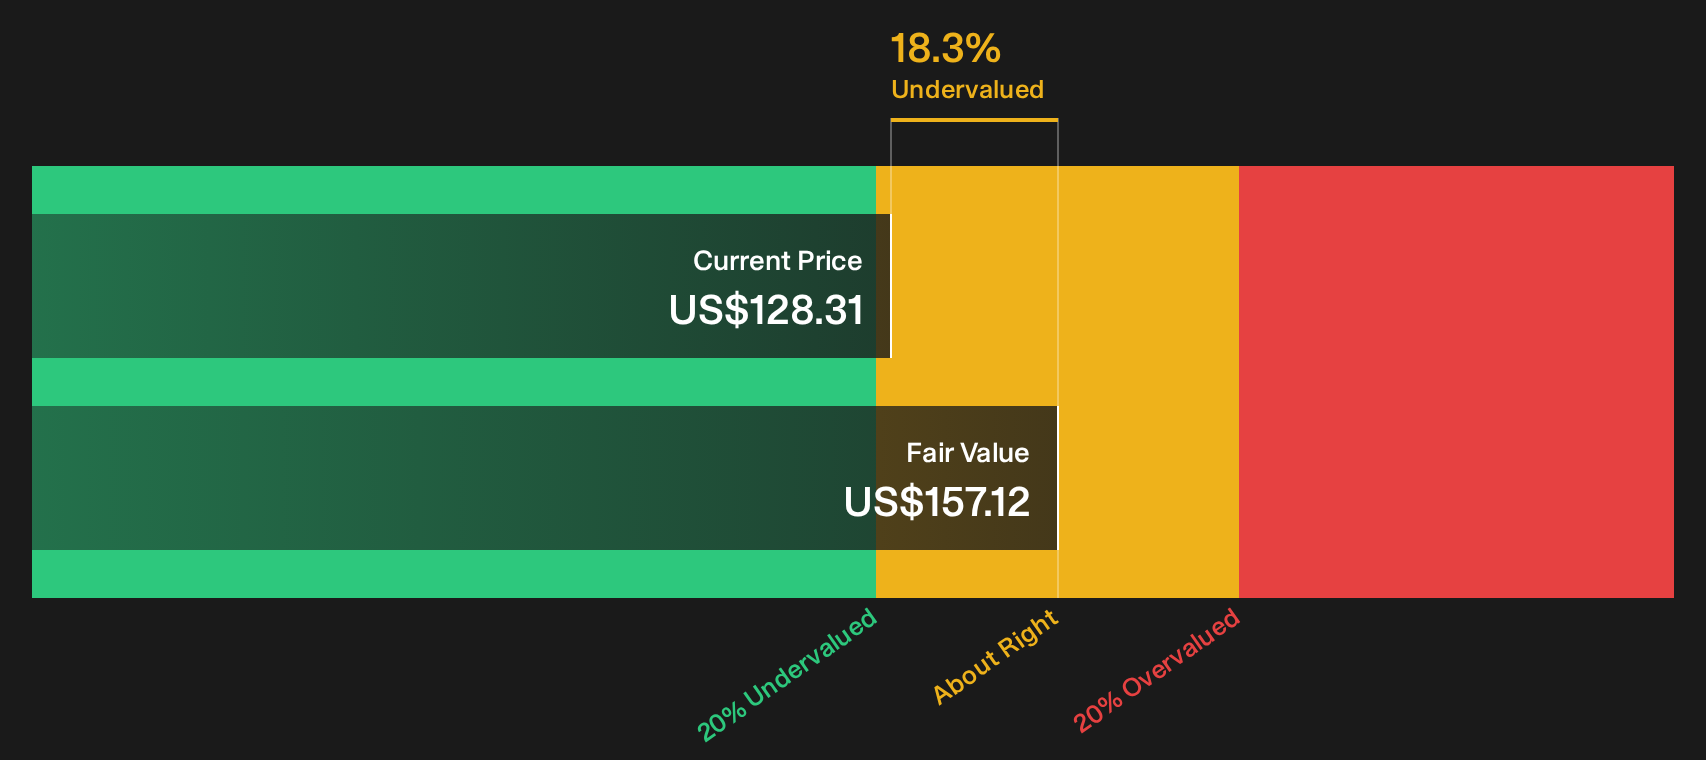
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FedEx Freight Holding Company for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around FedEx Freight Holding Company is clearly split, and the clock is ticking for you to interpret the data on your own terms. To weigh the trade off between the known concerns and the potential upside, review the 3 key rewards and 4 important warning signs
Looking for more FedEx Freight Holding Company investment ideas?
If FedEx Freight Holding Company has your attention now, do not stop here. Widen your watchlist with other ideas that fit your style before the market moves on.
- Target potential mispricing by scanning a curated pool of companies that currently look cheap on quality and value screens using the 32 high quality undervalued stocks.
- Focus on resilience first by filtering for businesses with stronger finances and cleaner balance sheets through the list of solid balance sheet and fundamentals (23 results).
- Hunt for underfollowed opportunities by reviewing a hand picked mix of quieter quality stocks in the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com