
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Sysco (SYY) Reaffirms 2027 Outlook, Is Fair Value Still Above The Current Price?
Sysco (SYY) reaffirmed its earnings outlook for fiscal 2027, guiding for net sales growth of about 6% to 7% to roughly $90b. That confirmation gives investors a fresh reference point.
That confirmation helped extend Sysco’s recent upswing, with a 1-day share price return of 1.09% at a last close of $83.21 and a 7-day share price return of 3.95%, while the 1-year total shareholder return of 7.14% and 3-year total shareholder return of 27.69% point to momentum that has been building rather than fading.
Capitalize on Sysco’s renewed guidance momentum by scanning a curated group of foodservice and consumer-facing operators with resilient fundamentals through the 15 high quality undiscovered gems.Sysco’s reaffirmed 2027 sales path and the stock’s recent climb put a spotlight on one issue: Does fair value sit closer to today’s price or to the much wider range of intrinsic and analyst estimates ahead?
Most Popular Narrative: 6.8% Undervalued
Compared with Sysco’s last close at $83.21, the most widely followed narrative pegs fair value near $89.31, which keeps the current rally in context rather than framing it as runaway enthusiasm.
Sysco is focused on improving its sales consultant workforce, with new hires becoming more productive and a strategic shift in compensation model, which is expected to enhance revenue and earnings starting in fiscal 2026. The company is expanding its fulfillment capacity with new facilities in Florida and internationally in Sweden and Ireland, boosting its storage and distribution ability to capture profitable revenue growth in key markets.
See why 61 investors see Sysco as 7% undervalued.
Result: Fair Value of $89.31 (UNDERVALUED)
Still, the narrative around Sysco can shift quickly if weak consumer confidence further pressures restaurant traffic, or if sales consultant turnover again disrupts customer relationships.
Find out about the key risks to this Sysco narrative.
Another View on Sysco’s Valuation
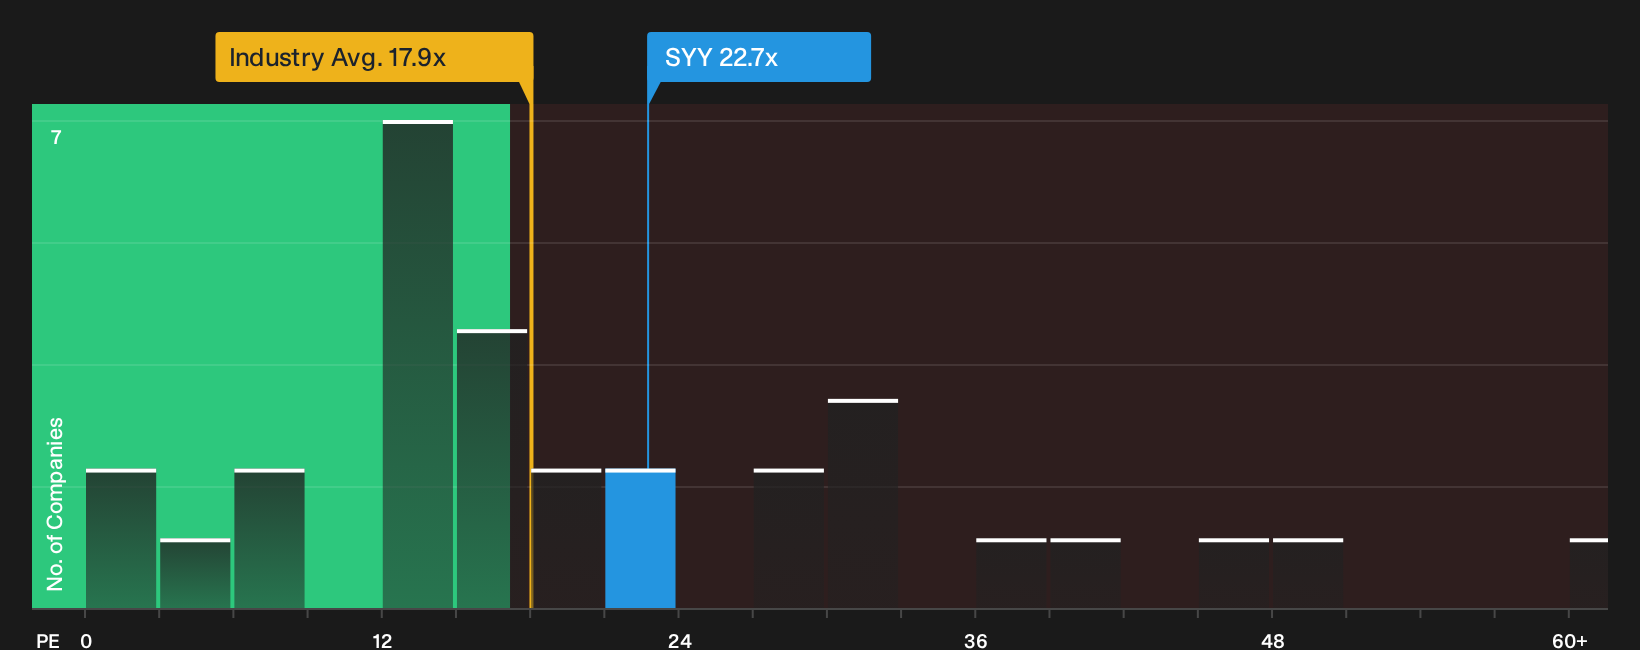
Sysco looks attractive on one metric and expensive on another, which complicates the picture. The stock trades on a P/E of 22.7x compared with 17.9x for the US Consumer Retailing group and 37.6x for closer peers, while the fair ratio sits higher again at 30.9x. That gap can flag both valuation risk if sector sentiment cools and potential upside if the market edges toward the fair ratio. Investors need to decide which side of that trade they prefer to be on.
See what the numbers say about this price in more depth through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Sysco’s valuation and risk profile can be confusing, so move quickly, review the underlying data, and weigh the 3 key rewards and 1 important warning sign.
Want more ideas beyond Sysco?
If Sysco has your attention, do not stop here. Use the same data driven approach to widen your watchlist and review your next move.
- Target resilient cash generators by reviewing our curated 32 high quality undervalued stocks that pair quality fundamentals with prices that may not fully reflect them.
- Strengthen your income stream by scanning the 6 dividend fortresses and focus on businesses built around consistent, higher yielding payouts.
- Limit downside risk by zeroing in on the 11 resilient stocks with low risk scores and concentrate on companies with sturdier financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com