
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can Hemlo Mining (TSX:HMMC) Justify Its Valuation Following South Rim Assay Results?
Hemlo Mining (TSX:HMMC) has drawn fresh attention after reporting new high-grade gold assay results from its South-Rim Zone drilling, highlighting potential low-capital resource growth near existing Hemlo mine infrastructure.
At around CA$8.38, Hemlo Mining has been on a strong run, with a 30-day share price return of 20.58% and a year-to-date share price gain of 67.6%. The 1-year total shareholder return is very large compared with the 5-year total shareholder return, which is down 25.51%, suggesting momentum has picked up sharply following the recent assay updates and broader 2026 exploration program.
Capitalize on the momentum around Hemlo Mining and its South-Rim results by lining up your next ideas against a curated set of 35 elite gold producer stocks.Bulls see Hemlo Mining as a rerating story after the South-Rim assays, while bears point to the mixed five-year track record. Which side does the current valuation actually reward?
Price-to-Earnings of 110x: Is it justified?
On simple valuation math, Hemlo Mining looks expensive at a P/E of 110x, especially with the share price at CA$8.38 and peers trading on far lower earnings multiples.
The P/E ratio compares what investors are paying today for each dollar of profit. For a gold producer like Hemlo Mining, a high multiple often reflects expectations for strong future earnings, a prized asset base or both. With HMMC only recently becoming profitable and carrying a P/E several times higher than typical metals and mining peers, the market is putting a lot of weight on its forward profit profile.
Relative to the Canadian Metals and Mining industry average P/E of 16.9x and a peer group average of 25.3x, Hemlo Mining trades at a very rich earnings multiple. The estimated fair P/E of 21x also sits far below the current 110x level, which suggests meaningful compression is a possible direction if the share price and earnings do not move in step.
Explore the SWS fair ratio for Hemlo Mining.
Result: Price-to-Earnings of 110x (OVERVALUED)
Still, Hemlo Mining faces real pressure if the South-Rim assays disappoint on follow-up drilling, or if the recent 1-year share surge reverses sentiment.
Find out about the key risks to this Hemlo Mining narrative.
Another view on Hemlo Mining's value
A very different picture comes from our DCF model. On this approach, Hemlo Mining at CA$8.38 is trading about 38.5% below an estimated future cash flow value of CA$13.62, which presents the stock as undervalued rather than simply expensive on a 110x P/E. That gap raises a simple question: Is the market overpaying for current earnings or underpricing the long term cash flow story?
Look into how the SWS DCF model arrives at its fair value.
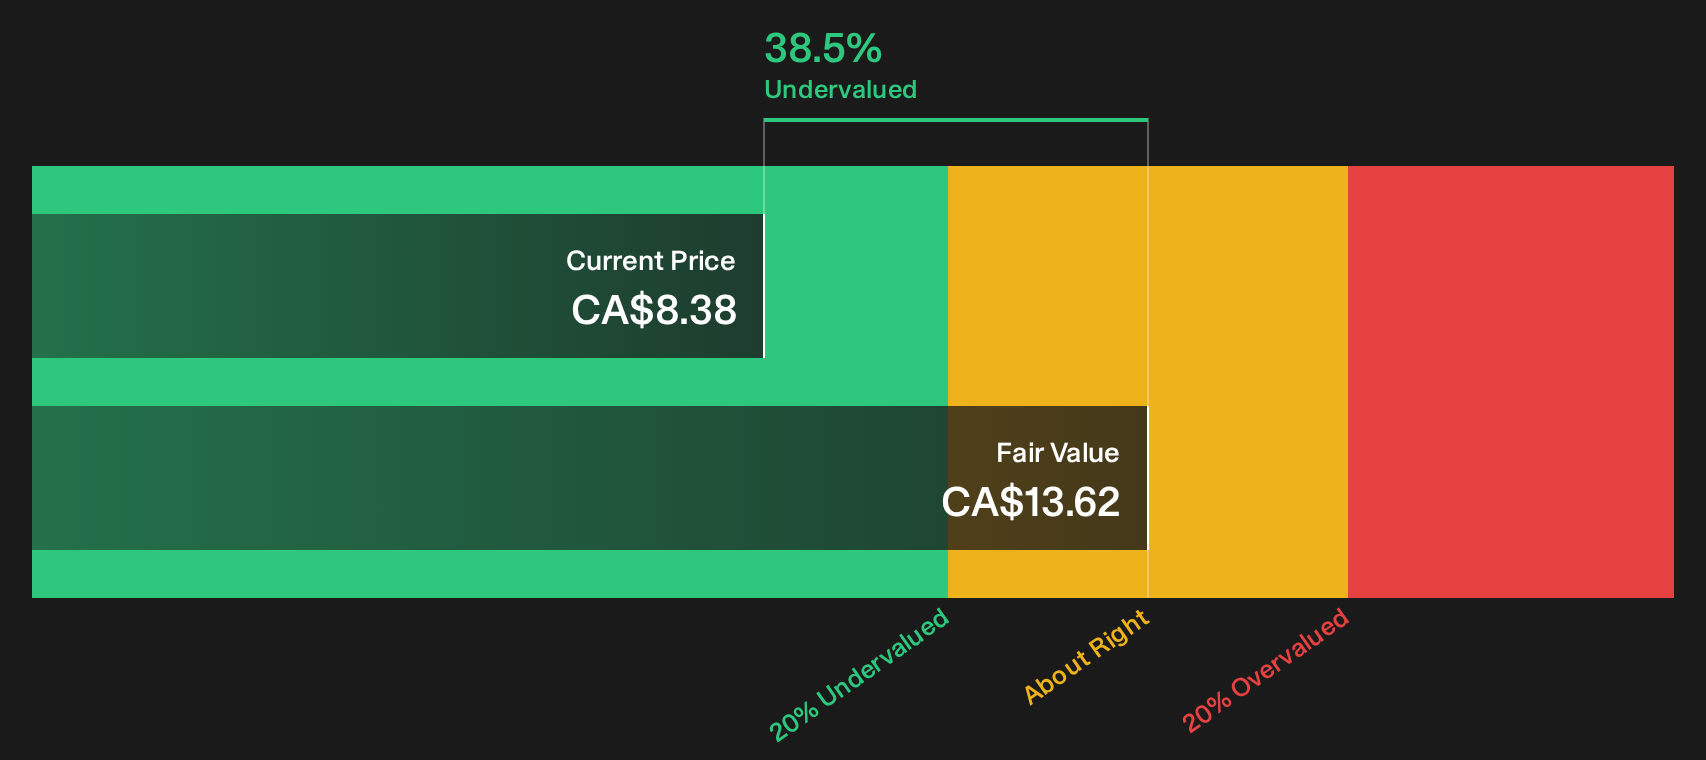
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hemlo Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Hemlo Mining's valuation and drilling results can pull you in both directions, so move quickly, review the full data set, and weigh the 3 key rewards and 2 important warning signs
Looking for more ideas beyond Hemlo Mining?
If Hemlo Mining has your attention, do not stop there. Broaden your watchlist now so you are not chasing the next move after it has already happened.
- Target potential mispricing by scanning a focused set of companies that screens for 5 high quality undervalued stocks.
- Stack your watchlist with resilient payers by reviewing income opportunities across a curated group of 2 dividend fortresses.
- Protect your downside first by filtering for businesses with robust finances through a list of solid balance sheet and fundamentals (7 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com